


Parametry
- 220 stron
- 8 godzin czytania
Więcej o książce
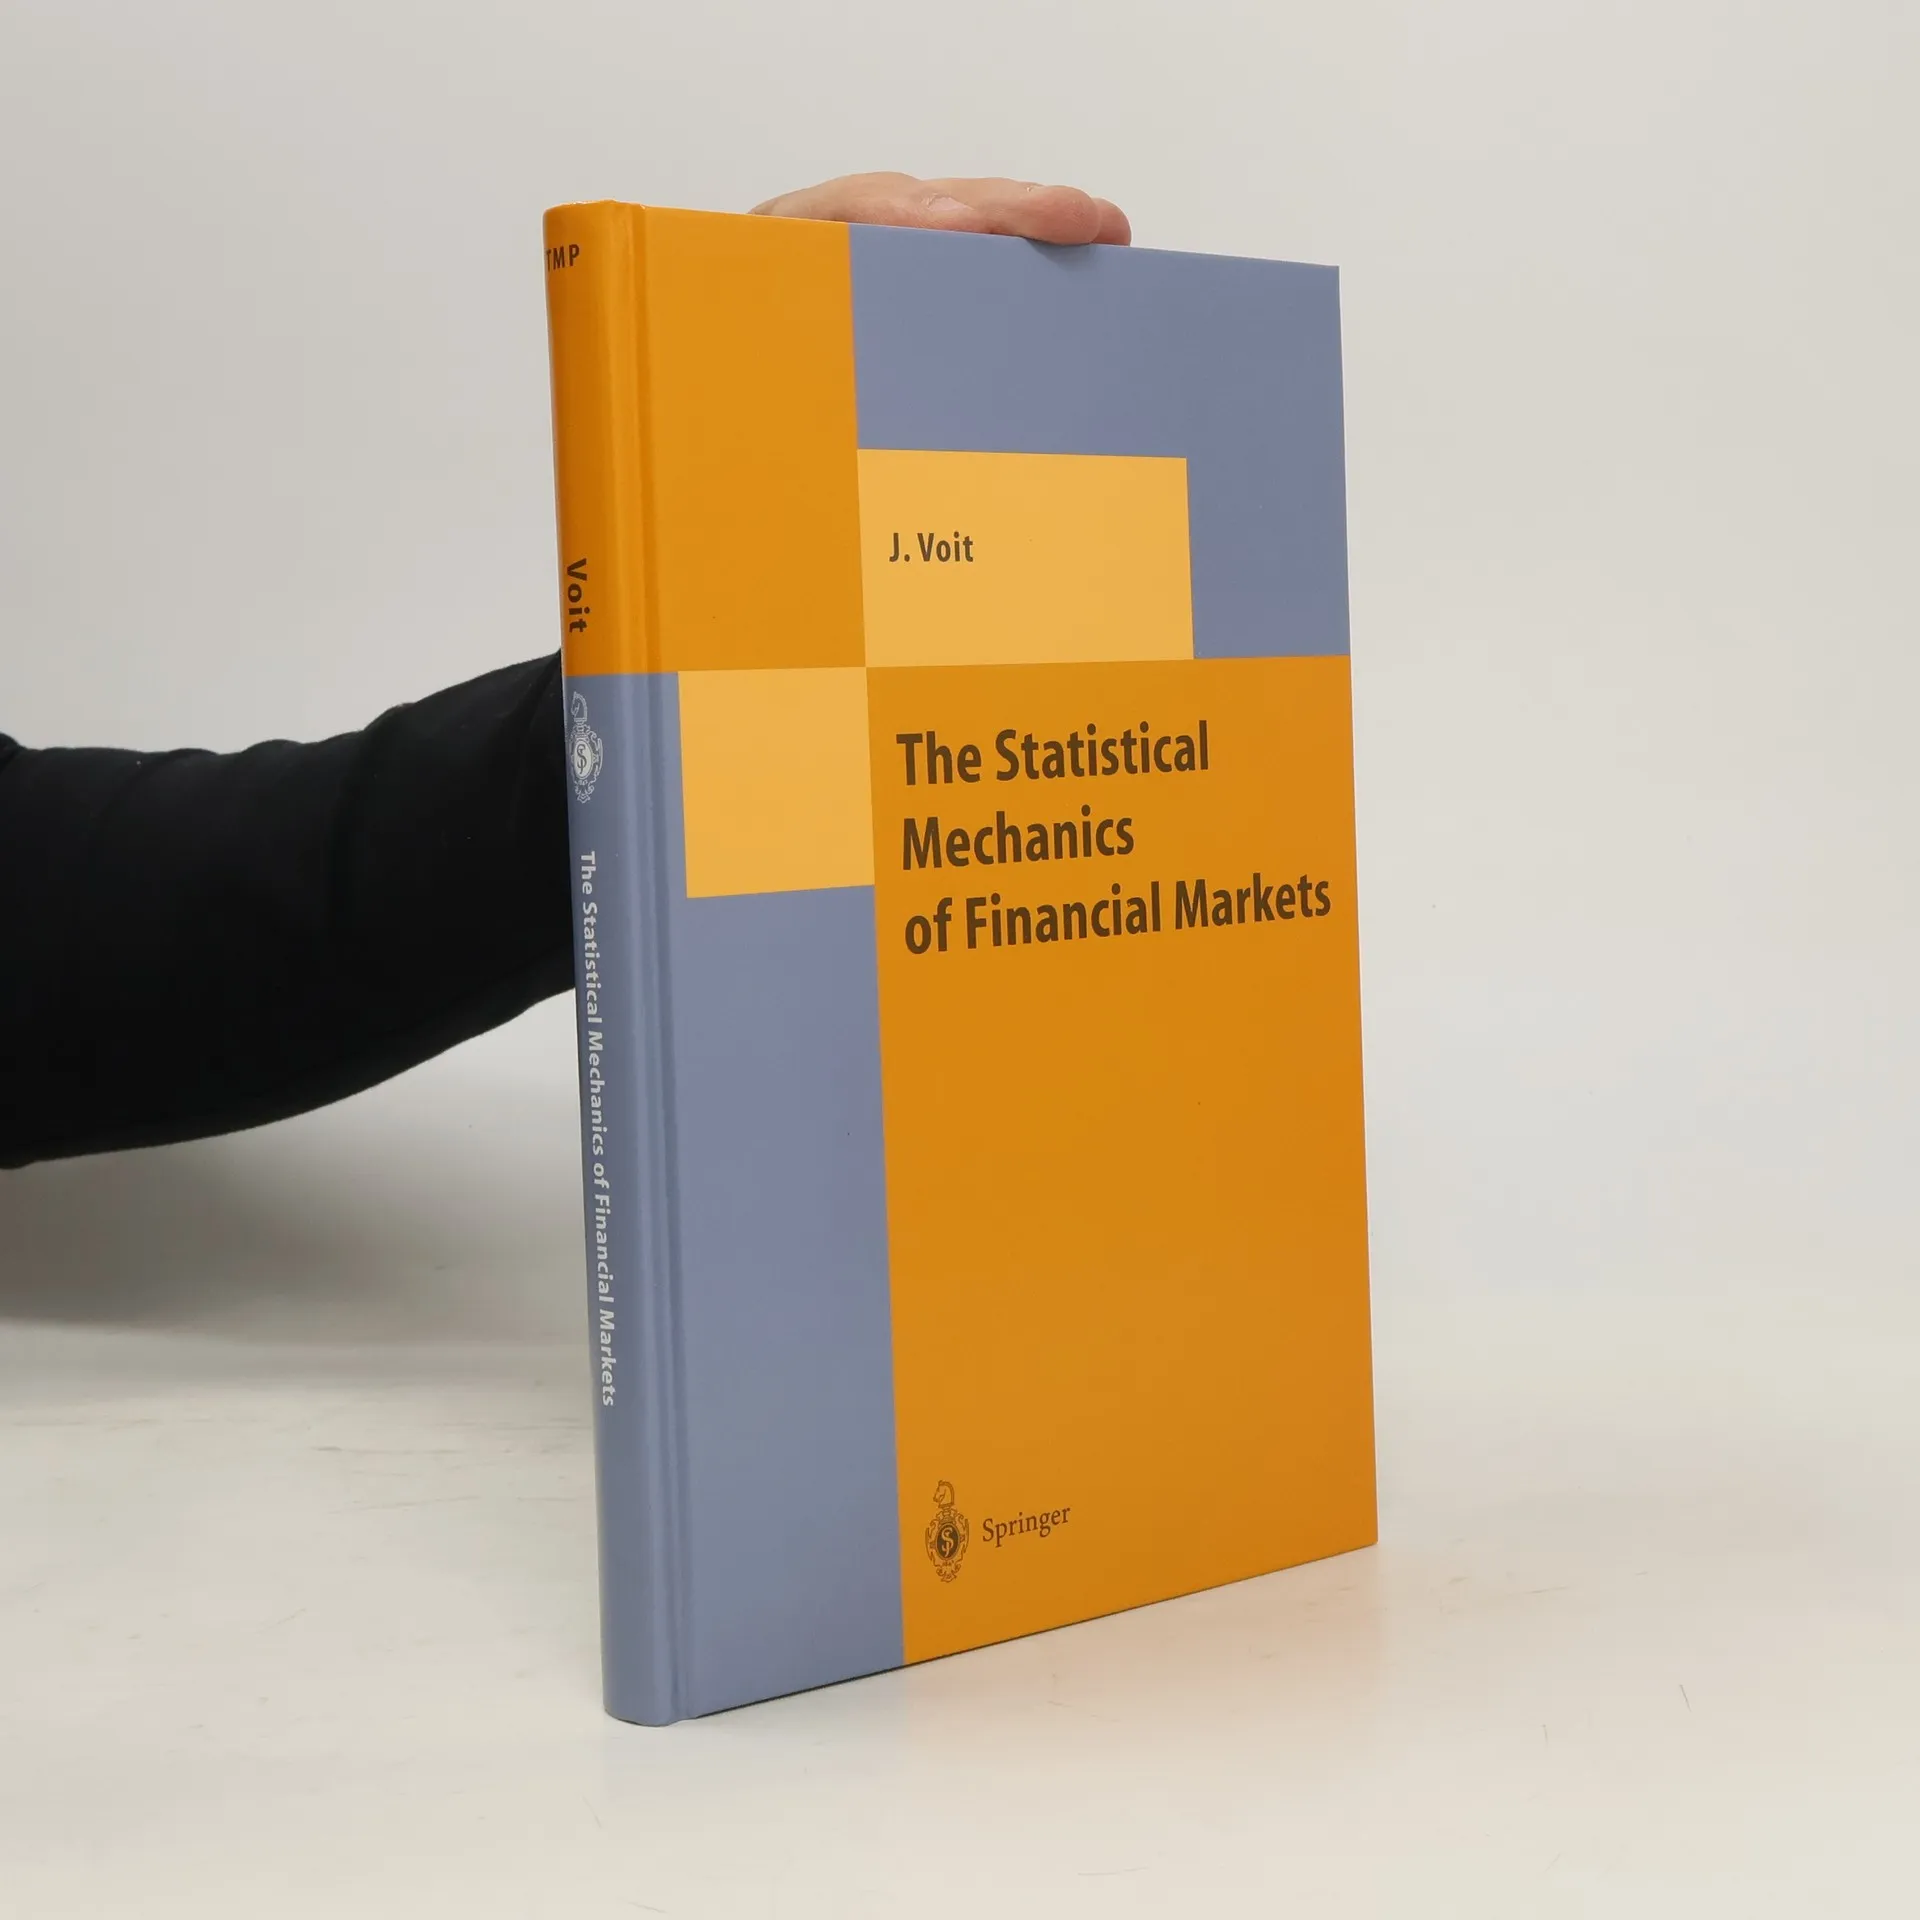
A careful examination of the interaction between physics and finance. It takes a look at the 100-year-long history of co-operation between the two fields and goes on to provide new research results on capital markets - taken from the field of statistical physics. The random walk model, well known in physics, is one good example of where the two disciplines meet. In the world of finance it is the basic model upon which the Black-Scholes theory of option pricing and hedging has been built. The underlying assumptions are discussed using empirical financial data and analogies to physical models such as fluid flows, turbulence, or superdiffusion. On this basis, new theories of derivative pricing and risk control can be formulated.
Zakup książki
The statistical mechanics of capital markets, Johannes Voit
- Język

- Rok wydania
- 2001
- Oprawa
- (twarda)
Metody płatności
Brakuje nam tutaj Twojej recenzji.
- Tytuł
- The statistical mechanics of capital markets
- Język
- angielski
- Autorzy
- Johannes Voit
- Wydawca
- Springer
- Rok wydania
- 2001
- Oprawa
- twarda
- Liczba stron
- 220
- ISBN10
- 3540414096
- ISBN13
- 9783540414094
- Seria
- Tagi
- Podręczniki, Biznes, Nauki przyrodnicze, Nauka, Podręczniki matematyki, Finanse, Podręczniki fizyki
- Ocena
- 4,2 z 5
- Opis
- A careful examination of the interaction between physics and finance. It takes a look at the 100-year-long history of co-operation between the two fields and goes on to provide new research results on capital markets - taken from the field of statistical physics. The random walk model, well known in physics, is one good example of where the two disciplines meet. In the world of finance it is the basic model upon which the Black-Scholes theory of option pricing and hedging has been built. The underlying assumptions are discussed using empirical financial data and analogies to physical models such as fluid flows, turbulence, or superdiffusion. On this basis, new theories of derivative pricing and risk control can be formulated.