

Więcej o książce
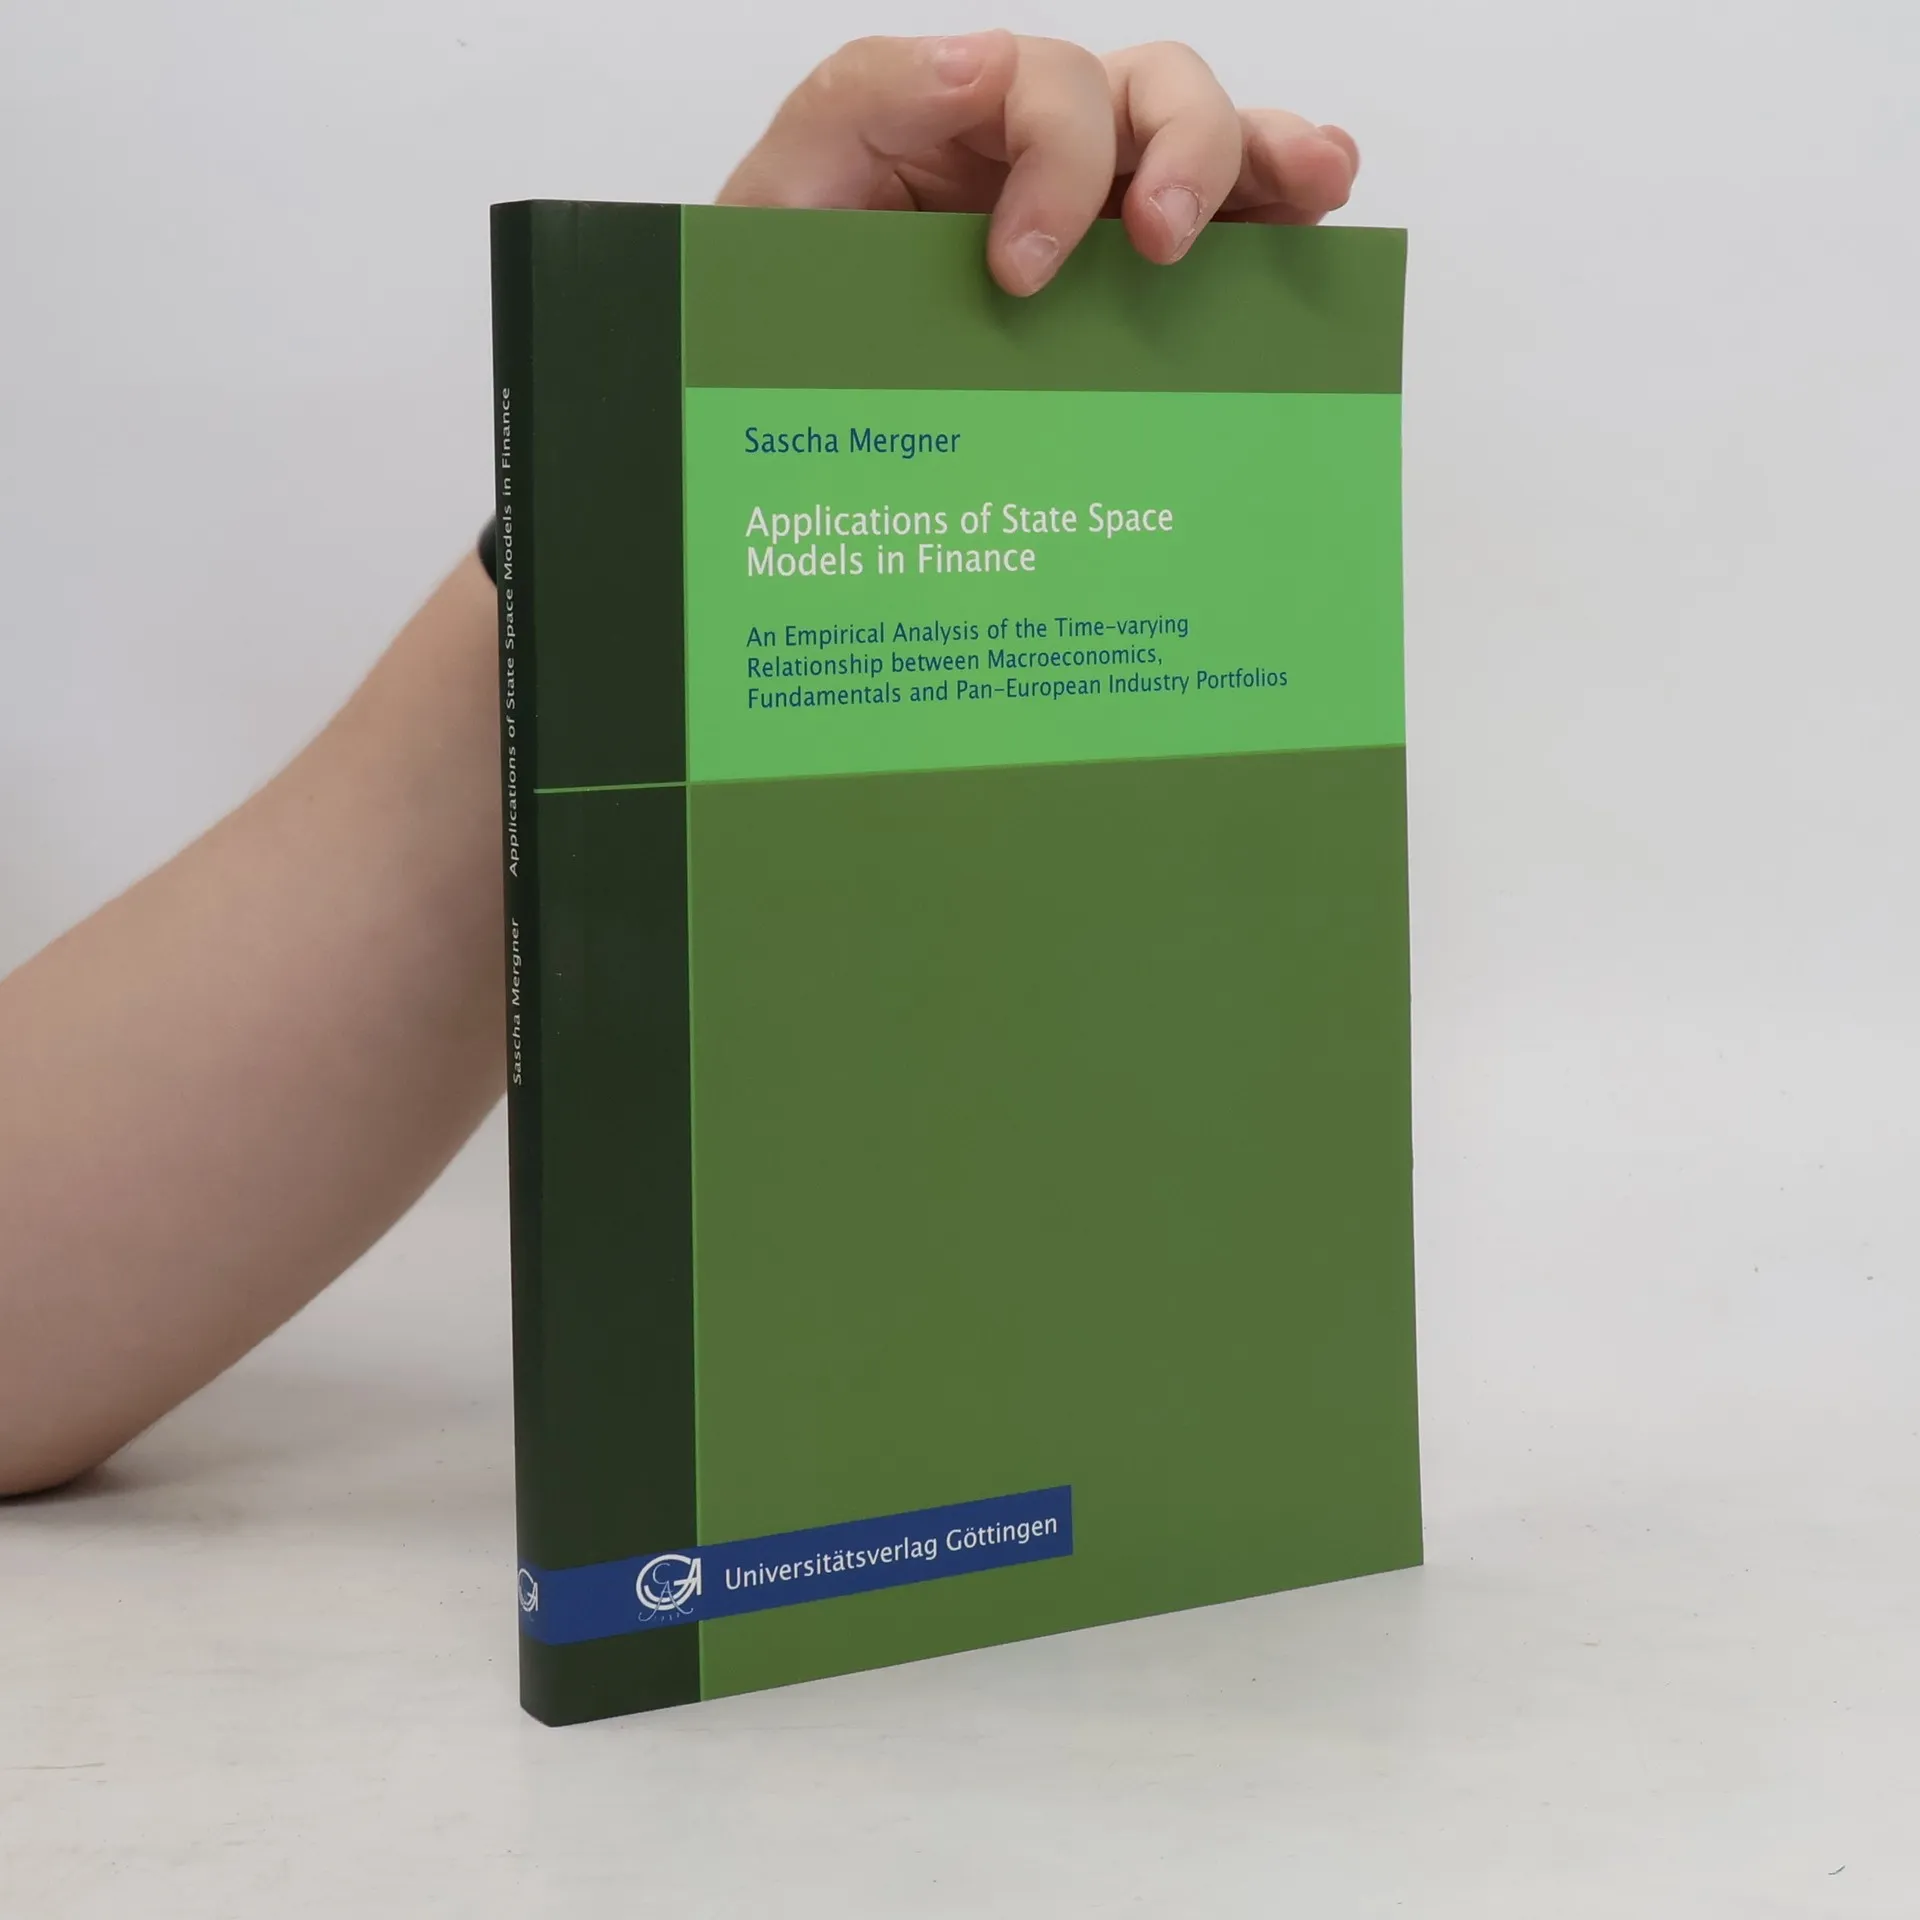
State space models play a key role in the estimation of time-varying sensitivities in financial markets. The objective of this book is to analyze the relative merits of modern time series techniques, such as Markov regime switching and the Kalman filter, to model structural changes in the context of widely used concepts in finance. The presented material will be useful for financial economists and practitioners who are interested in taking time-variation in the relationship between financial assets and key economic factors explicitly into account. The empirical part illustrates the application of the various methods under consideration. As a distinctive feature, it includes a comprehensive analysis of the ability of time-varying coefficient models to estimate and predict the conditional nature of systematic risks for European industry portfolios.
Zakup książki
Applications of state space models in finance, Sascha Mergner
- Język

- Rok wydania
- 2009
- Oprawa
- (miękka)
Metody płatności
Nikt jeszcze nie ocenił.
- Tytuł
- Applications of state space models in finance
- Język
- angielski
- Autorzy
- Sascha Mergner
- Wydawca
- Univ.-Verl. Göttingen
- Rok wydania
- 2009
- Oprawa
- miękka
- Liczba stron
- 235
- ISBN10
- 3941875221
- ISBN13
- 9783941875227
- Seria
- Kategorie
- Opis
- State space models play a key role in the estimation of time-varying sensitivities in financial markets. The objective of this book is to analyze the relative merits of modern time series techniques, such as Markov regime switching and the Kalman filter, to model structural changes in the context of widely used concepts in finance. The presented material will be useful for financial economists and practitioners who are interested in taking time-variation in the relationship between financial assets and key economic factors explicitly into account. The empirical part illustrates the application of the various methods under consideration. As a distinctive feature, it includes a comprehensive analysis of the ability of time-varying coefficient models to estimate and predict the conditional nature of systematic risks for European industry portfolios.