

Parametry
Więcej o książce
This textbook guides readers from microeconomic principles to modern asset pricing theory, skillfully connecting topics traditionally explored by general economic theorists and financial economists. Through a series of clearly explained steps, it demonstrates how the first welfare theorem applies to asset pricing theory. The exploration of Radner economies and von Neumann-Morgenstern decision theory culminates in Wilson's mutuality principle and the consumption-based CAPM, which is then placed in a dynamic context alongside term structure models. The text thoroughly addresses the empirical limitations of standard asset pricing models and reviews two decades of research aimed at aligning theory with real-world observations. Current concerns such as habit formation, heterogeneity, demographic effects, changing tax regimes, market frictions, and the implications of prospect theory for asset pricing are examined. Targeted at master's or Ph.D. students in financial economics, this book also serves as a supplementary resource for advanced macroeconomics students and is relevant for finance professionals with a background in economics and mathematics. It includes problems with solutions and offers additional supporting materials for lecturers on an accompanying website.
Zakup książki
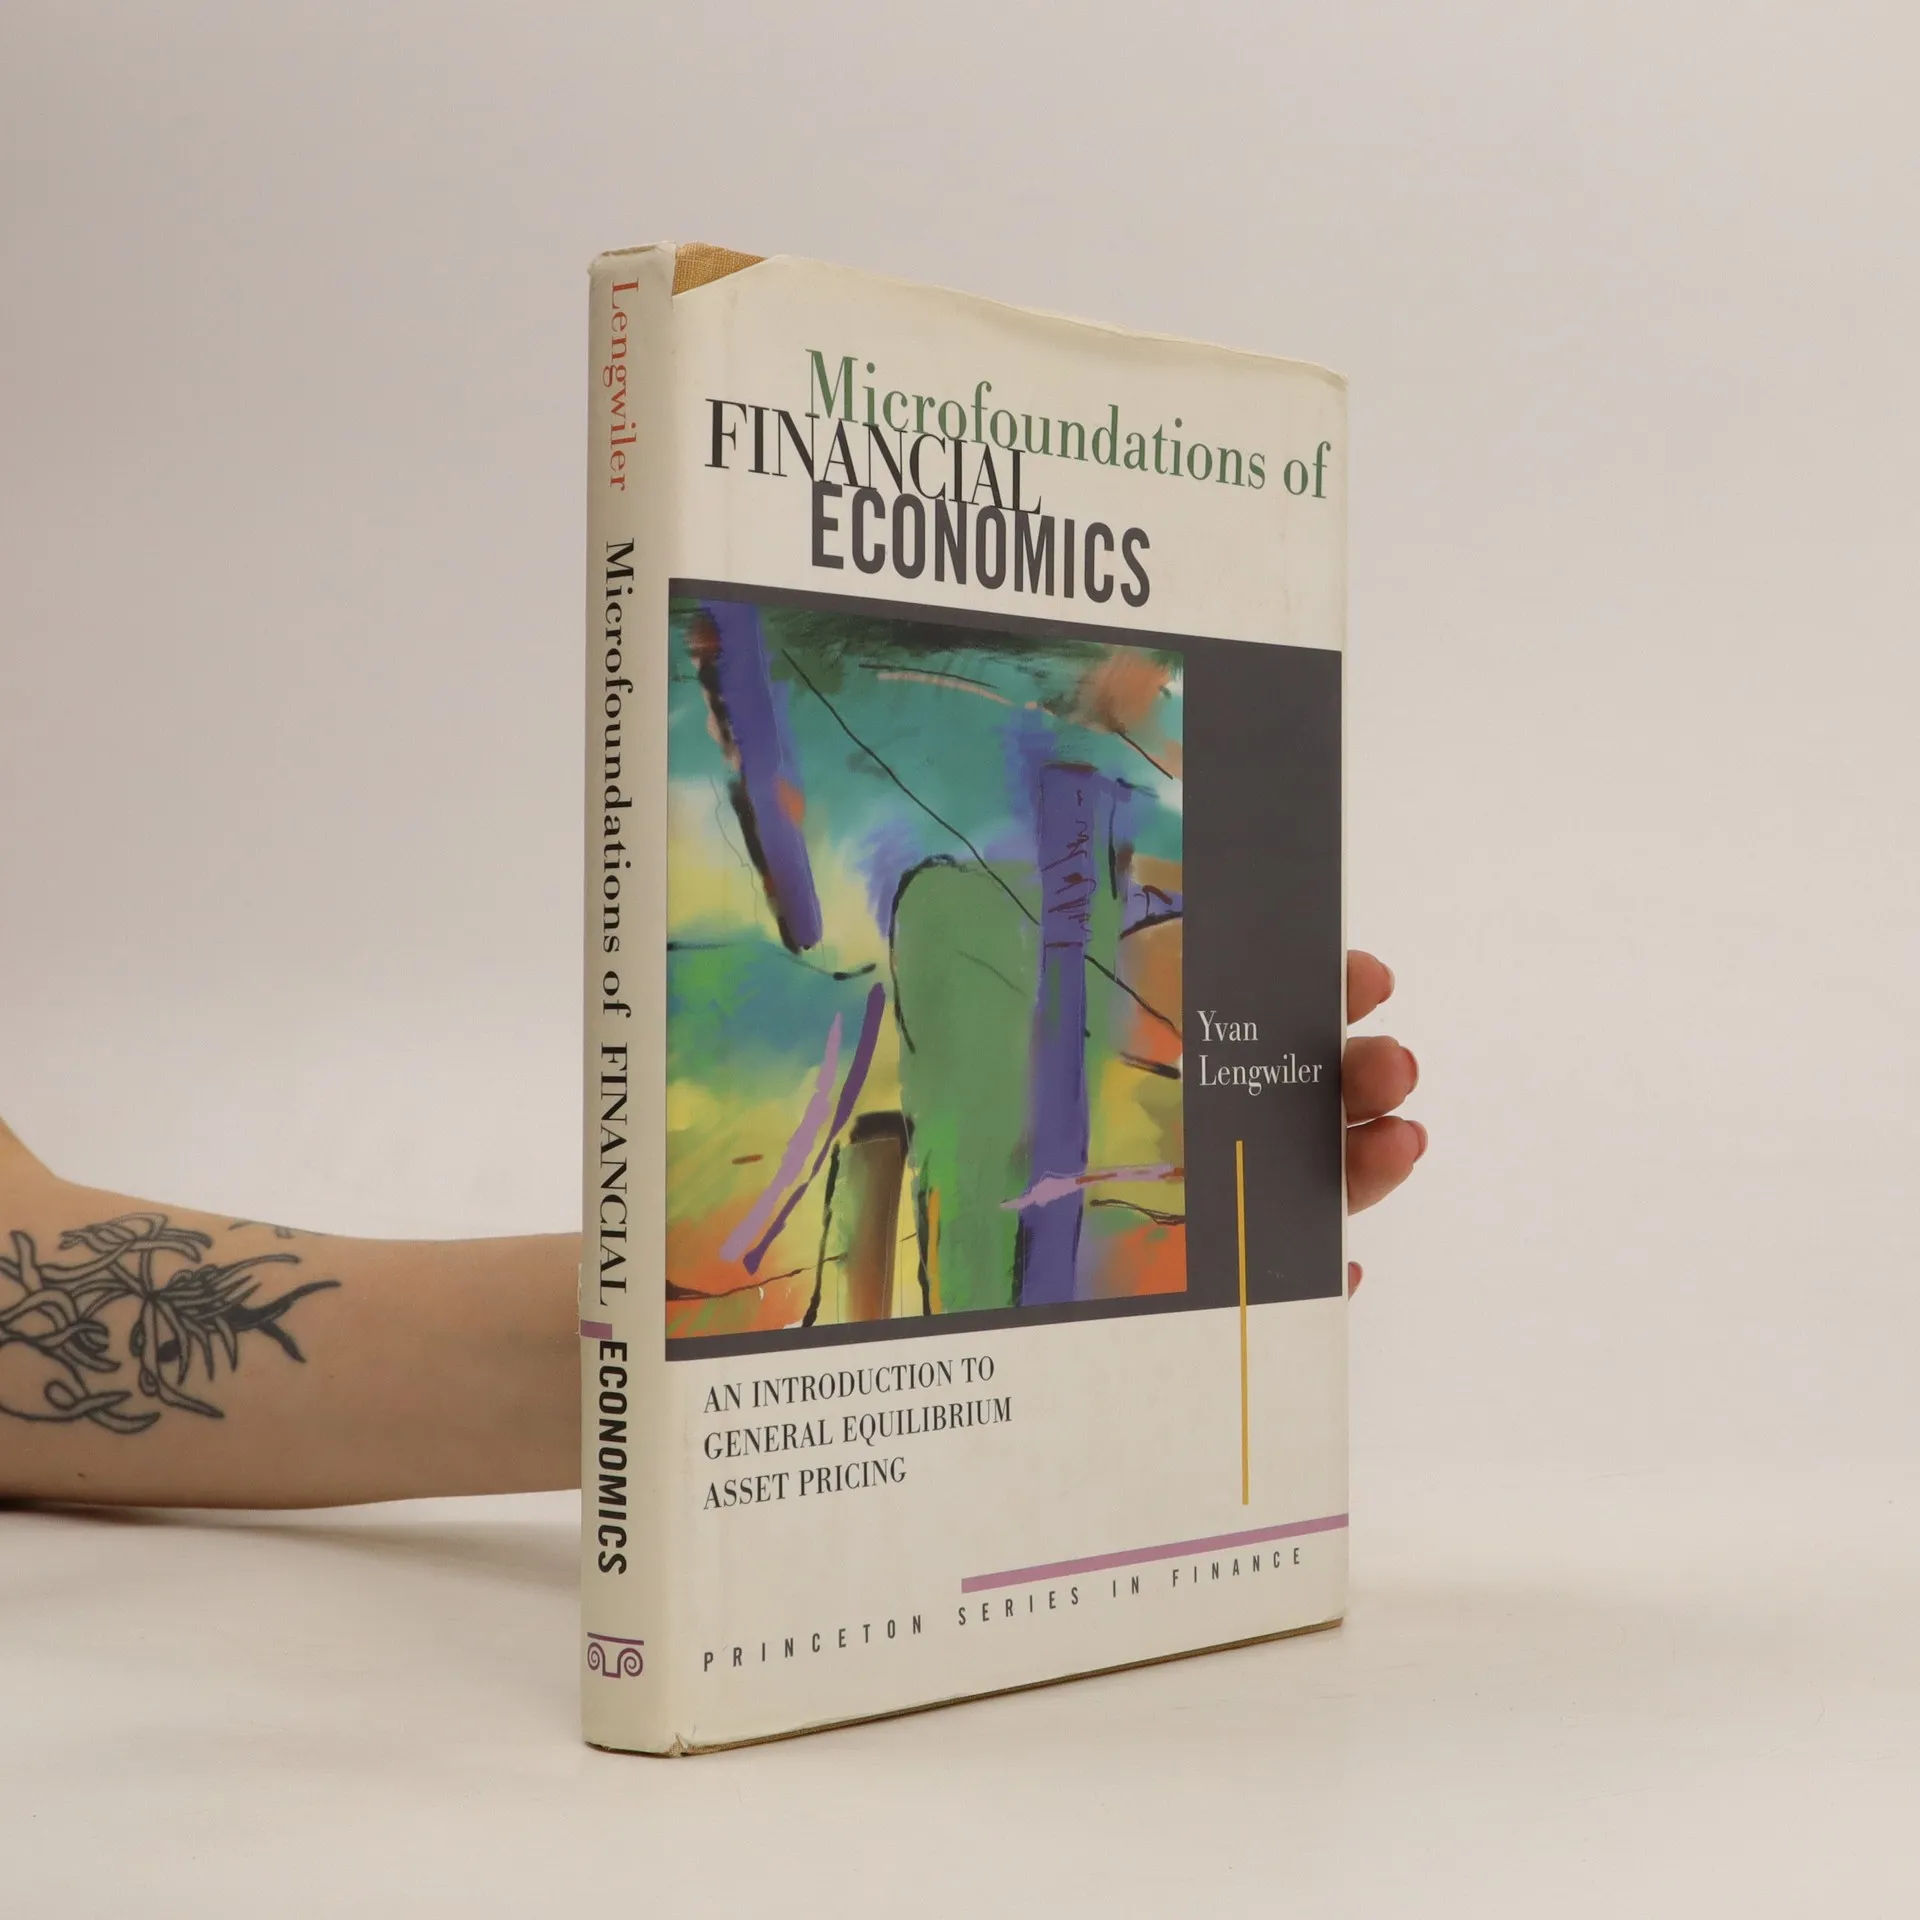
Microfoundations of Financial Economics, Yvan Lengwiler
- Język

- Rok wydania
- 2004
- Oprawa
- (twarda)
Metody płatności
Nikt jeszcze nie ocenił.
- Tytuł
- Microfoundations of Financial Economics
- Język
- angielski
- Autorzy
- Yvan Lengwiler
- Wydawca
- Princeton University Press
- Rok wydania
- 2004
- Oprawa
- twarda
- ISBN10
- 0691113157
- ISBN13
- 9780691113159
- Seria
- Tagi
- Podręczniki, Biznes
- Opis
- This textbook guides readers from microeconomic principles to modern asset pricing theory, skillfully connecting topics traditionally explored by general economic theorists and financial economists. Through a series of clearly explained steps, it demonstrates how the first welfare theorem applies to asset pricing theory. The exploration of Radner economies and von Neumann-Morgenstern decision theory culminates in Wilson's mutuality principle and the consumption-based CAPM, which is then placed in a dynamic context alongside term structure models. The text thoroughly addresses the empirical limitations of standard asset pricing models and reviews two decades of research aimed at aligning theory with real-world observations. Current concerns such as habit formation, heterogeneity, demographic effects, changing tax regimes, market frictions, and the implications of prospect theory for asset pricing are examined. Targeted at master's or Ph.D. students in financial economics, this book also serves as a supplementary resource for advanced macroeconomics students and is relevant for finance professionals with a background in economics and mathematics. It includes problems with solutions and offers additional supporting materials for lecturers on an accompanying website.