



Więcej o książce
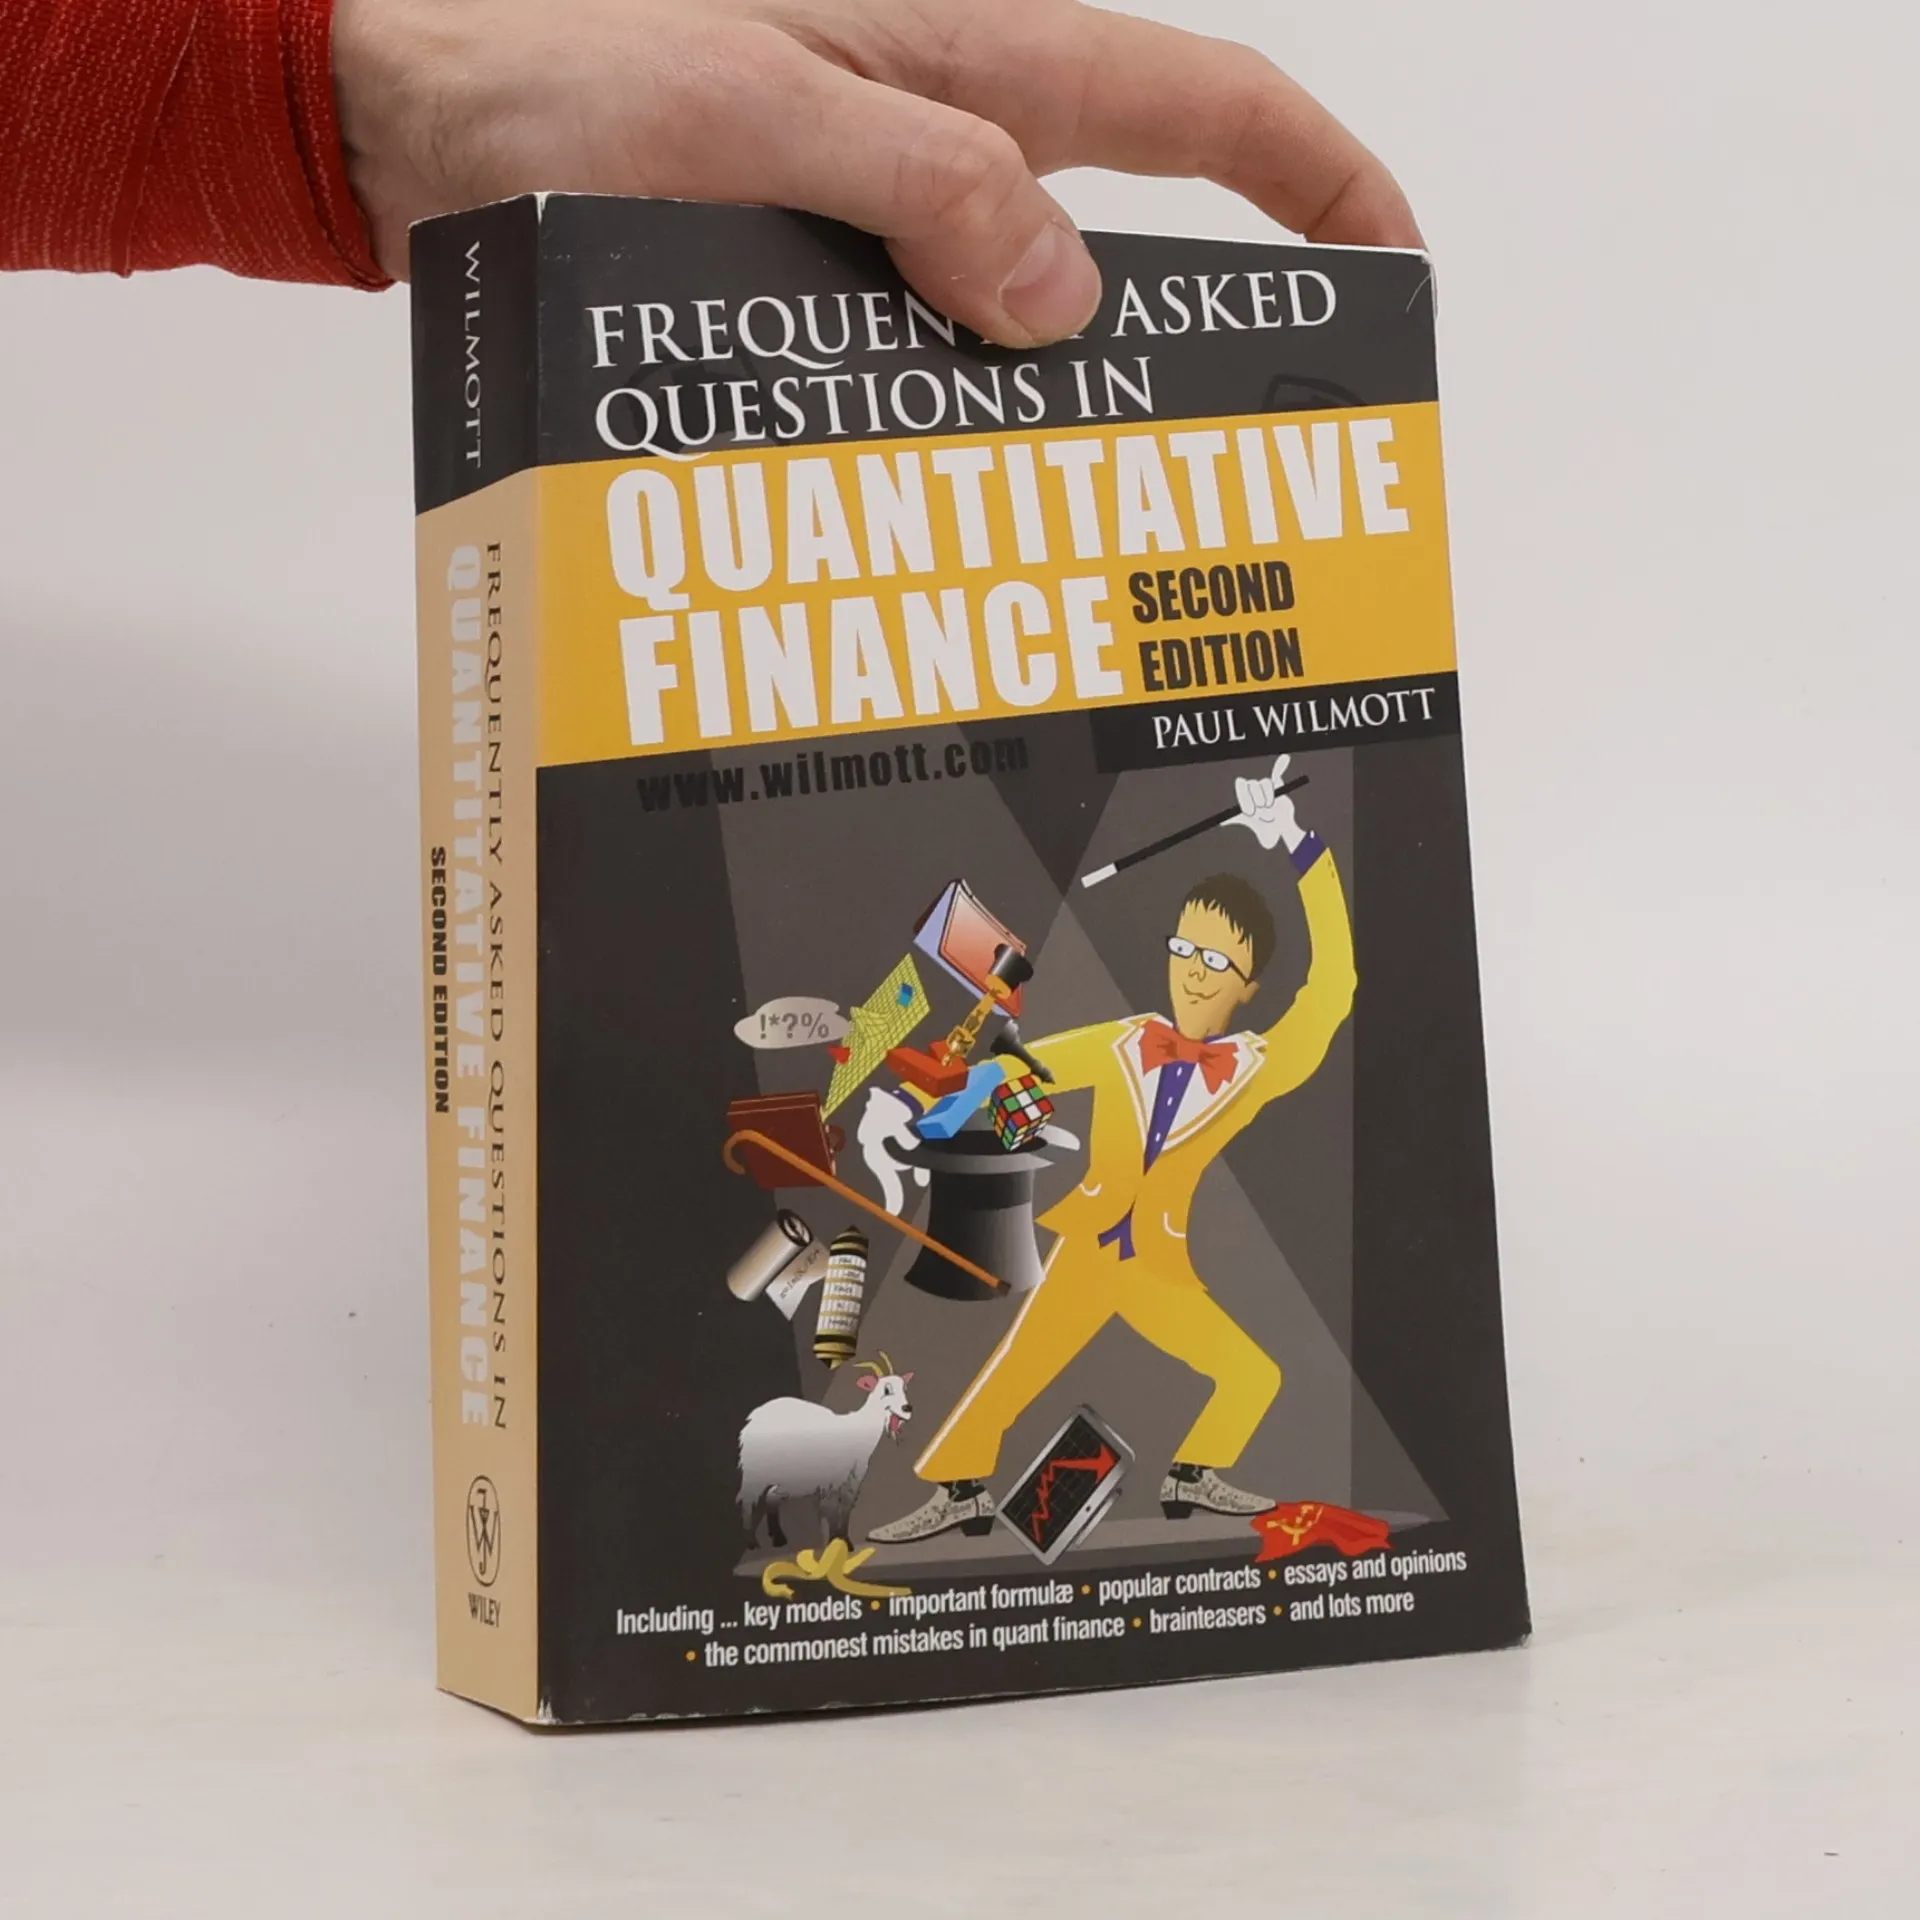
Getting agreement between finance theory and practice is crucial, especially with the derivatives market now vastly exceeding the underlying world economy. Derivatives have evolved from tools for managing financial risks to a dominant force in finance, placing significant responsibility on professionals in the field. In this second edition of Frequently Asked Questions in Quantitative Finance, the aim is to elevate quantitative finance from oversimplification while avoiding excessive complexity. The book advocates for a balanced approach, where models are both robust and comprehensible. It features essential FAQs and answers that bridge theory and practice, including multiple derivations of Black-Scholes, popular models, equations, formulae, and probability distributions. Additionally, it includes critical essays, brainteasers, and a section on common quant mistakes—knowledge that could save trillions of dollars. The content is designed to engage readers and highlight the fascinating aspects of this vital subject. Readers are encouraged to join discussions on wilmott.com to further explore these topics. The book encompasses key models, important formulae, a history of quantitative finance, and much more, making it a valuable resource for anyone in the industry.
Zakup książki
Frequently Asked Questions in Quantitative Finance, Paul Wilmott
- Język

- Rok wydania
- 2009
- Oprawa
- (miękka)
Metody płatności
Brakuje nam tutaj Twojej recenzji.
- Tytuł
- Frequently Asked Questions in Quantitative Finance
- Język
- angielski
- Autorzy
- Paul Wilmott
- Wydawca
- John Wiley & Sons
- Rok wydania
- 2009
- Oprawa
- miękka
- Liczba stron
- 608
- ISBN10
- 0470748753
- ISBN13
- 9780470748756
- Seria
- Ocena
- 4,1 z 5
- Opis
- Getting agreement between finance theory and practice is crucial, especially with the derivatives market now vastly exceeding the underlying world economy. Derivatives have evolved from tools for managing financial risks to a dominant force in finance, placing significant responsibility on professionals in the field. In this second edition of Frequently Asked Questions in Quantitative Finance, the aim is to elevate quantitative finance from oversimplification while avoiding excessive complexity. The book advocates for a balanced approach, where models are both robust and comprehensible. It features essential FAQs and answers that bridge theory and practice, including multiple derivations of Black-Scholes, popular models, equations, formulae, and probability distributions. Additionally, it includes critical essays, brainteasers, and a section on common quant mistakes—knowledge that could save trillions of dollars. The content is designed to engage readers and highlight the fascinating aspects of this vital subject. Readers are encouraged to join discussions on wilmott.com to further explore these topics. The book encompasses key models, important formulae, a history of quantitative finance, and much more, making it a valuable resource for anyone in the industry.