

Ocena książki
Więcej o książce
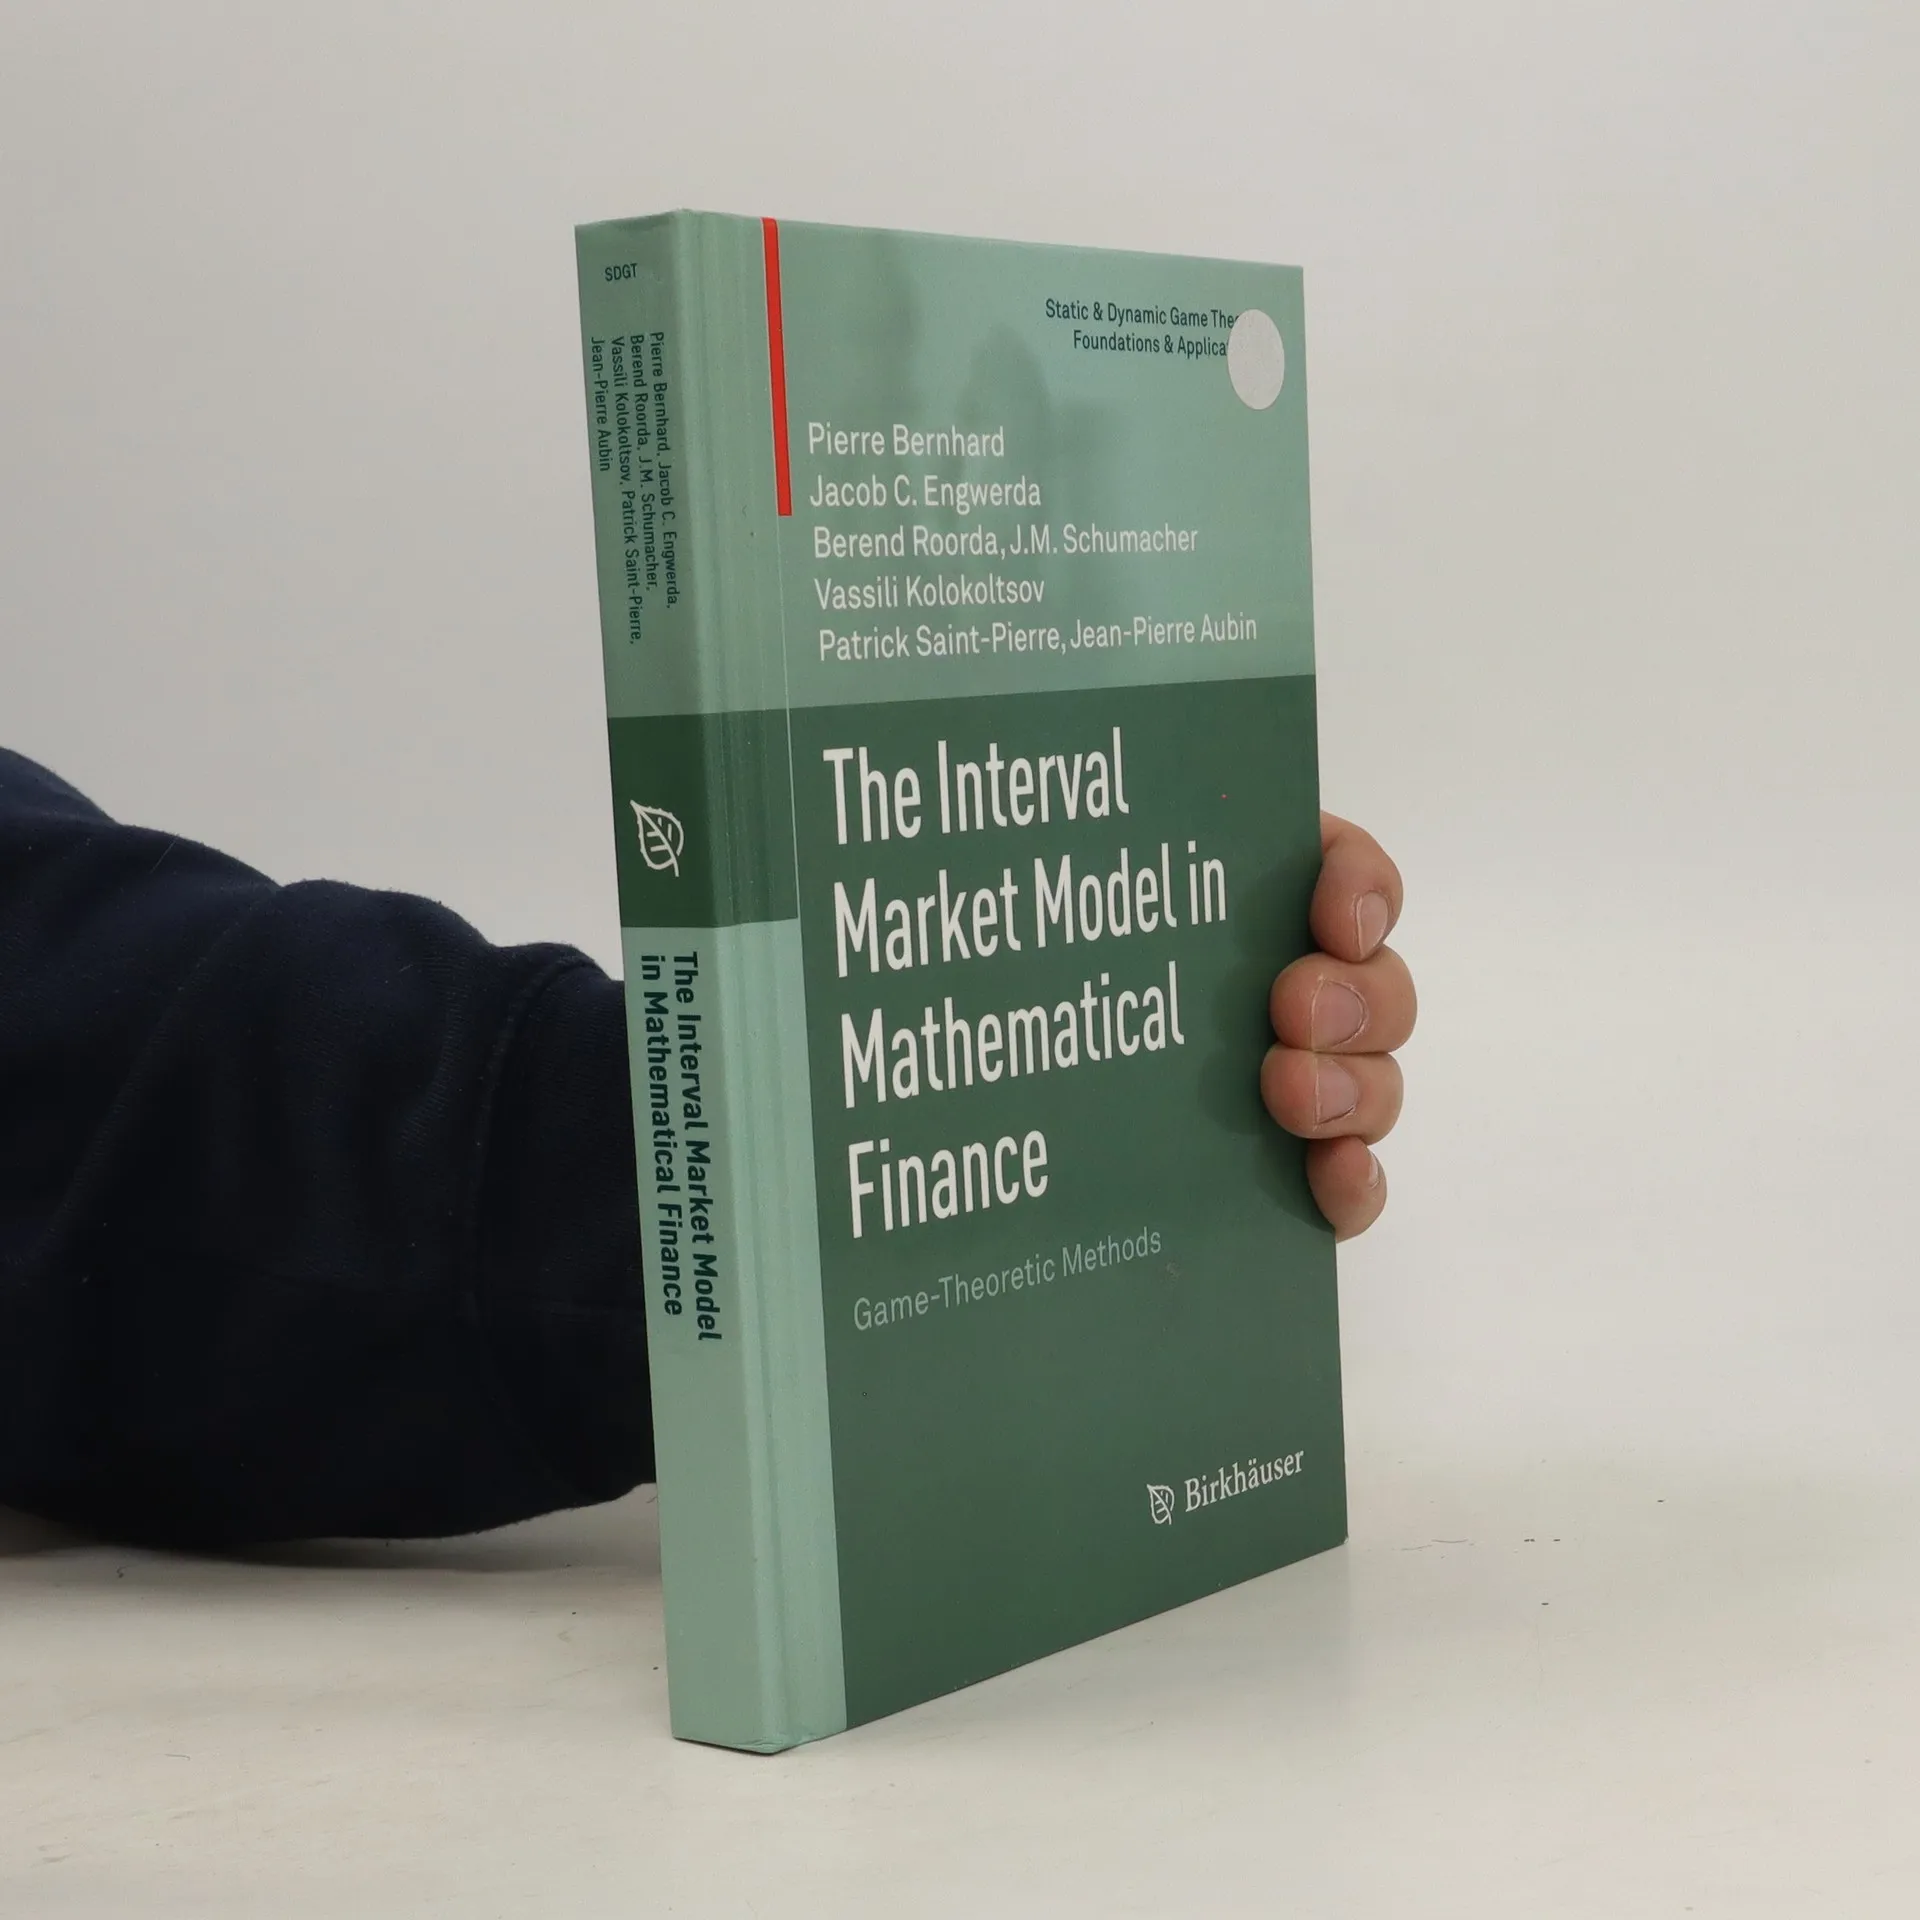
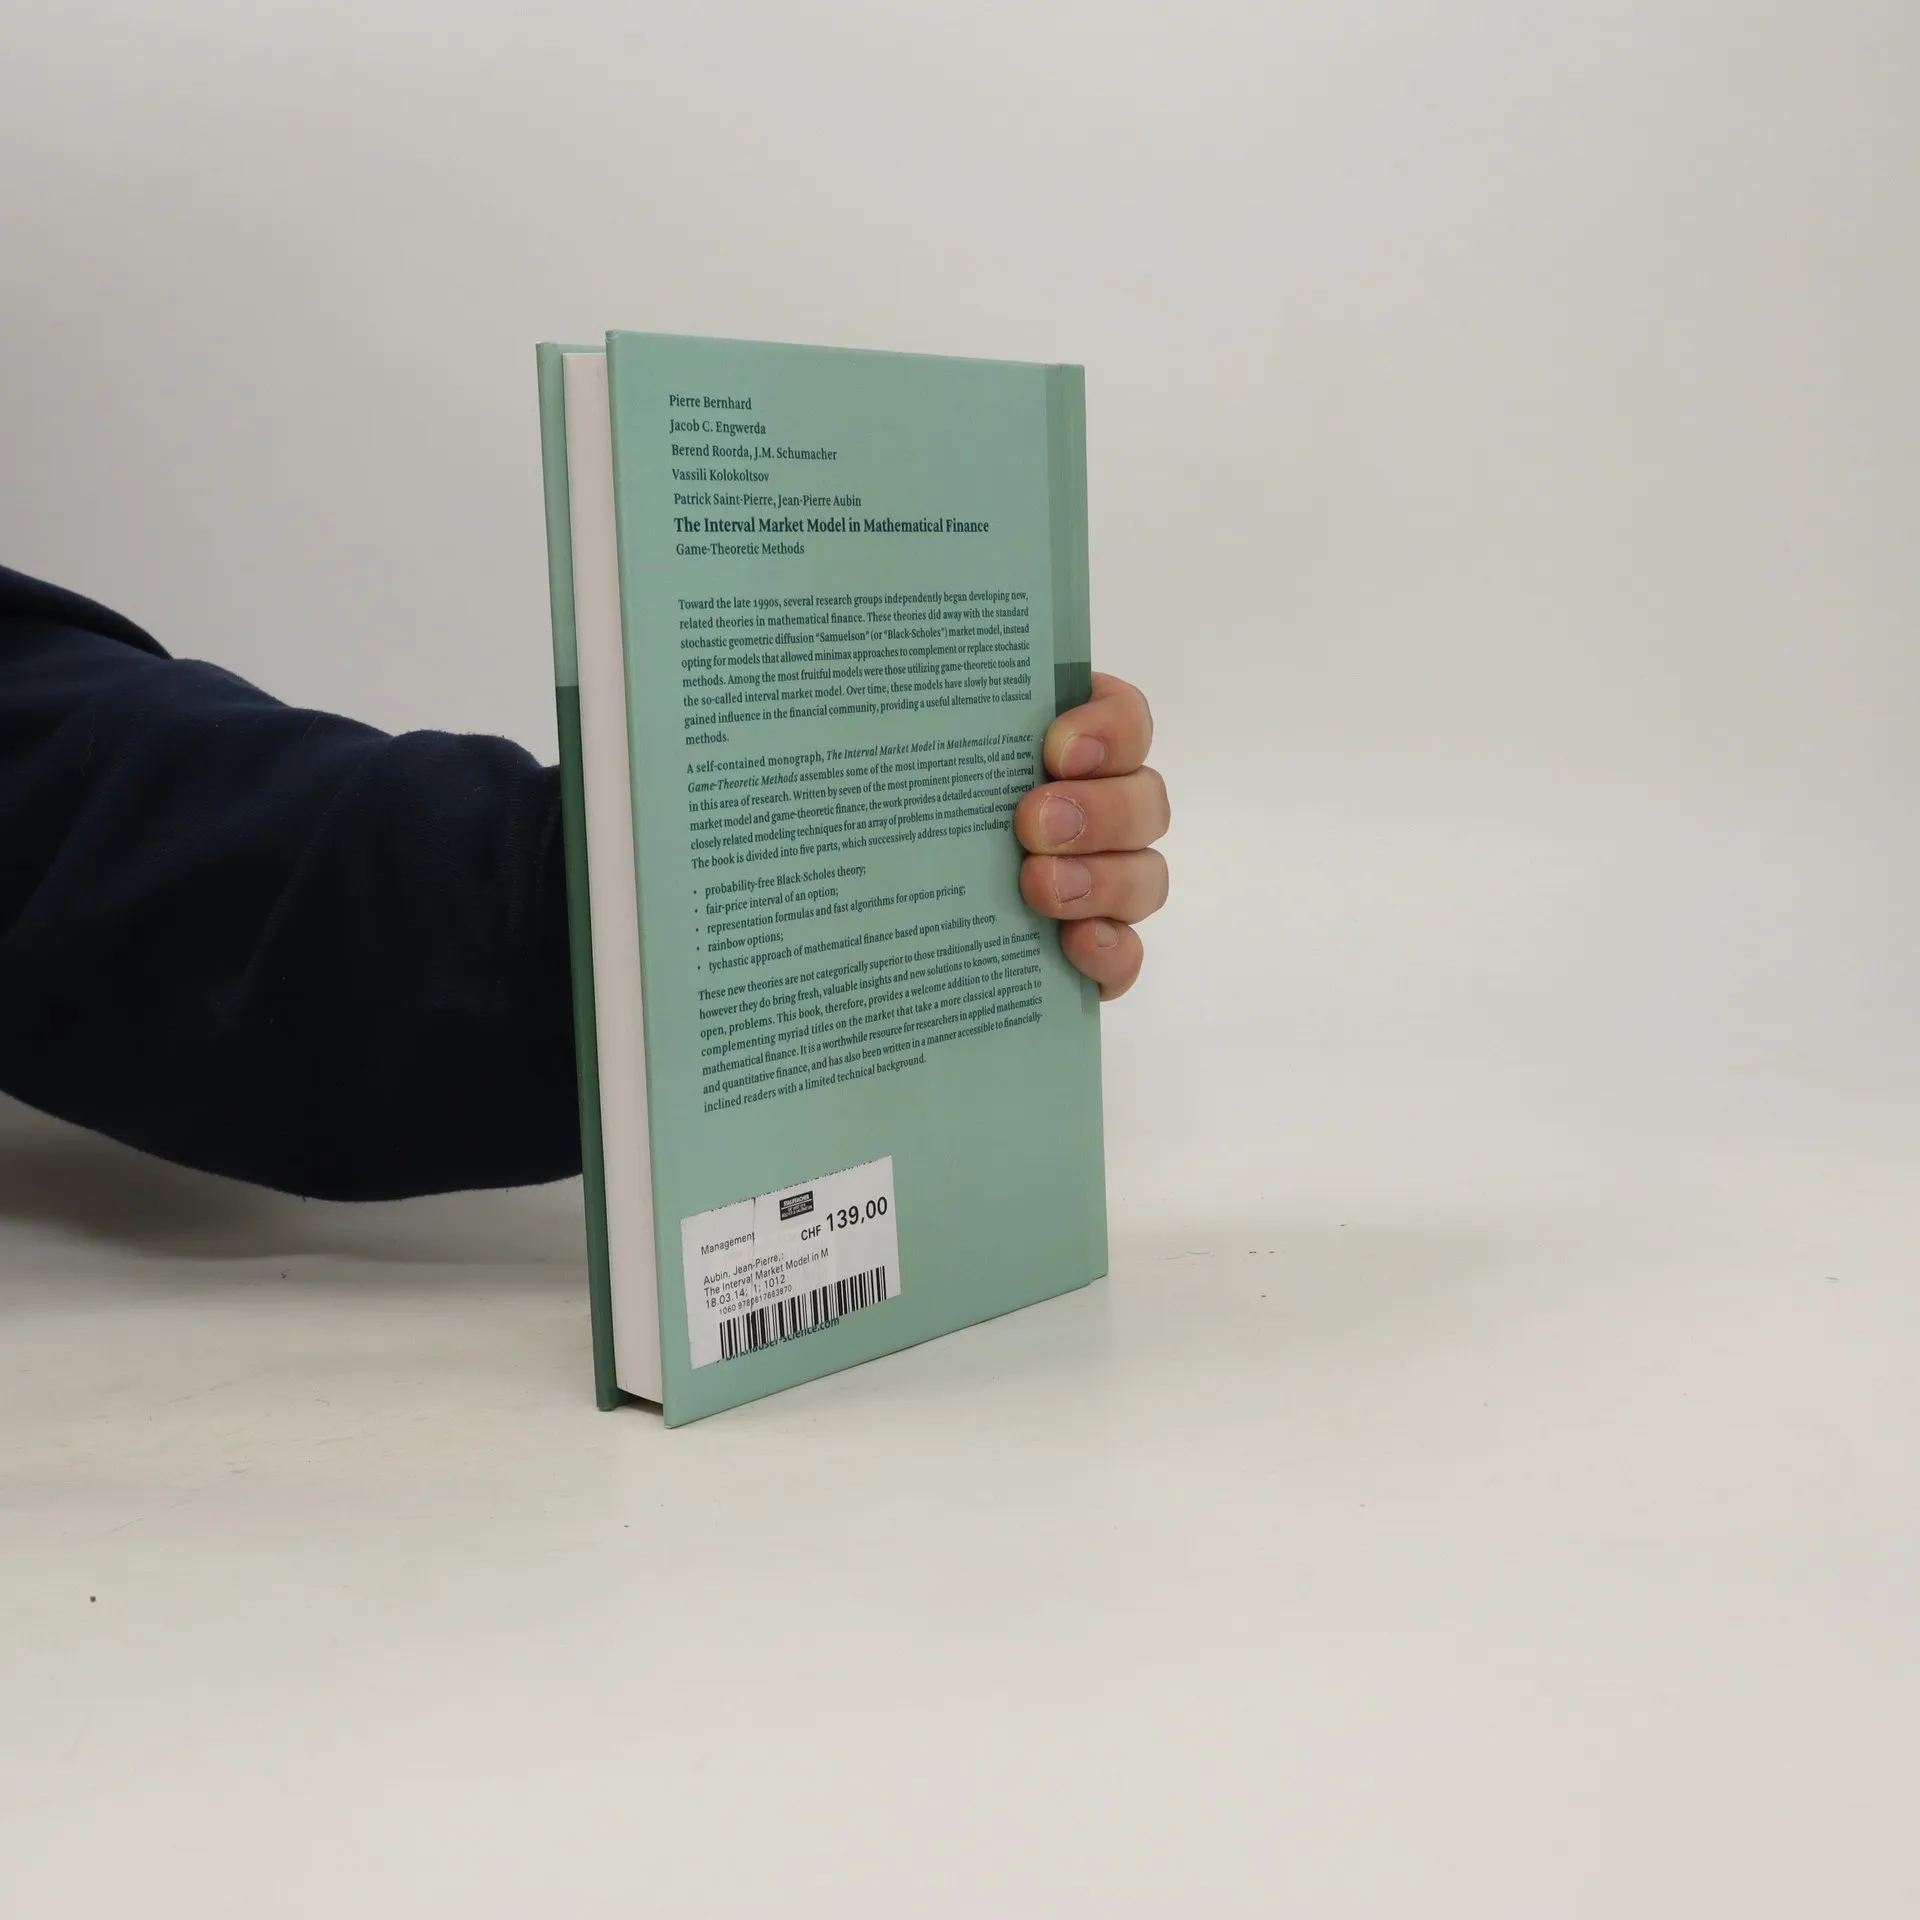
Toward the late 1990s, various research groups began developing new theories in mathematical finance that moved away from the traditional stochastic geometric diffusion market model, often associated with the Black-Scholes theory. These new models incorporated minimax approaches and utilized game-theoretic tools, including the interval market model, which have gained traction within the financial community as viable alternatives to classical methods. This self-contained monograph assembles significant results in this field, authored by seven leading pioneers of the interval market model and game-theoretic finance. The work provides a comprehensive overview of various modeling techniques applicable to mathematical economics. It is organized into five parts covering topics such as probability-free Black-Scholes theory, fair-price intervals of options, representation formulas and algorithms for option pricing, rainbow options, and the tychastic approach based on viability theory. This book enriches the existing literature by offering a fresh perspective on mathematical finance, making it a valuable resource for researchers in applied mathematics and quantitative finance, while also being accessible to readers with a limited technical background.
Zakup książki
The Interval Market Model In Mathematical Finance Gametheoretic Methods, kolektiv
- Język

- Rok wydania
- 2012
- Oprawa
- (twarda)
Metody płatności
Brakuje nam tutaj Twojej recenzji.
- Tytuł
- The Interval Market Model In Mathematical Finance Gametheoretic Methods
- Język
- angielski
- Autorzy
- kolektiv
- Wydawca
- Birkh User
- Rok wydania
- 2012
- Oprawa
- twarda
- Liczba stron
- 364
- ISBN10
- 0817683879
- ISBN13
- 9780817683870
- Seria
- Tagi
- Ocena
- 4 z 5
- Opis
- Toward the late 1990s, various research groups began developing new theories in mathematical finance that moved away from the traditional stochastic geometric diffusion market model, often associated with the Black-Scholes theory. These new models incorporated minimax approaches and utilized game-theoretic tools, including the interval market model, which have gained traction within the financial community as viable alternatives to classical methods. This self-contained monograph assembles significant results in this field, authored by seven leading pioneers of the interval market model and game-theoretic finance. The work provides a comprehensive overview of various modeling techniques applicable to mathematical economics. It is organized into five parts covering topics such as probability-free Black-Scholes theory, fair-price intervals of options, representation formulas and algorithms for option pricing, rainbow options, and the tychastic approach based on viability theory. This book enriches the existing literature by offering a fresh perspective on mathematical finance, making it a valuable resource for researchers in applied mathematics and quantitative finance, while also being accessible to readers with a limited technical background.