

Wyprzedane, ale poszukiwane!


Więcej o książce
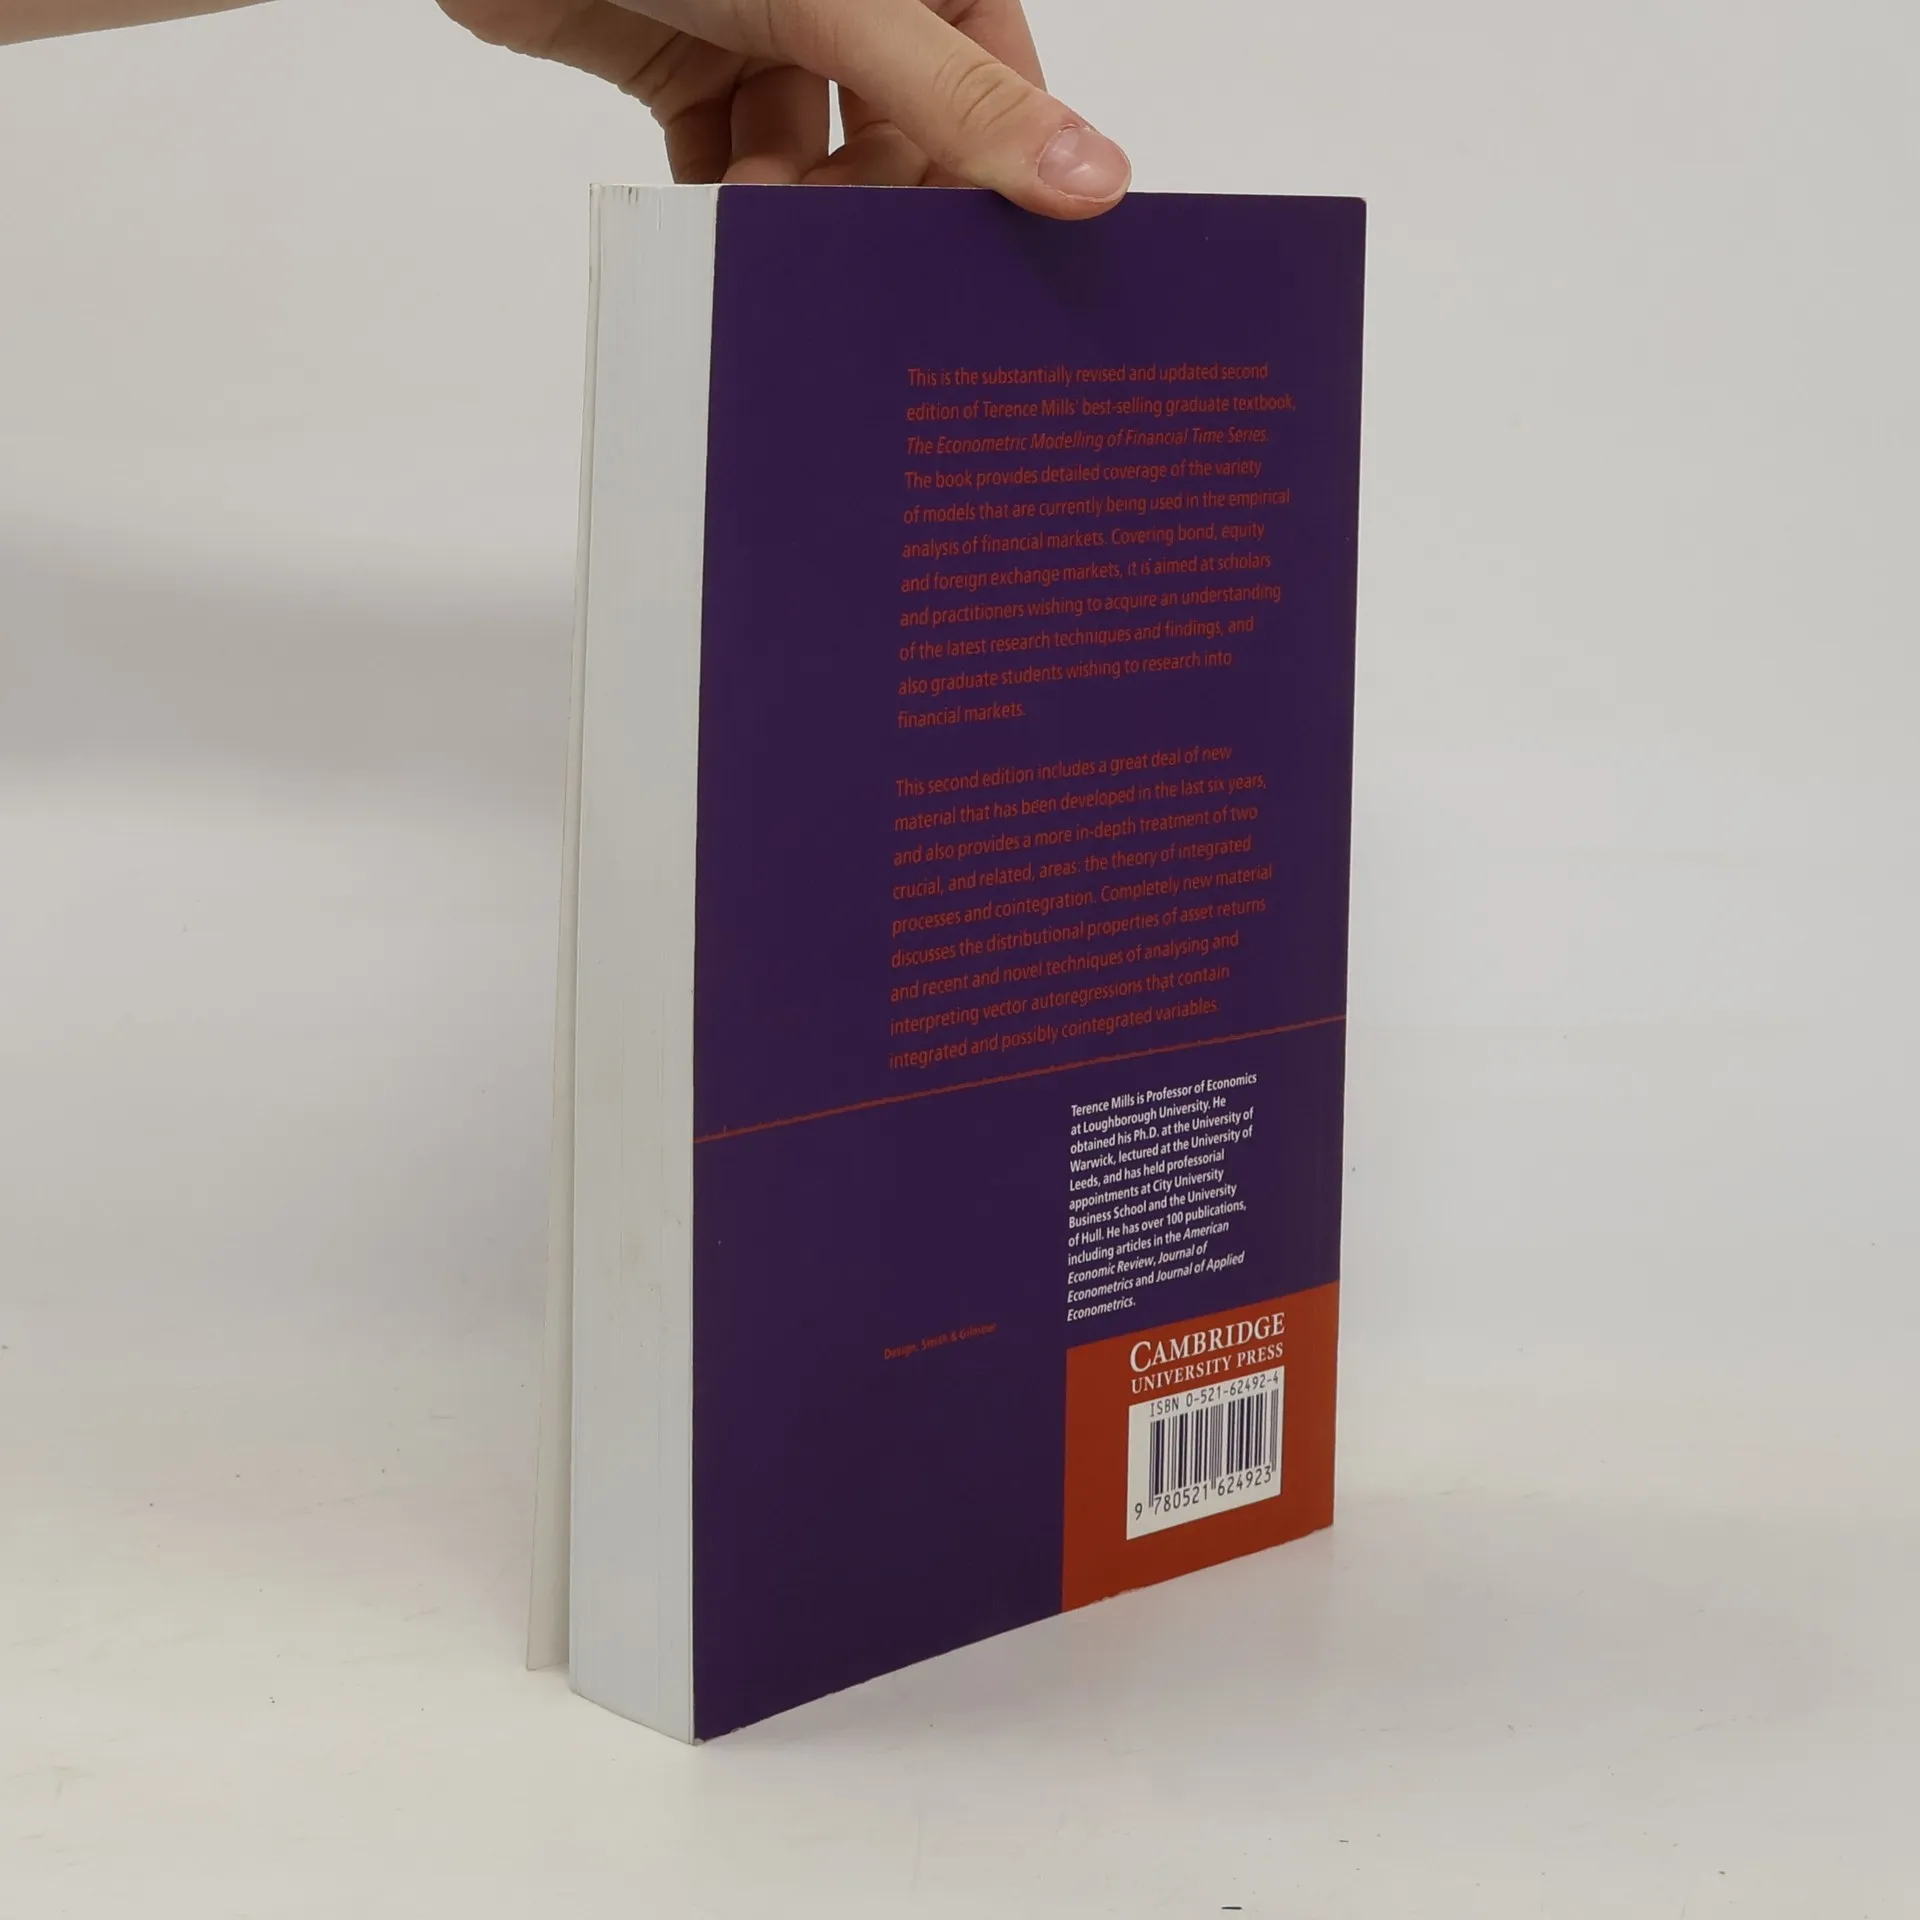
Fully revised and updated, the second edition of the best-selling The Econometric Modelling of Financial Time Series provides comprehensive coverage of the variety of models currently used in the empirical analysis of financial markets. Covering bond, equity and financial markets, it is essential for scholars and practitioners wishing to acquire an understanding of the latest research techniques and findings in the field, and also graduate students wishing to research in financial markets. It provides many examples to illustrate techniques that are only just emerging in the technical literature.
Zakup książki
The Econometric Modelling of Financial Time Series, Terence C. Mills
- Język

- Rok wydania
- 1999
- Oprawa
- (miękka)
Jak tylko się pojawi, wyślemy Ci wiadomość e-mail.
Metody płatności
Brakuje nam tutaj Twojej recenzji.
- Tytuł
- The Econometric Modelling of Financial Time Series
- Język
- angielski
- Autorzy
- Terence C. Mills
- Wydawca
- Cambridge University Press
- Rok wydania
- 1999
- Oprawa
- miękka
- Liczba stron
- 380
- ISBN10
- 0521624924
- ISBN13
- 9780521624923
- Seria
- Ocena
- 4,5 z 5
- Opis
- Fully revised and updated, the second edition of the best-selling The Econometric Modelling of Financial Time Series provides comprehensive coverage of the variety of models currently used in the empirical analysis of financial markets. Covering bond, equity and financial markets, it is essential for scholars and practitioners wishing to acquire an understanding of the latest research techniques and findings in the field, and also graduate students wishing to research in financial markets. It provides many examples to illustrate techniques that are only just emerging in the technical literature.