

Więcej o książce
The study of security market imperfections, namely the predictability of equity stock returns, is one of the fundamental research areas in financial modelling. These anomalies, which are not consistent with existing theories, concern the relation between stock returns and variables, such as firm size and earnings-to-price ratios, and seasonal effects, such as January and turn-of-the-month. This book provides the most complete and current account of work in the area. Leading academics and investment researchers have combined to produce a comprehensive coverage of the subject, including both cross-sectional and time series analyses, as well as discussing the measurement of risk and prediction models that have been used by institutional investors. The studies cover many worldwide markets including the US, Japan, Asia, and Europe. The book will be invaluable for courses in financial engineering, investment and portfolio management, and as a reference for investment professionals seeking an up-to-date source on return predictability.
Zakup książki
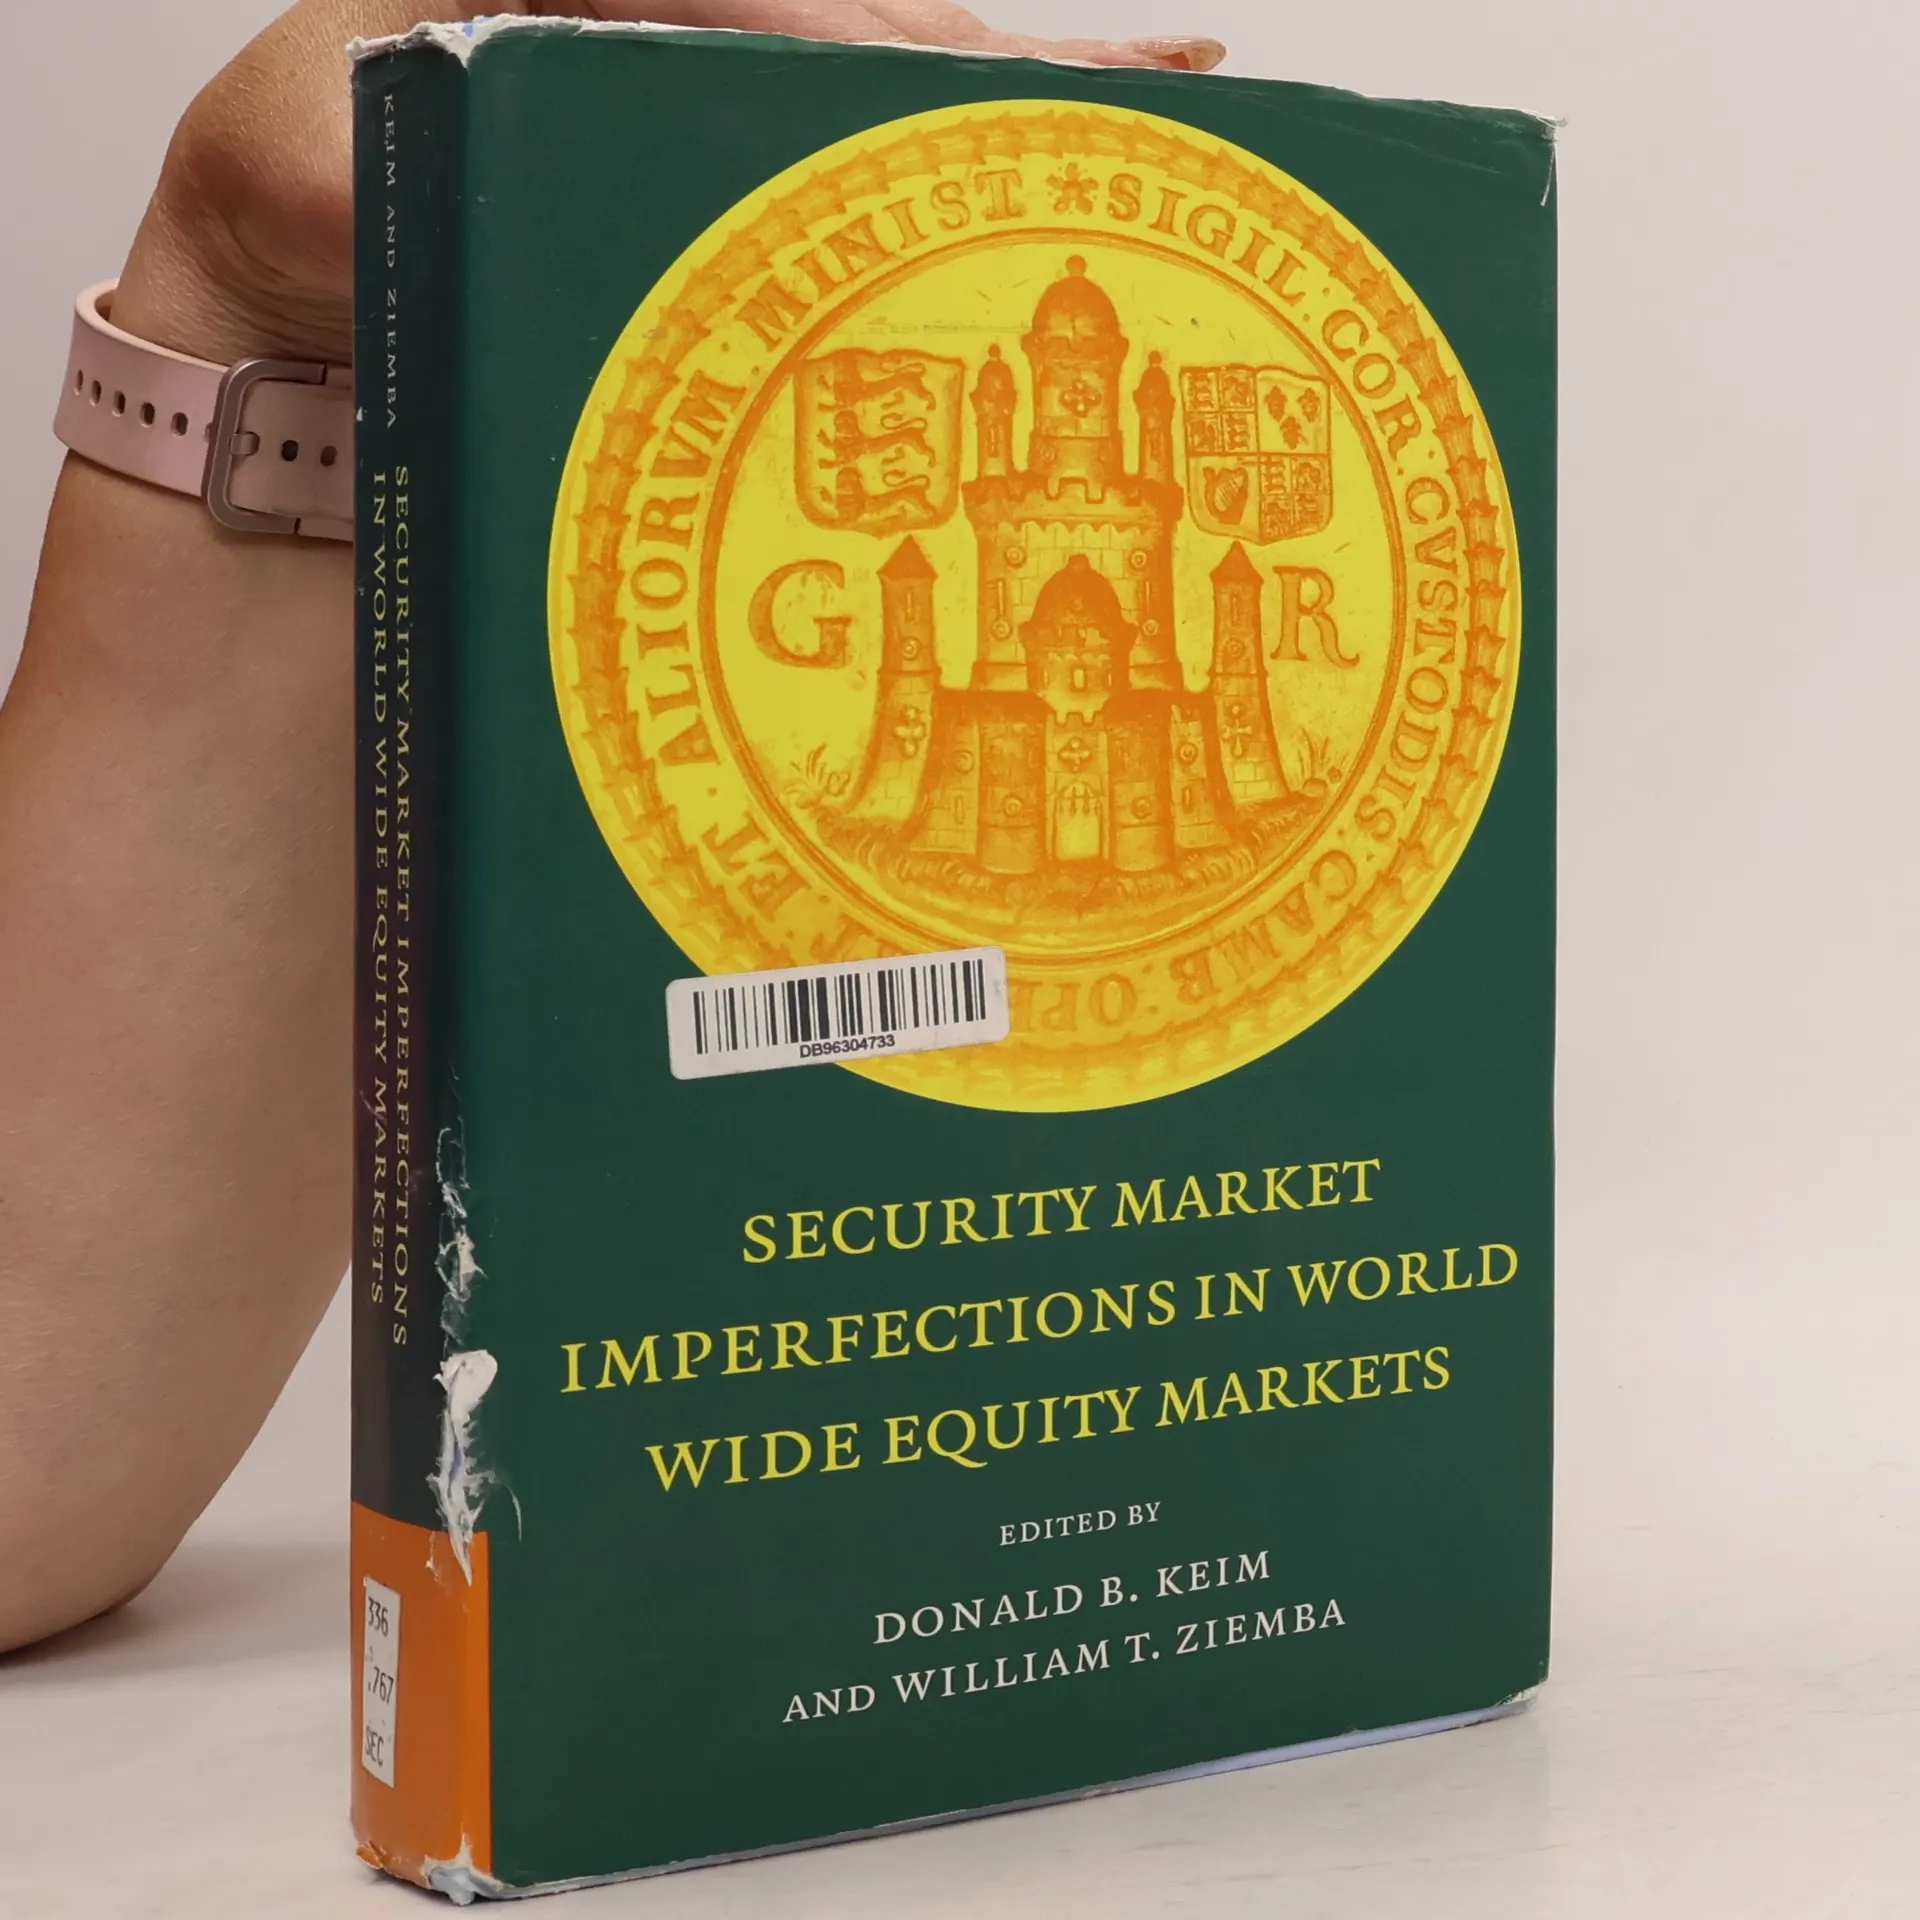
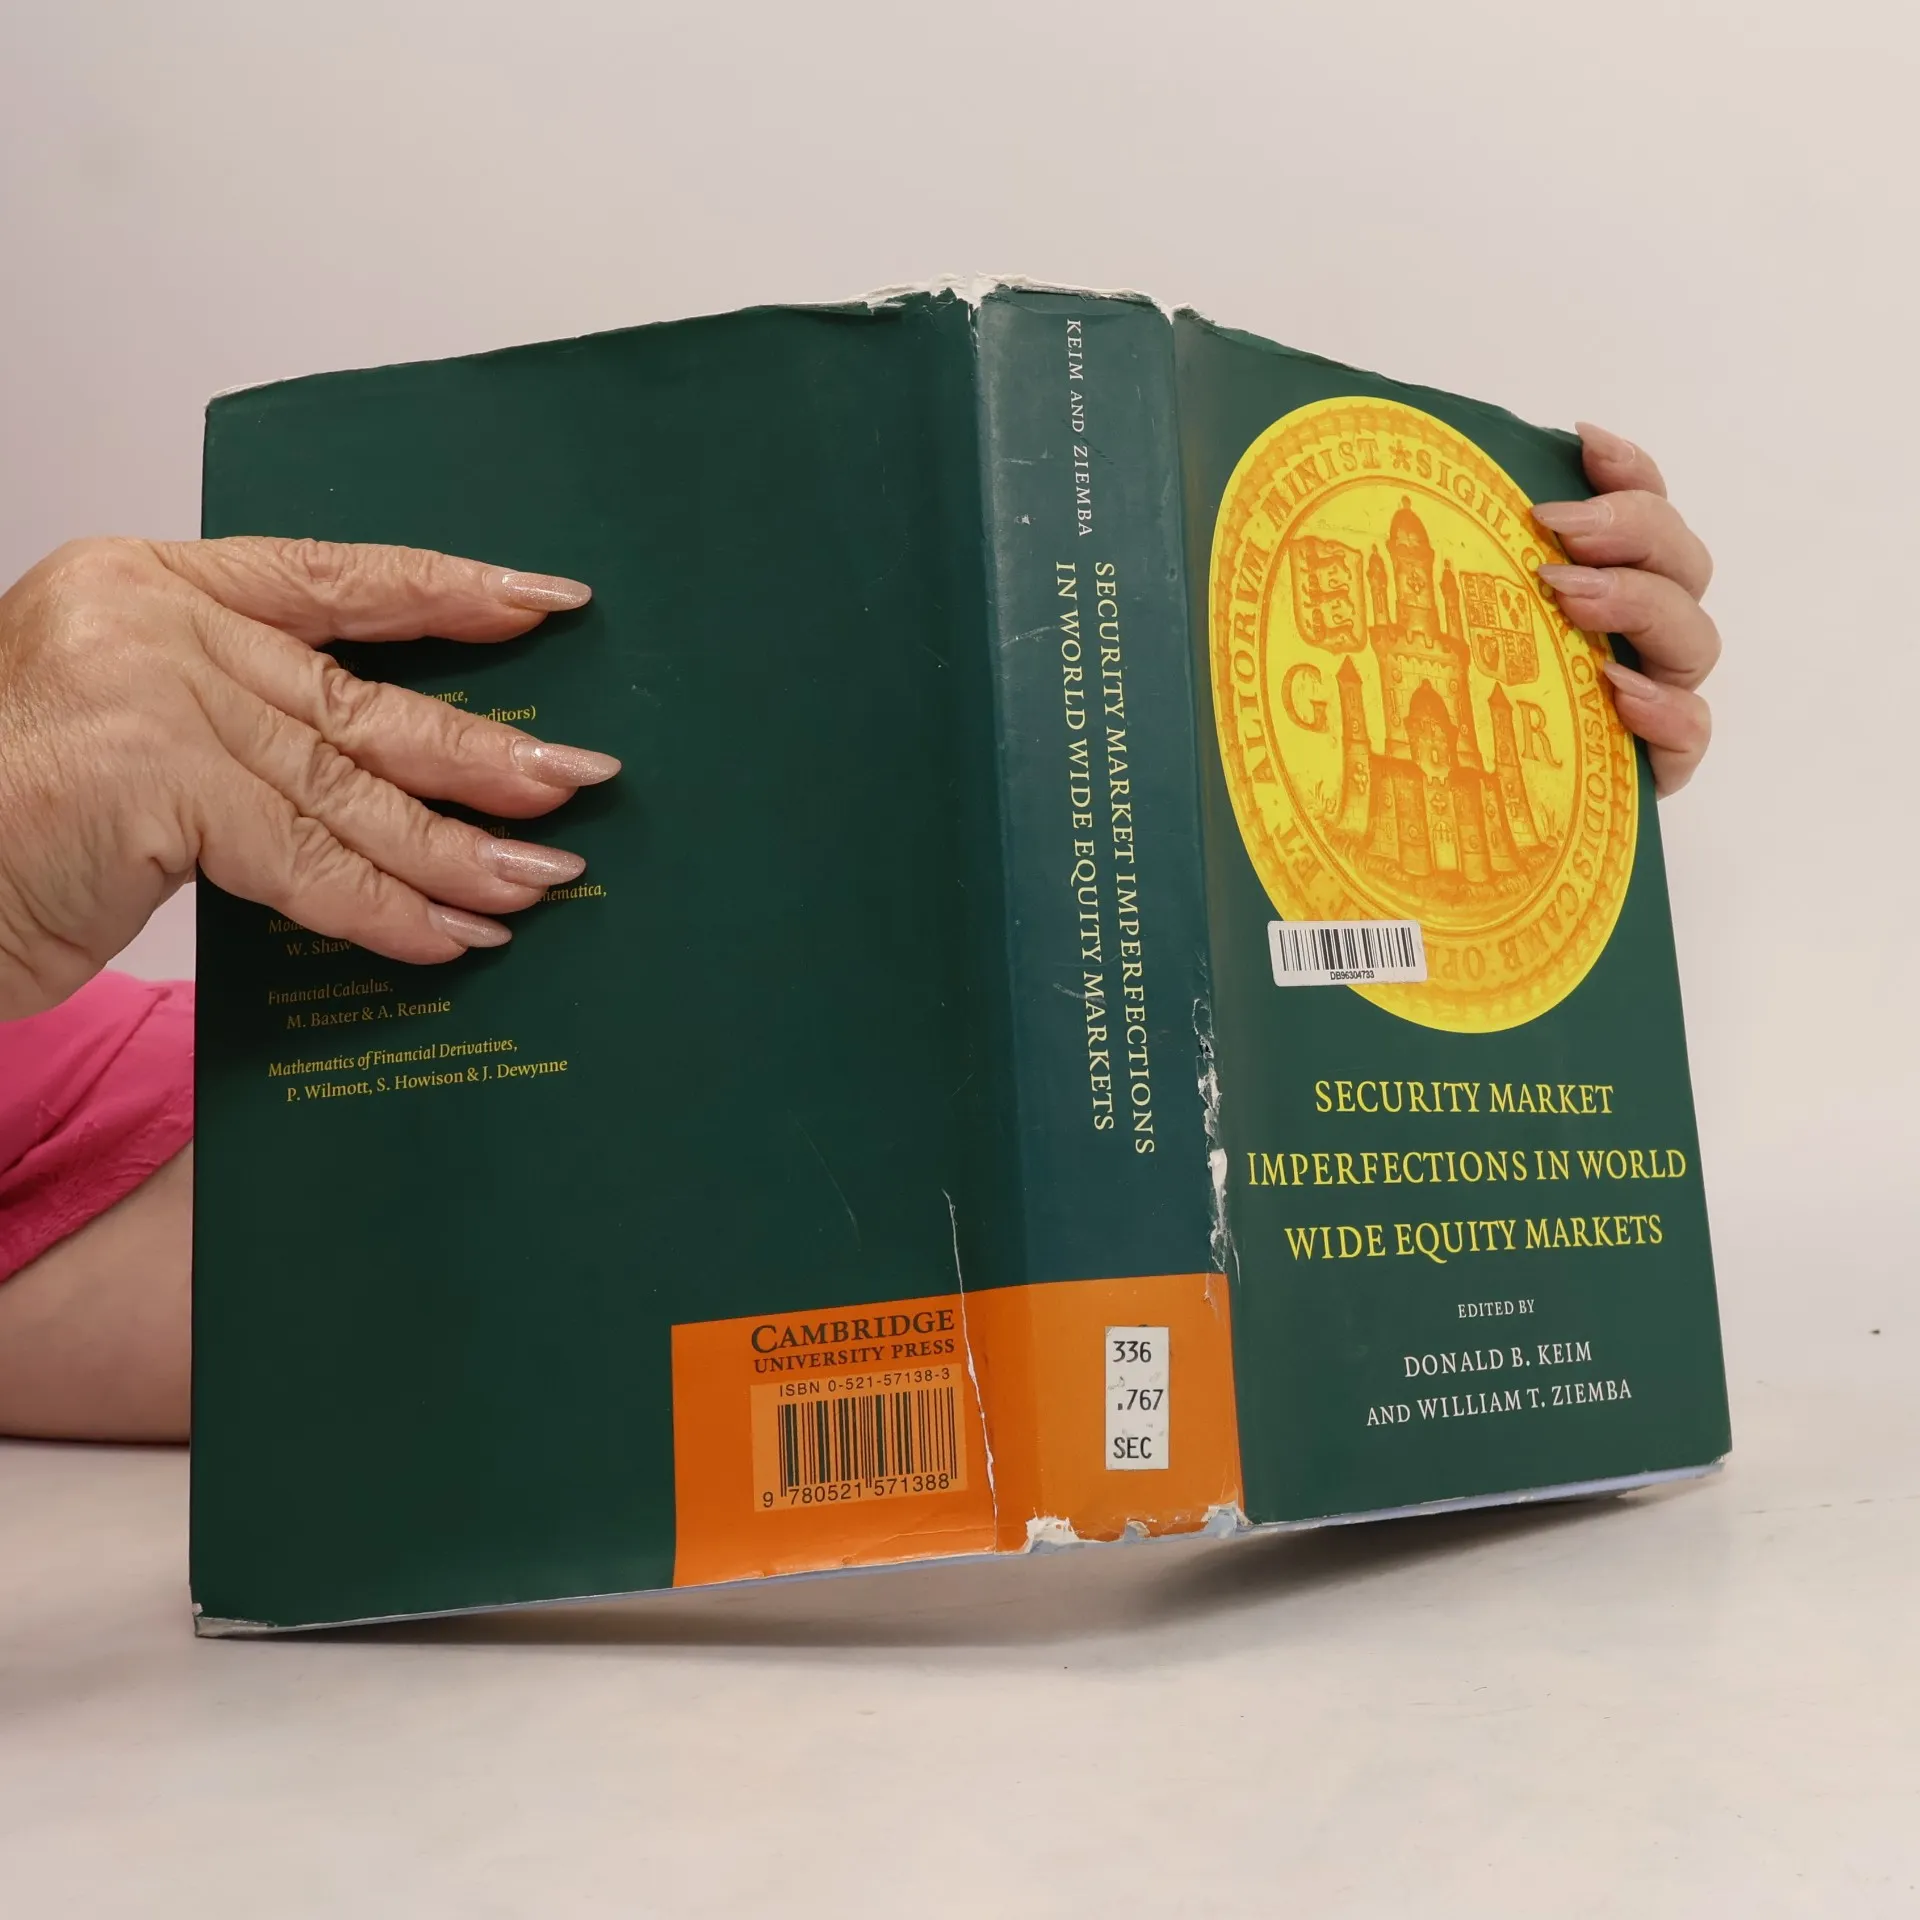
Security Market Imperfections in Worldwide Equity Markets, Donald B. Keim, William T Ziemba
- Język

- Rok wydania
- 2000
- Oprawa
- (twarda),
- Stan książki
- Uszkodzony
- Cena
- 81,39 zł
Metody płatności
Nikt jeszcze nie ocenił.
- Tytuł
- Security Market Imperfections in Worldwide Equity Markets
- Język
- angielski
- Autorzy
- Donald B. Keim, William T Ziemba
- Wydawca
- Cambridge University Press
- Rok wydania
- 2000
- Oprawa
- twarda
- Liczba stron
- 576
- ISBN10
- 0521571383
- ISBN13
- 9780521571388
- Seria
- Tagi
- Biznes
- Opis
- The study of security market imperfections, namely the predictability of equity stock returns, is one of the fundamental research areas in financial modelling. These anomalies, which are not consistent with existing theories, concern the relation between stock returns and variables, such as firm size and earnings-to-price ratios, and seasonal effects, such as January and turn-of-the-month. This book provides the most complete and current account of work in the area. Leading academics and investment researchers have combined to produce a comprehensive coverage of the subject, including both cross-sectional and time series analyses, as well as discussing the measurement of risk and prediction models that have been used by institutional investors. The studies cover many worldwide markets including the US, Japan, Asia, and Europe. The book will be invaluable for courses in financial engineering, investment and portfolio management, and as a reference for investment professionals seeking an up-to-date source on return predictability.