

Parametry
- 239 stron
- 9 godzin czytania
Więcej o książce
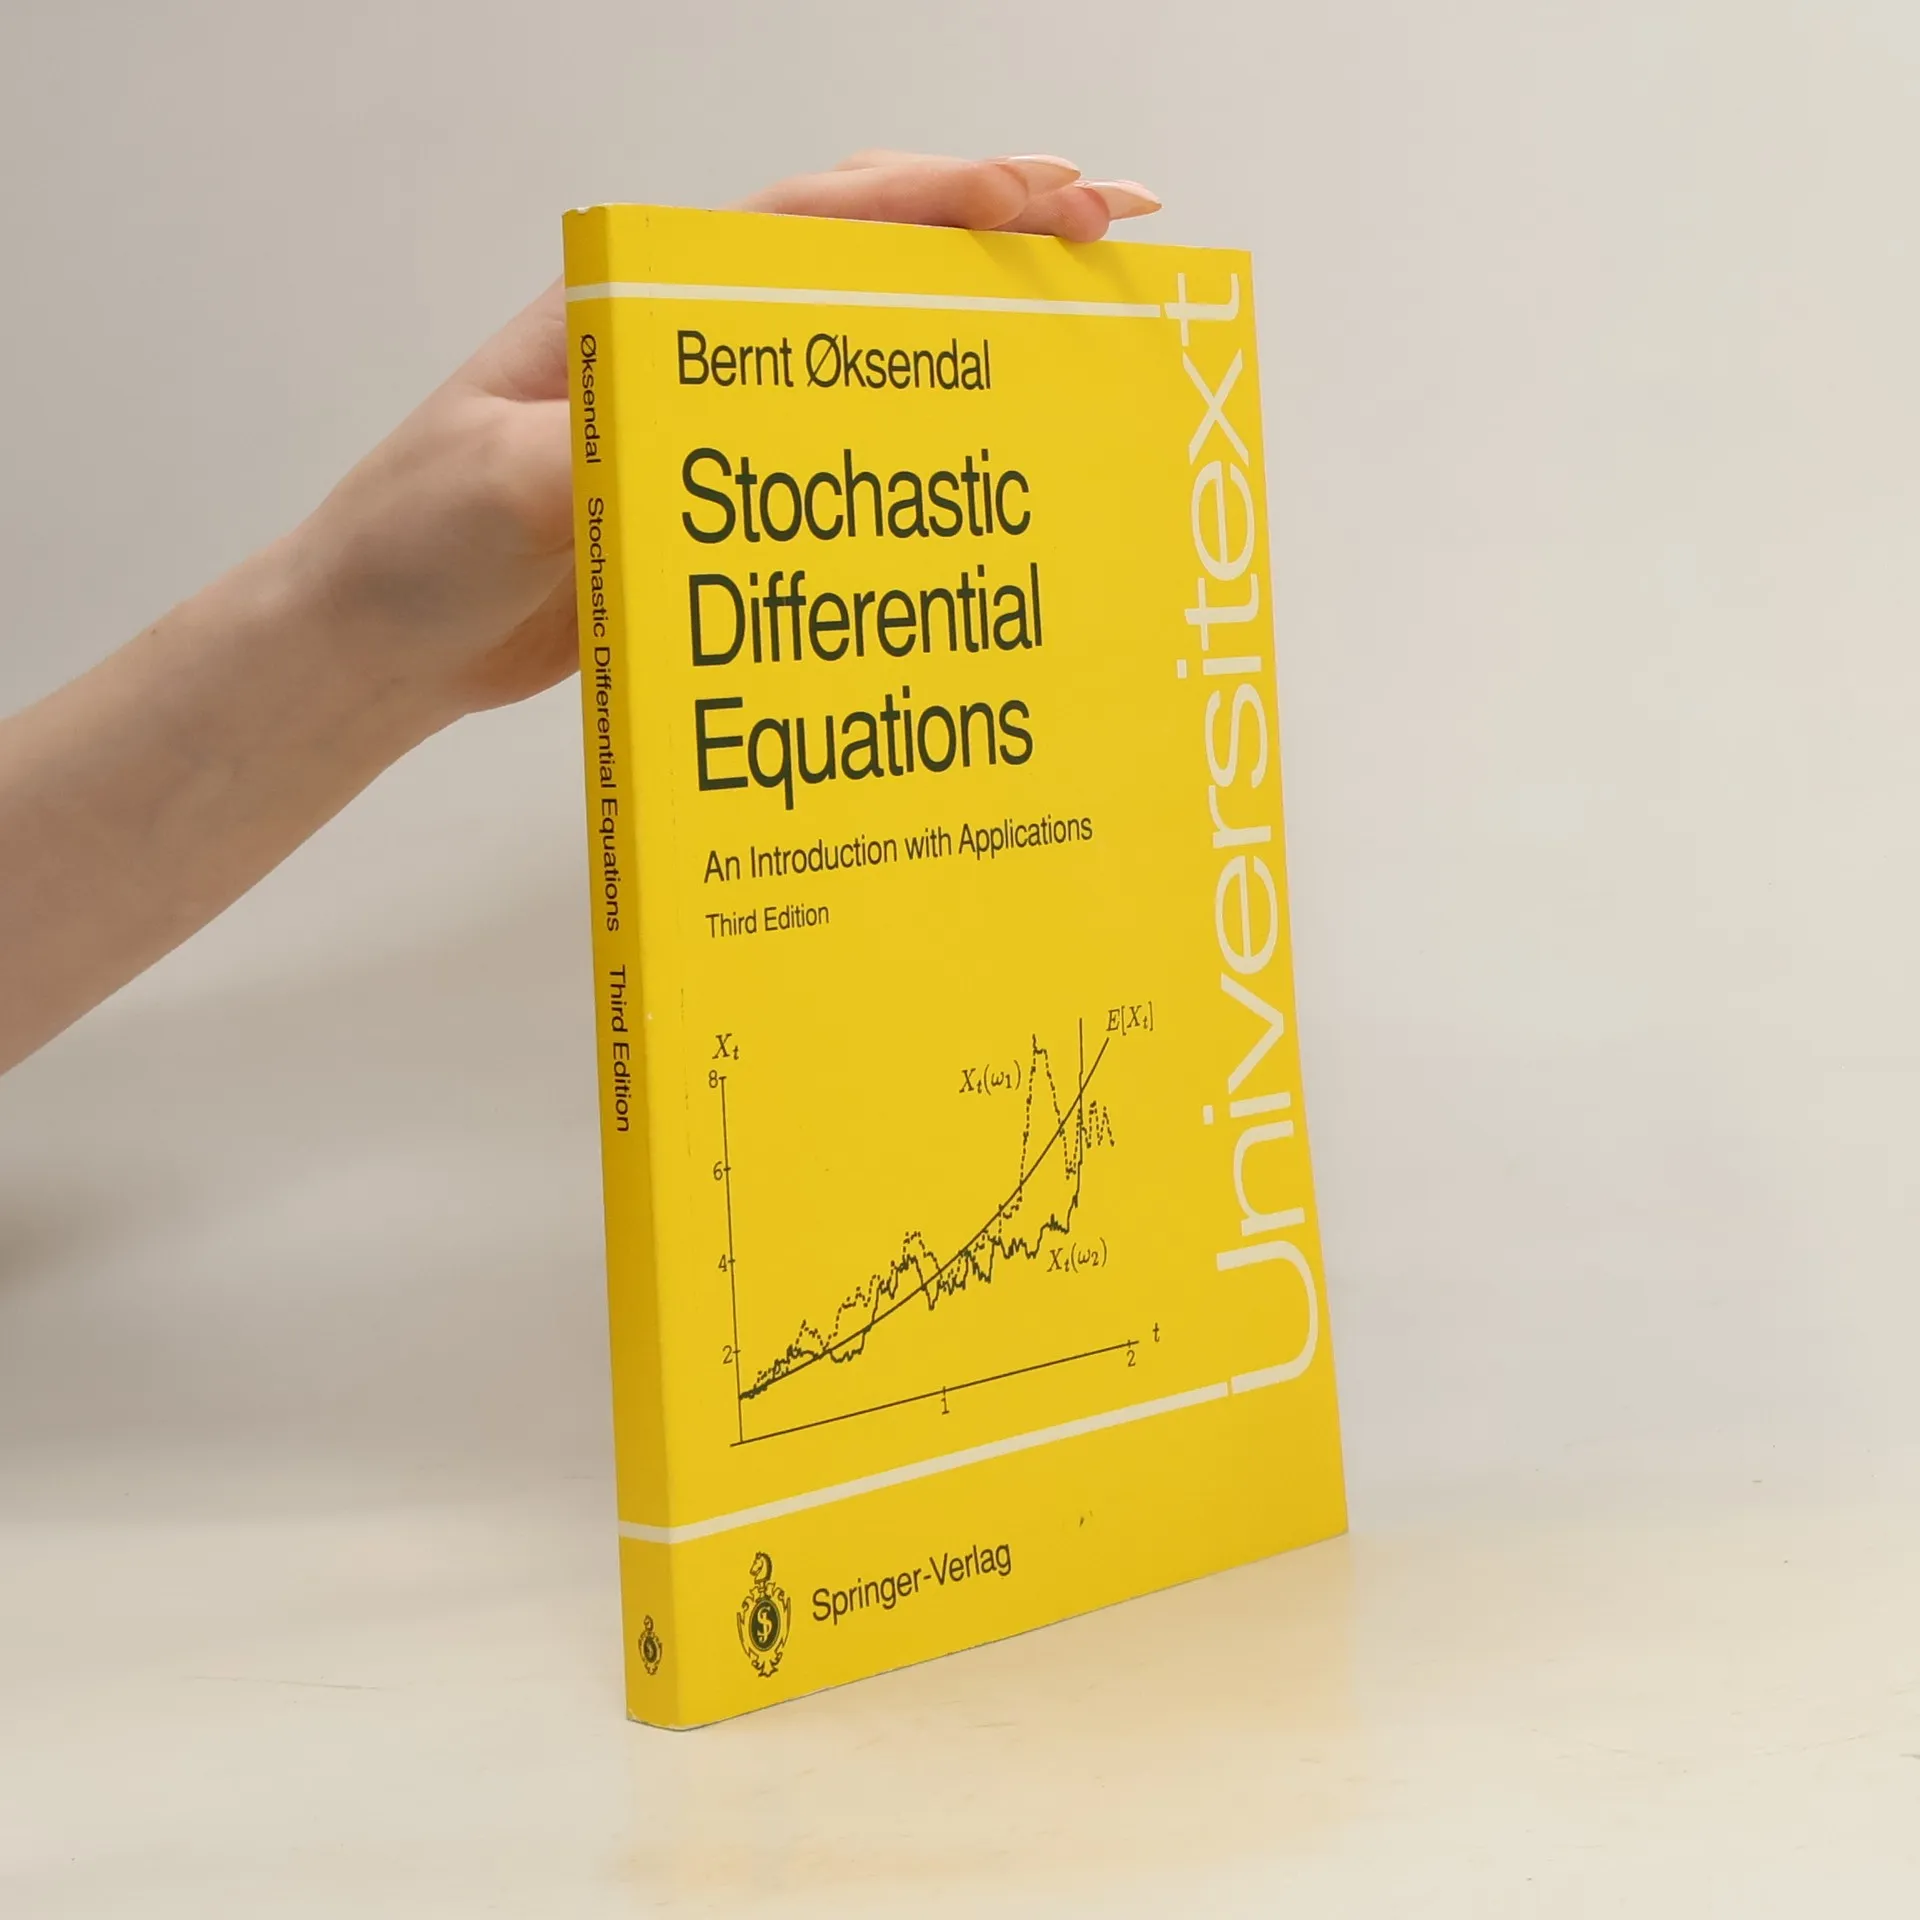
This book gives an introduction to the basic theory of stochastic calculus and its applications. Examples are provided throughout the text to motivate and illustrate the theory and show its importance for many applications in economics, biology, and physics. The basic idea of the presentation is to start from some fundamental results (without proofs) of the easier cases and develop the theory from there, concentrating on the proofs of the easier cases (which are often sufficiently general for many purposes) to quickly reach the parts of the theory that are most important for the applications. An extra chapter on applications to mathematical finance is included.
Zakup książki
Stochastic Differential Equations, Bernt Oksendal
- Język

- Rok wydania
- 1992
- Oprawa
- (miękka)
Metody płatności
Brakuje nam tutaj Twojej recenzji.
- Tytuł
- Stochastic Differential Equations
- Podtytuł
- An Introduction with Applications
- Język
- angielski
- Autorzy
- Bernt Oksendal
- Rok wydania
- 1992
- Oprawa
- miękka
- Liczba stron
- 239
- ISBN10
- 3540533354
- ISBN13
- 9783540533351
- Seria
- Tagi
- Podręczniki, Biznes, Nauki przyrodnicze, Nauka, Podręczniki matematyki, Finanse, Podręczniki fizyki
- Ocena
- 4 z 5
- Opis
- This book gives an introduction to the basic theory of stochastic calculus and its applications. Examples are provided throughout the text to motivate and illustrate the theory and show its importance for many applications in economics, biology, and physics. The basic idea of the presentation is to start from some fundamental results (without proofs) of the easier cases and develop the theory from there, concentrating on the proofs of the easier cases (which are often sufficiently general for many purposes) to quickly reach the parts of the theory that are most important for the applications. An extra chapter on applications to mathematical finance is included.