



Więcej o książce
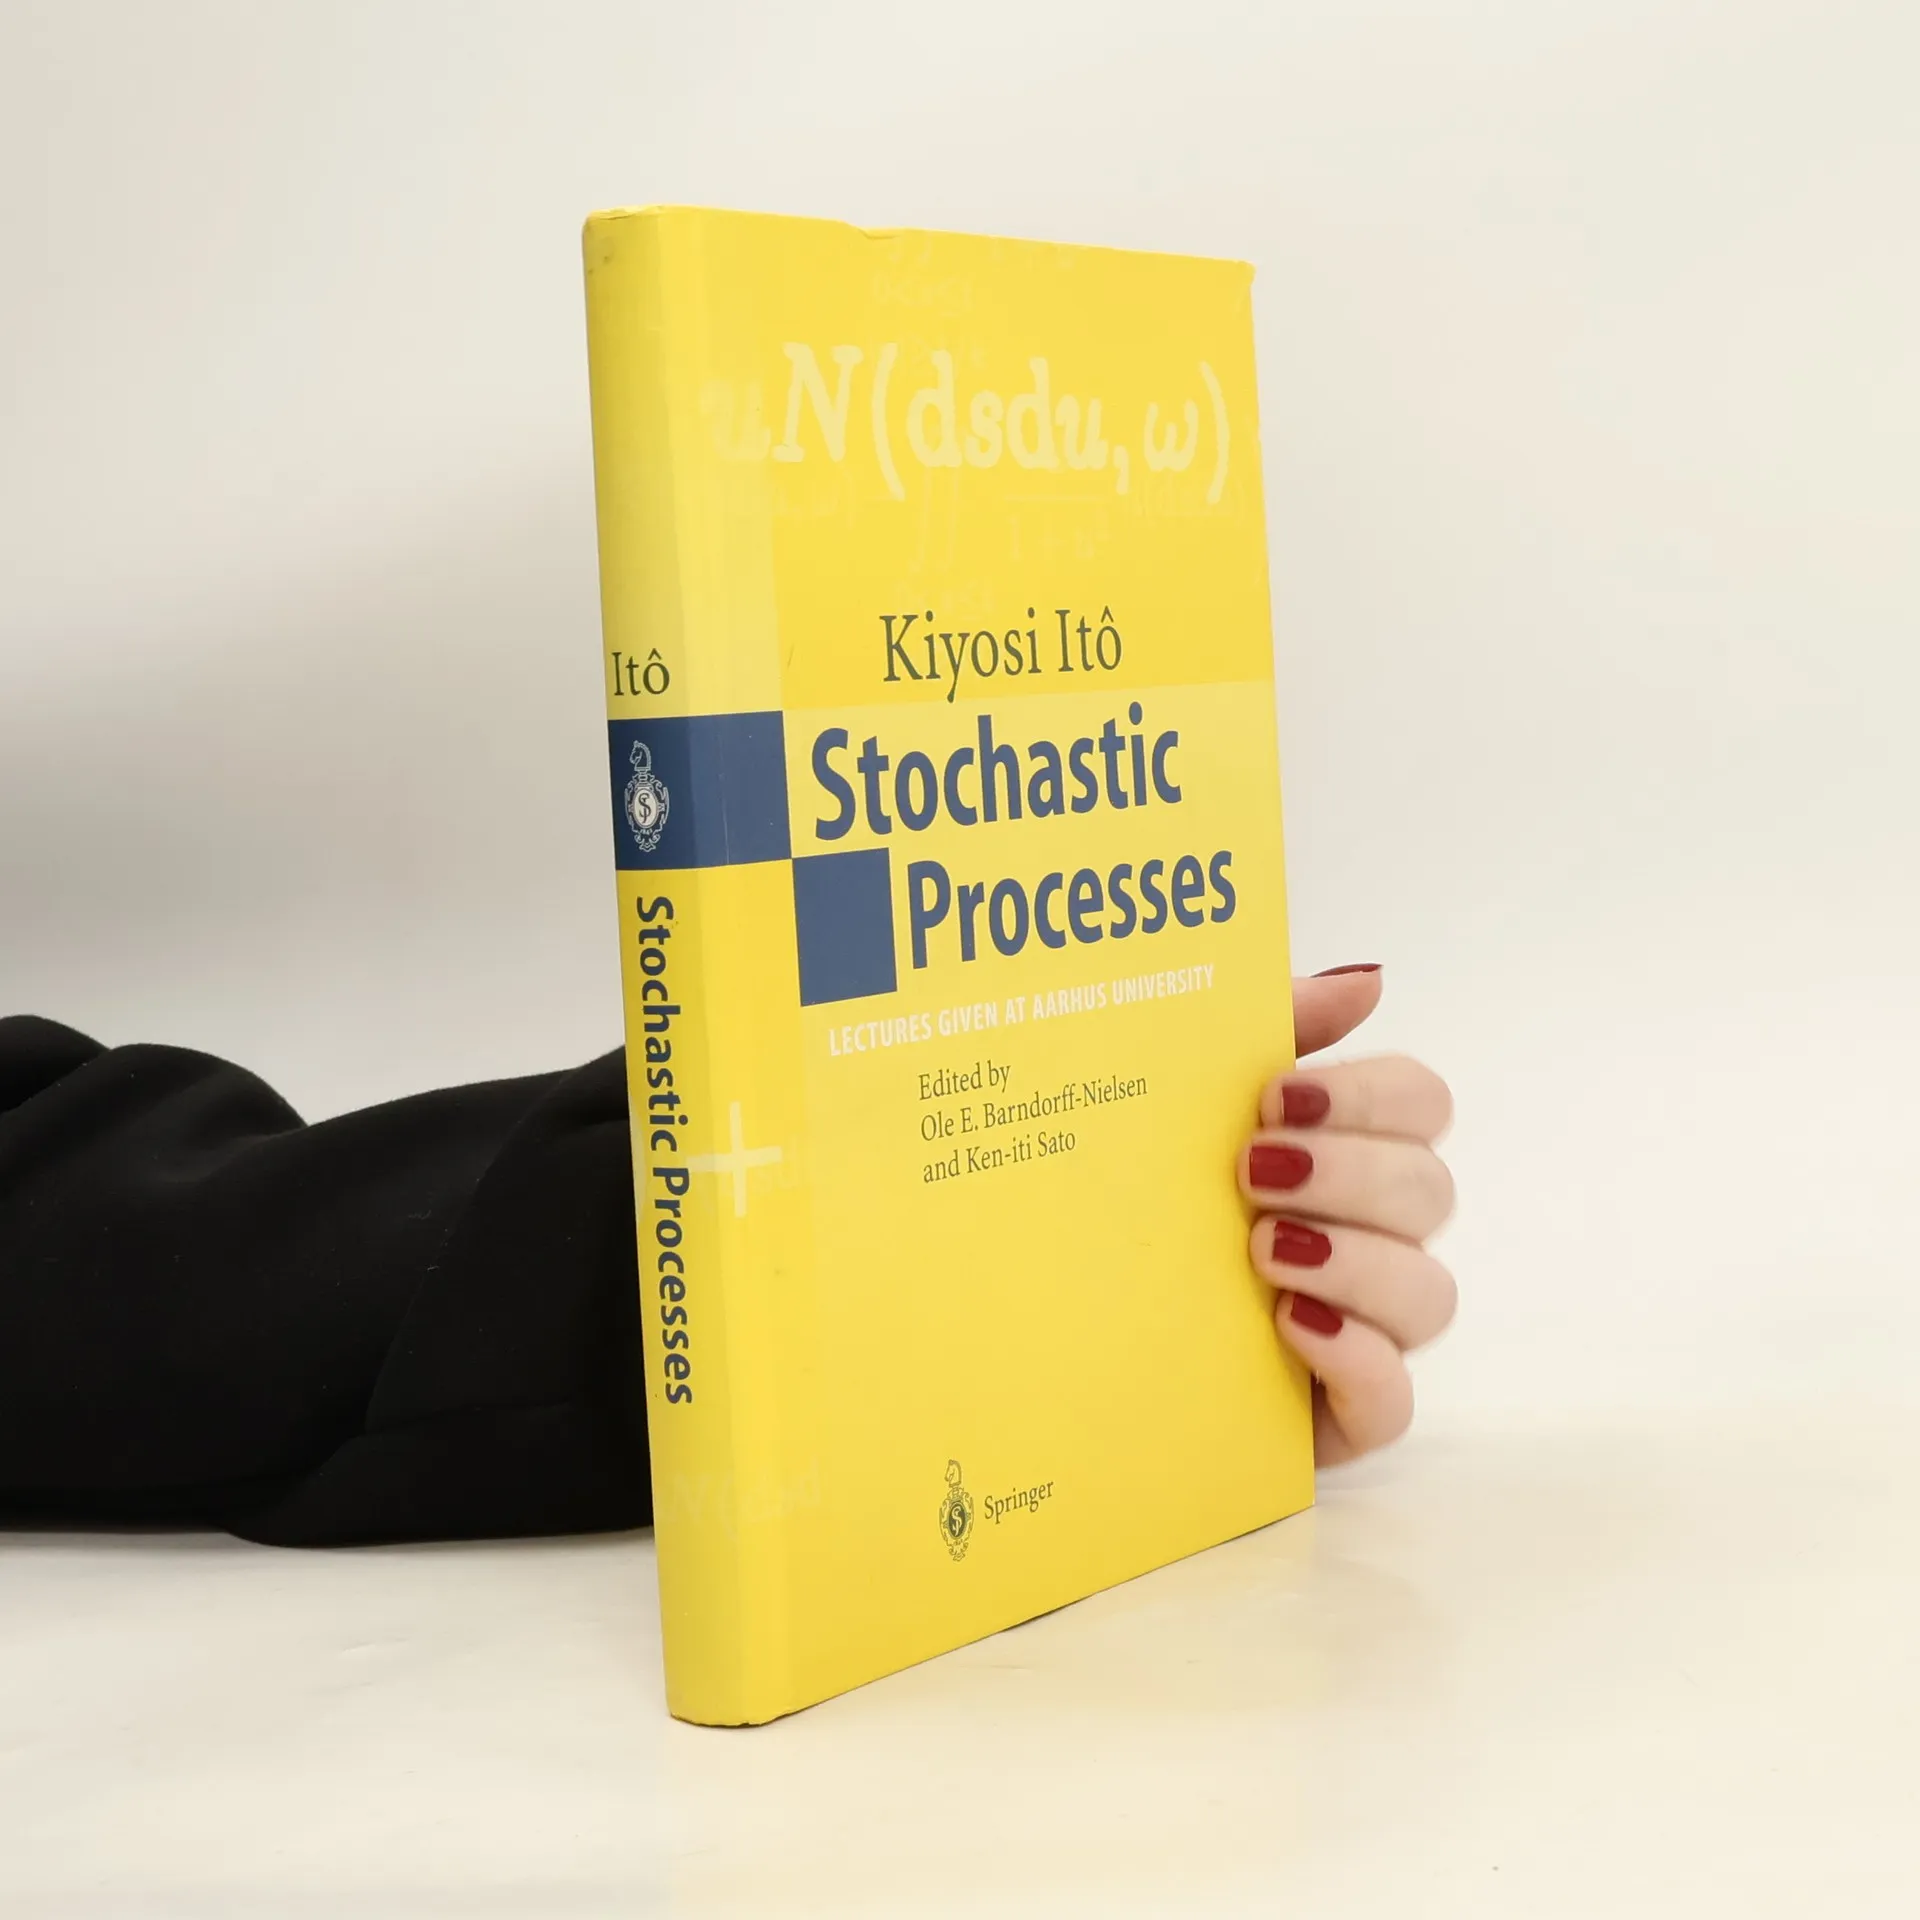
The volume by K. Itö, published in August 1969 as part of the Lecture Notes Series from the Mathematics Institute, Aarhus University, is based on lectures from the academic year 1968-1969. This 3.5 cm thick, mimeographed text has been out of print for years, serving as a valuable introduction to additive processes and Markov processes for those fortunate enough to obtain one of the few copies. It features a clear exposition of the Lévy-Itö decomposition of additive processes. Encouraged by Professor Itö, the volume has been edited into its current form, with amendments and additional footnotes, along with an index. Chapter 0 covers preliminaries, discussing centralized sums of independent random variables and utilizing dispersion as a key tool. It also presents Lévy's characteristic functions of infinitely divisible distributions and essential properties of martingales. Chapter 1 focuses on the analysis of additive processes, detailing a fundamental theorem that describes the decomposition of sample functions, known as the Lévy-Itö decomposition. This is explored thoroughly, without assuming continuity in time, closely aligning with Itö's original 1942 paper that articulated Lévy's intuitive understanding of path behavior.
Zakup książki
Stochastic Processes, Kiyoshi Ito, Ole E. Barndorff-Nielsen, Ken-iti Sato
- Język

- Rok wydania
- 2004
- Oprawa
- (twarda)
Metody płatności
Nikt jeszcze nie ocenił.
- Tytuł
- Stochastic Processes
- Podtytuł
- Lectures Given at Aarhus University
- Język
- angielski
- Wydawca
- Springer
- Rok wydania
- 2004
- Oprawa
- twarda
- Liczba stron
- 234
- ISBN10
- 3540204822
- ISBN13
- 9783540204824
- Seria
- Opis
- The volume by K. Itö, published in August 1969 as part of the Lecture Notes Series from the Mathematics Institute, Aarhus University, is based on lectures from the academic year 1968-1969. This 3.5 cm thick, mimeographed text has been out of print for years, serving as a valuable introduction to additive processes and Markov processes for those fortunate enough to obtain one of the few copies. It features a clear exposition of the Lévy-Itö decomposition of additive processes. Encouraged by Professor Itö, the volume has been edited into its current form, with amendments and additional footnotes, along with an index. Chapter 0 covers preliminaries, discussing centralized sums of independent random variables and utilizing dispersion as a key tool. It also presents Lévy's characteristic functions of infinitely divisible distributions and essential properties of martingales. Chapter 1 focuses on the analysis of additive processes, detailing a fundamental theorem that describes the decomposition of sample functions, known as the Lévy-Itö decomposition. This is explored thoroughly, without assuming continuity in time, closely aligning with Itö's original 1942 paper that articulated Lévy's intuitive understanding of path behavior.