

Kupujesz dokładnie tę książkę,która jest na zdjęciu.
Parametry
- 392 strony
- 14 godzin czytania
Więcej o książce
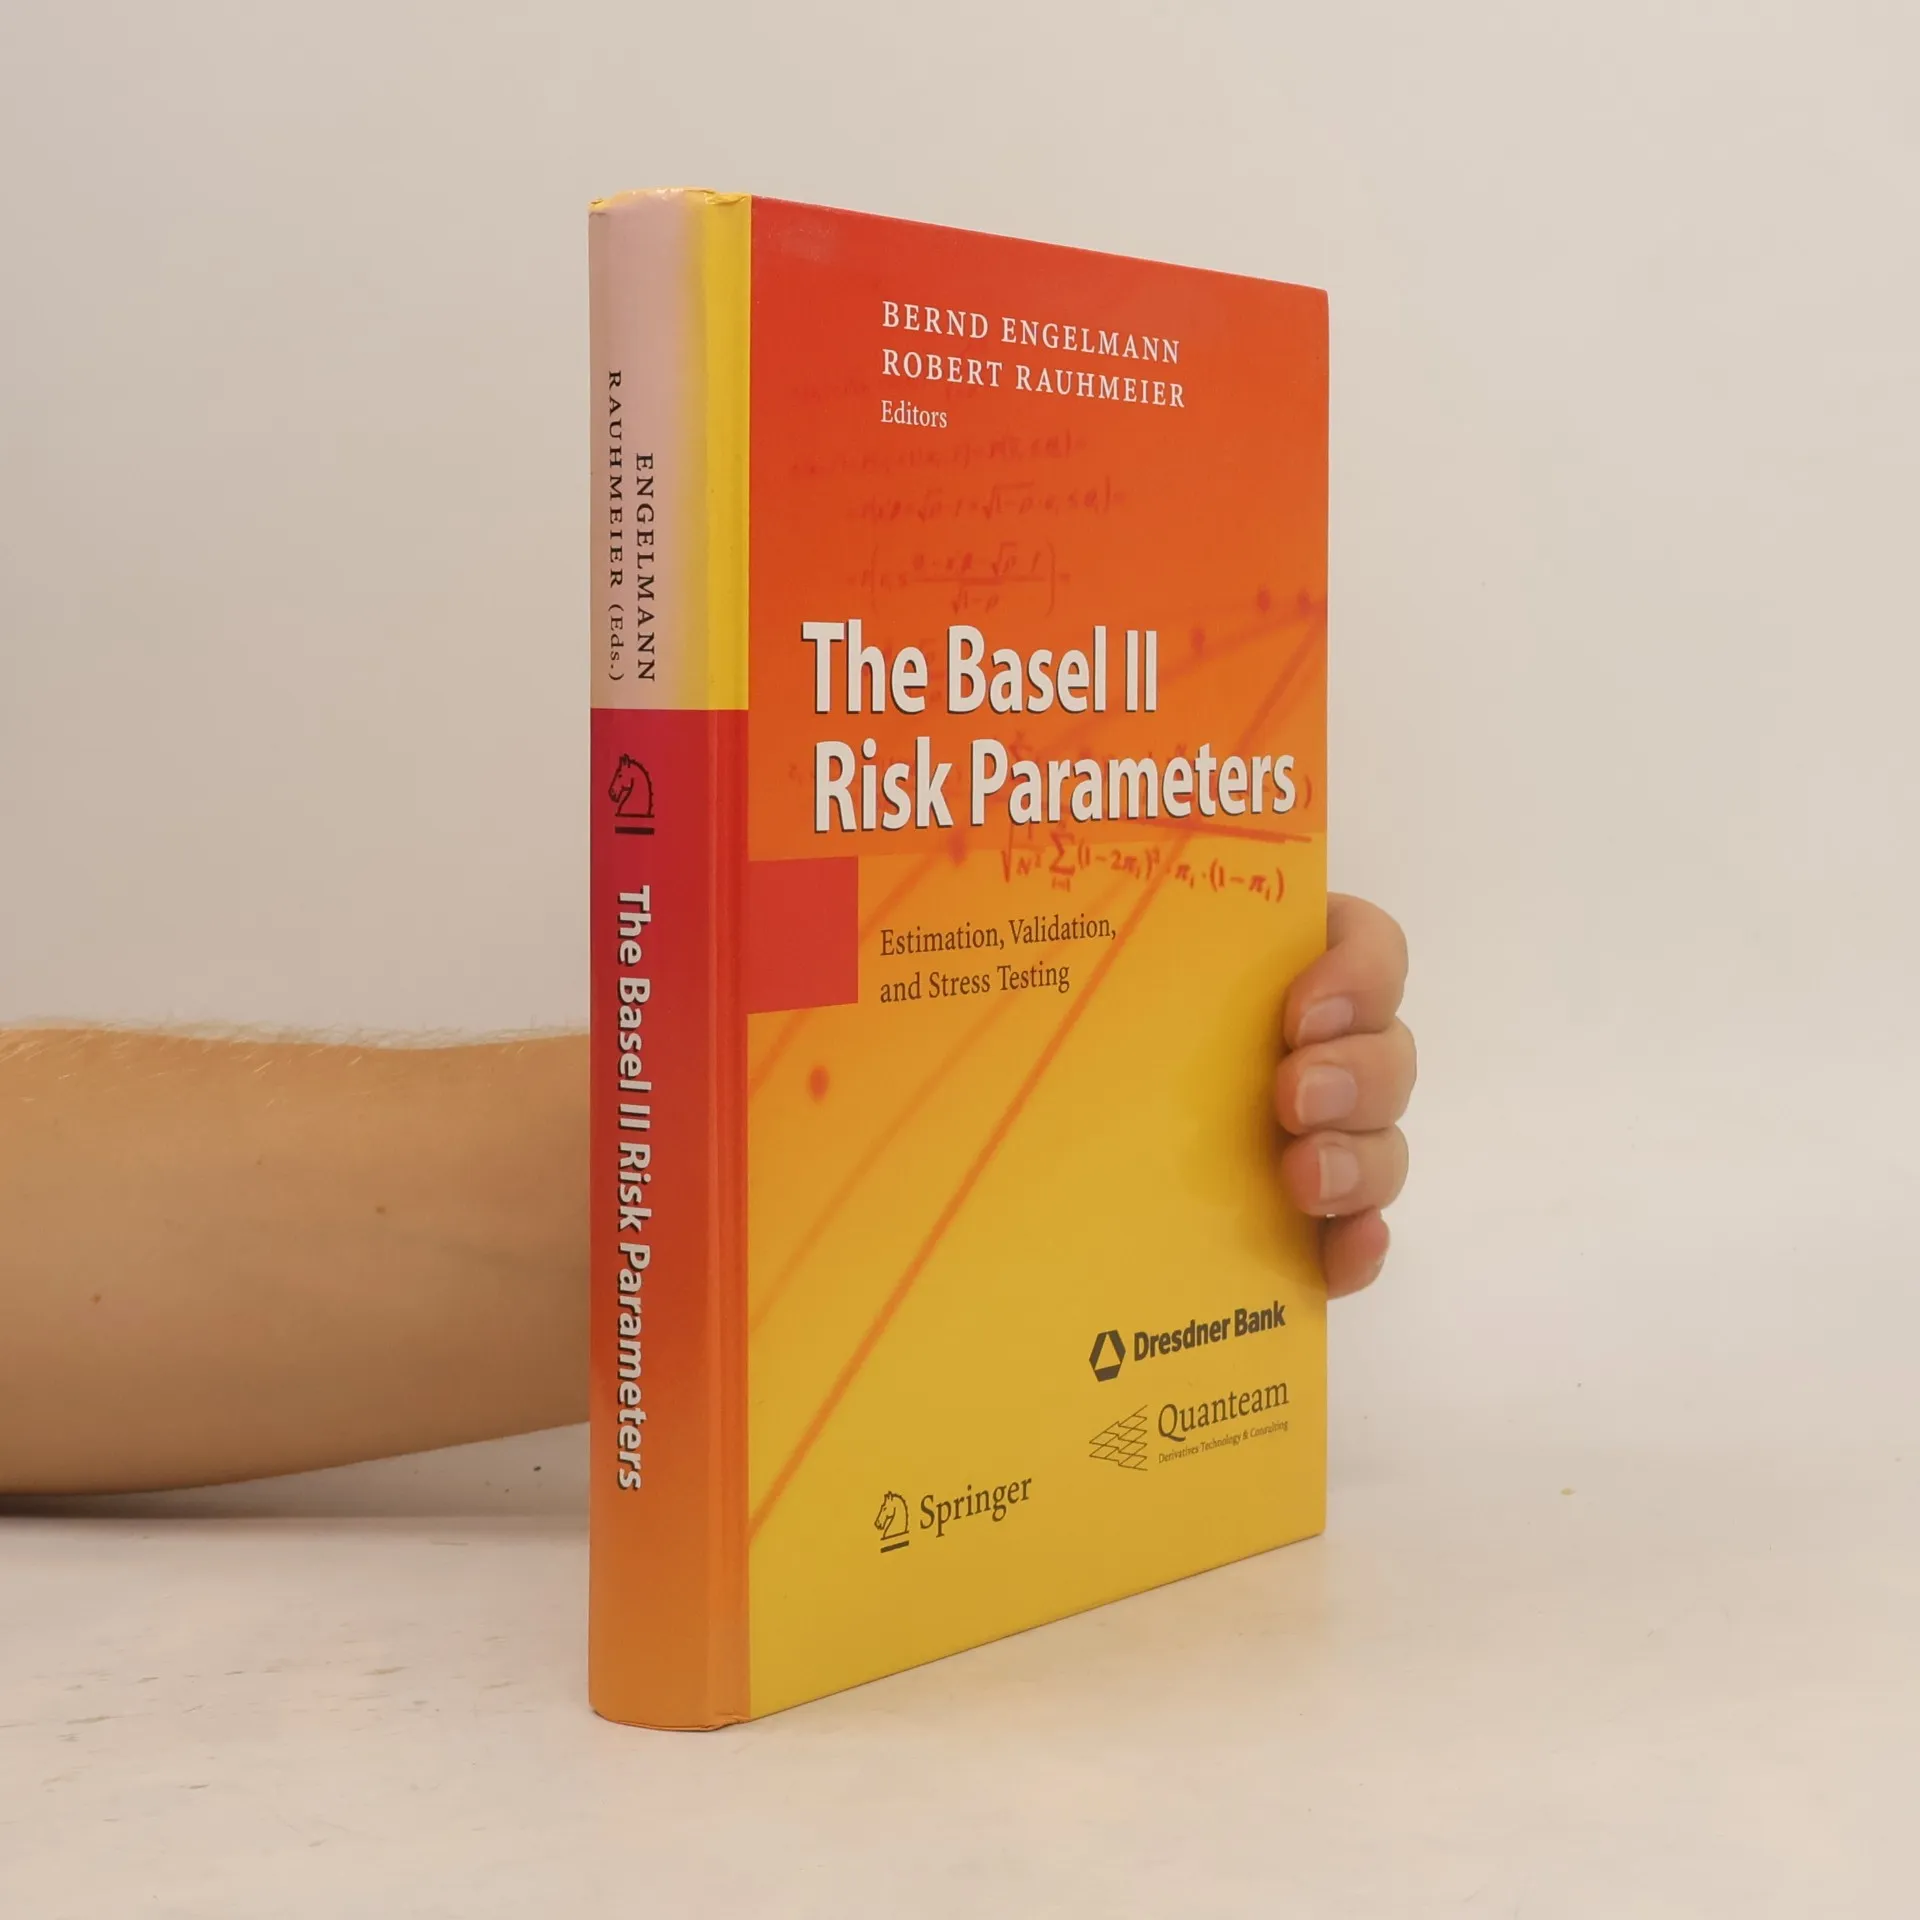
A critical problem in the practice of banking risk assessment is the estimation and validation of the Basel II risk parameters PD (default probability), LGD (loss given default), and EAD (exposure at default). This book presents the state-of-the-art in designing and validating rating systems and default probability estimations, and outlines techniques to estimate LGD and EAD. Also included is a chapter on stress testing of the Basel II risk parameters.
Zakup książki
The Basel II Risk Parameters, Berndt Engelmann, Robert Rauhmeier
- Język

- Rok wydania
- 2006
- Oprawa
- (twarda),
- Stan książki
- Dobry
- Cena
- 176,32 zł
Metody płatności
Nikt jeszcze nie ocenił.
- Tytuł
- The Basel II Risk Parameters
- Podtytuł
- Estimation, Validation, and Stress Testing
- Język
- angielski
- Autorzy
- Berndt Engelmann, Robert Rauhmeier
- Wydawca
- Springer
- Rok wydania
- 2006
- Oprawa
- twarda
- Liczba stron
- 392
- ISBN10
- 3540330852
- ISBN13
- 9783540330851
- Seria
- Kategorie
- Tagi
- Biznes, Finanse, Zachodnia Europa, Rozwój, Bankowość, Modelarstwo
- Opis
- A critical problem in the practice of banking risk assessment is the estimation and validation of the Basel II risk parameters PD (default probability), LGD (loss given default), and EAD (exposure at default). This book presents the state-of-the-art in designing and validating rating systems and default probability estimations, and outlines techniques to estimate LGD and EAD. Also included is a chapter on stress testing of the Basel II risk parameters.