

Wyprzedane, ale poszukiwane!
Więcej o książce
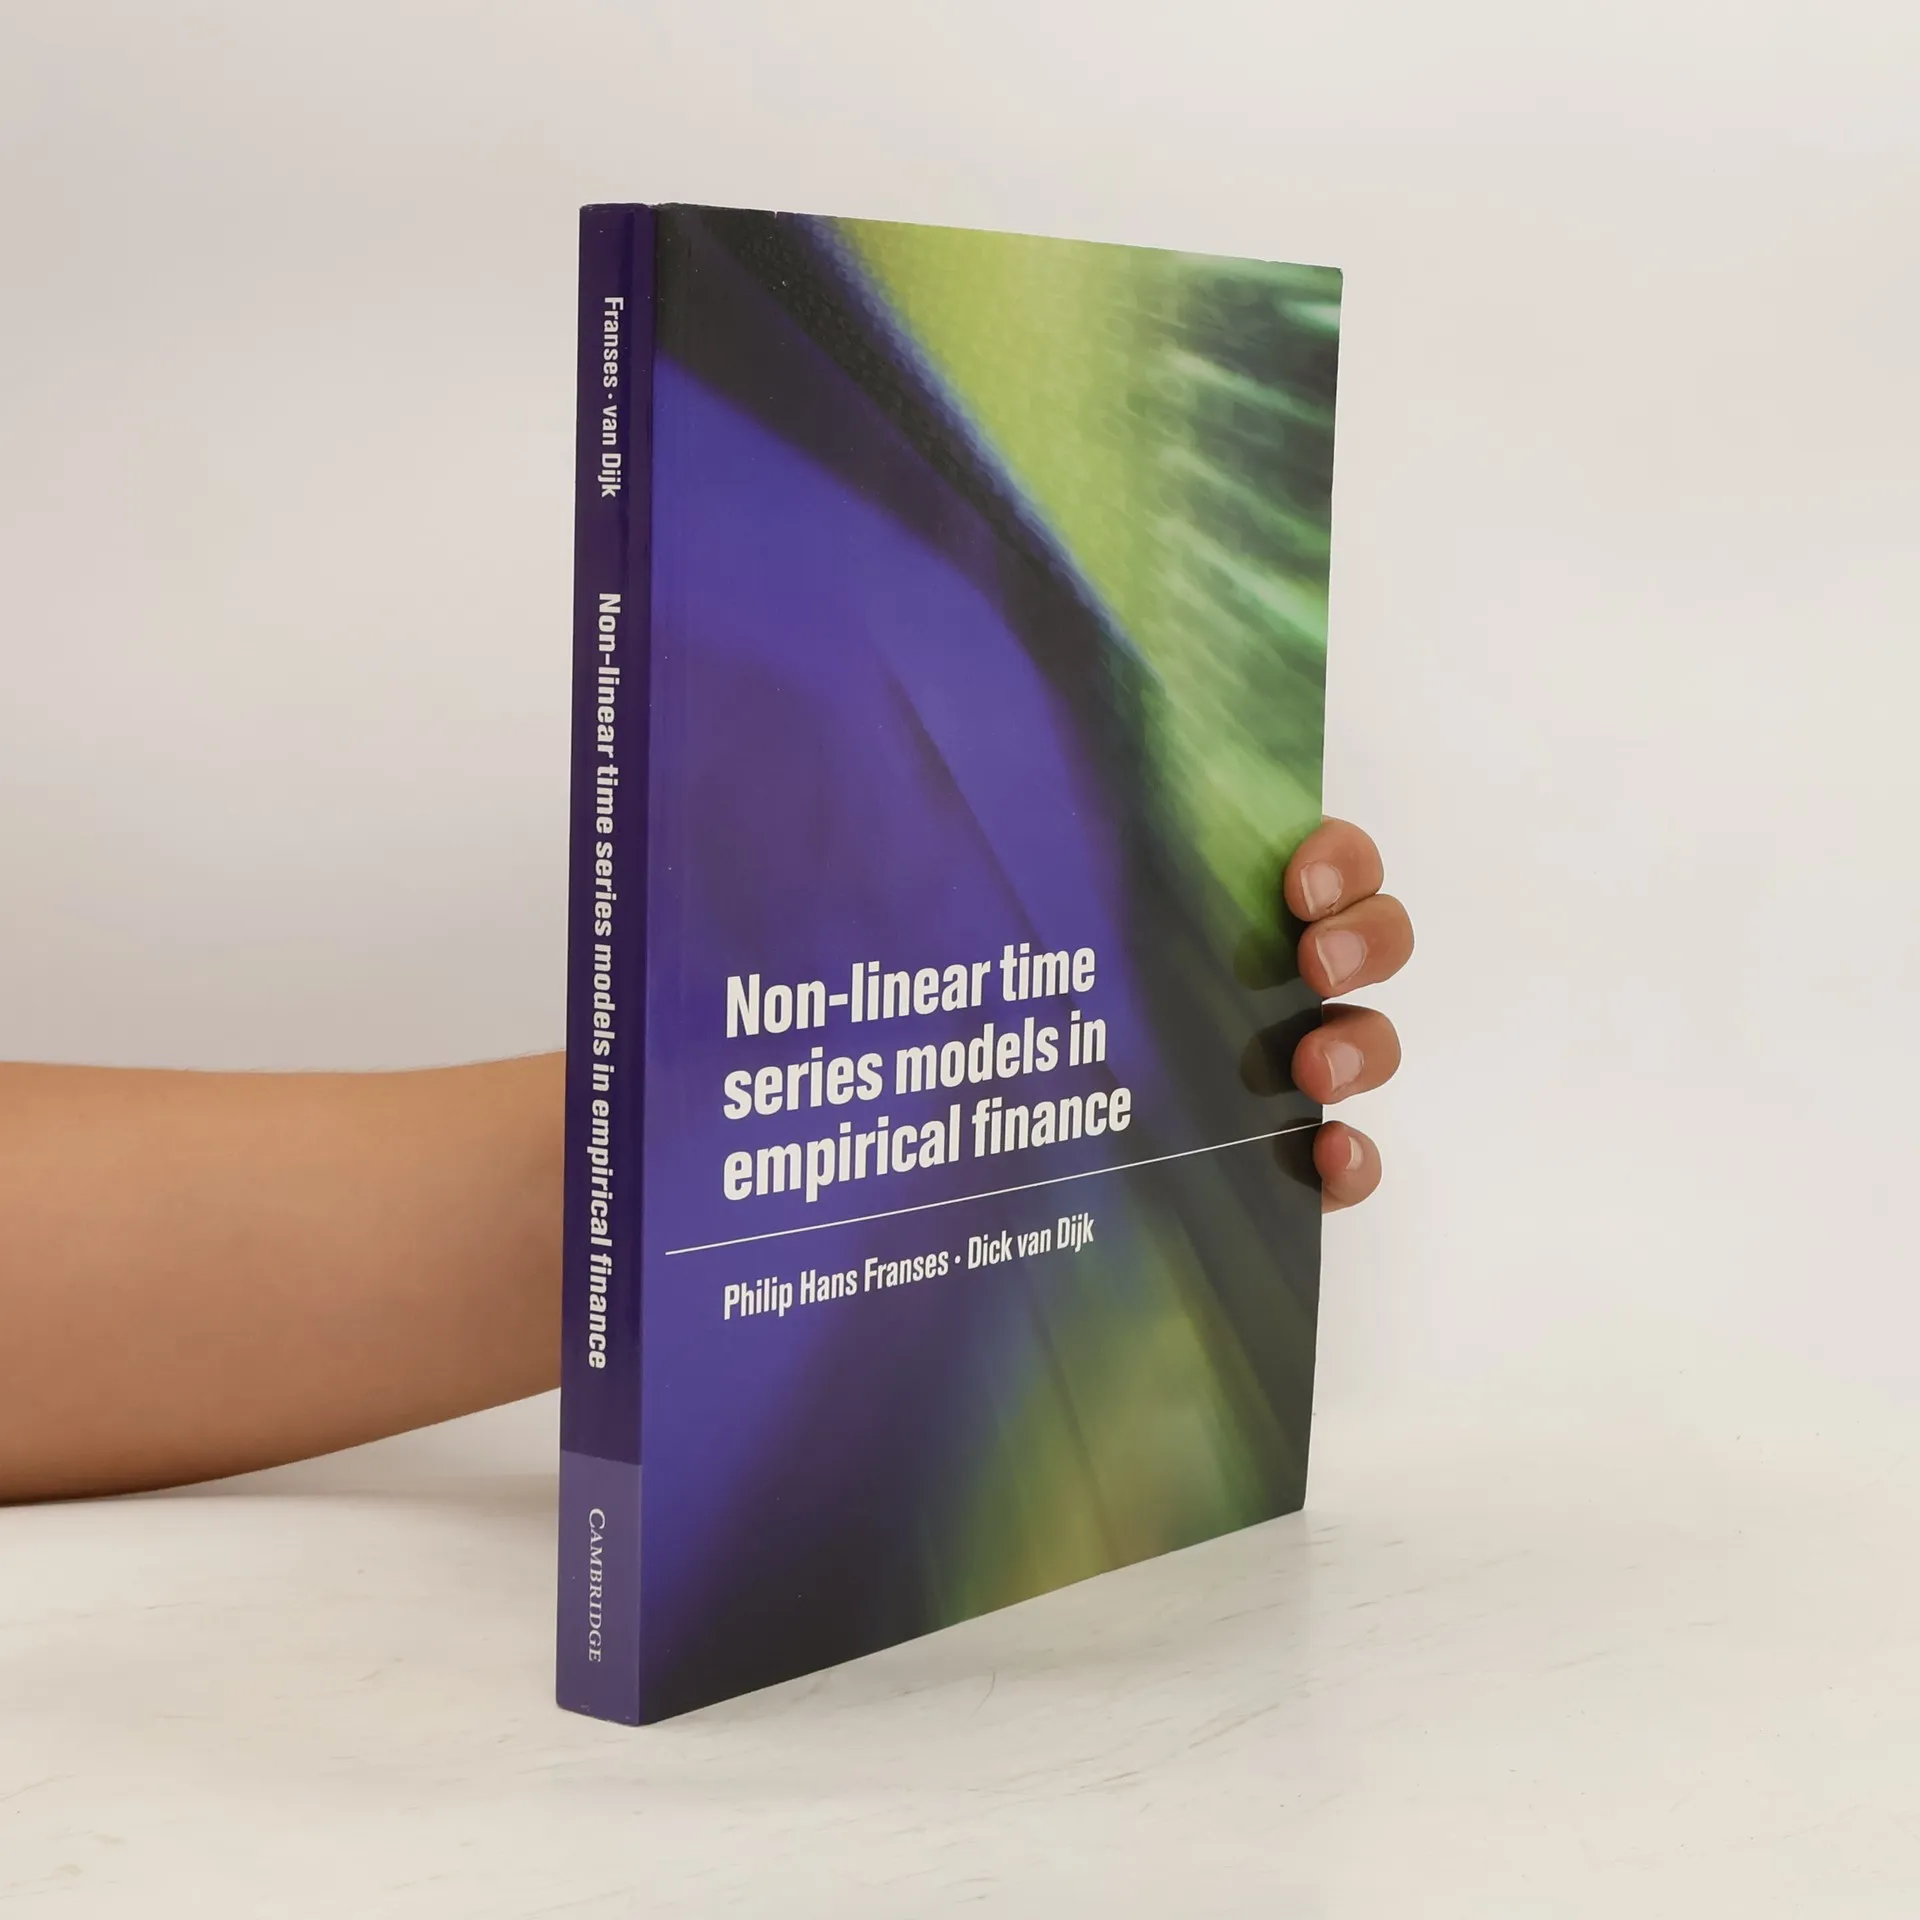
This is the most up-to-date and accessible guide to one of the fastest growing areas in financial analysis by two of the most accomplished young econometricians in Europe. This classroom-tested advanced undergraduate and graduate textbook provides an in-depth treatment of recently developed nonlinear models, including regime-switching and artificial neural networks, and applies them to describing and forecasting financial asset returns and volatility. It uses a wide range of financial data, drawn from sources including the markets of Tokyo, London and Frankfurt.
Zakup książki
Non-Linear Time Series Models in Empirical Finance, Philip Hans Franses, Dick van Dijk
- Język

- Rok wydania
- 2000
- Oprawa
- (zintegrowana)
Jak tylko się pojawi, wyślemy Ci wiadomość e-mail.
Metody płatności
Brakuje nam tutaj Twojej recenzji.
- Tytuł
- Non-Linear Time Series Models in Empirical Finance
- Język
- angielski
- Autorzy
- Philip Hans Franses, Dick van Dijk
- Wydawca
- Cambridge University Press
- Rok wydania
- 2000
- Oprawa
- zintegrowana
- Liczba stron
- 296
- ISBN10
- 0521779650
- ISBN13
- 9780521779654
- Seria
- Tagi
- Biznes
- Ocena
- 3,65 z 5
- Opis
- This is the most up-to-date and accessible guide to one of the fastest growing areas in financial analysis by two of the most accomplished young econometricians in Europe. This classroom-tested advanced undergraduate and graduate textbook provides an in-depth treatment of recently developed nonlinear models, including regime-switching and artificial neural networks, and applies them to describing and forecasting financial asset returns and volatility. It uses a wide range of financial data, drawn from sources including the markets of Tokyo, London and Frankfurt.