

Więcej o książce
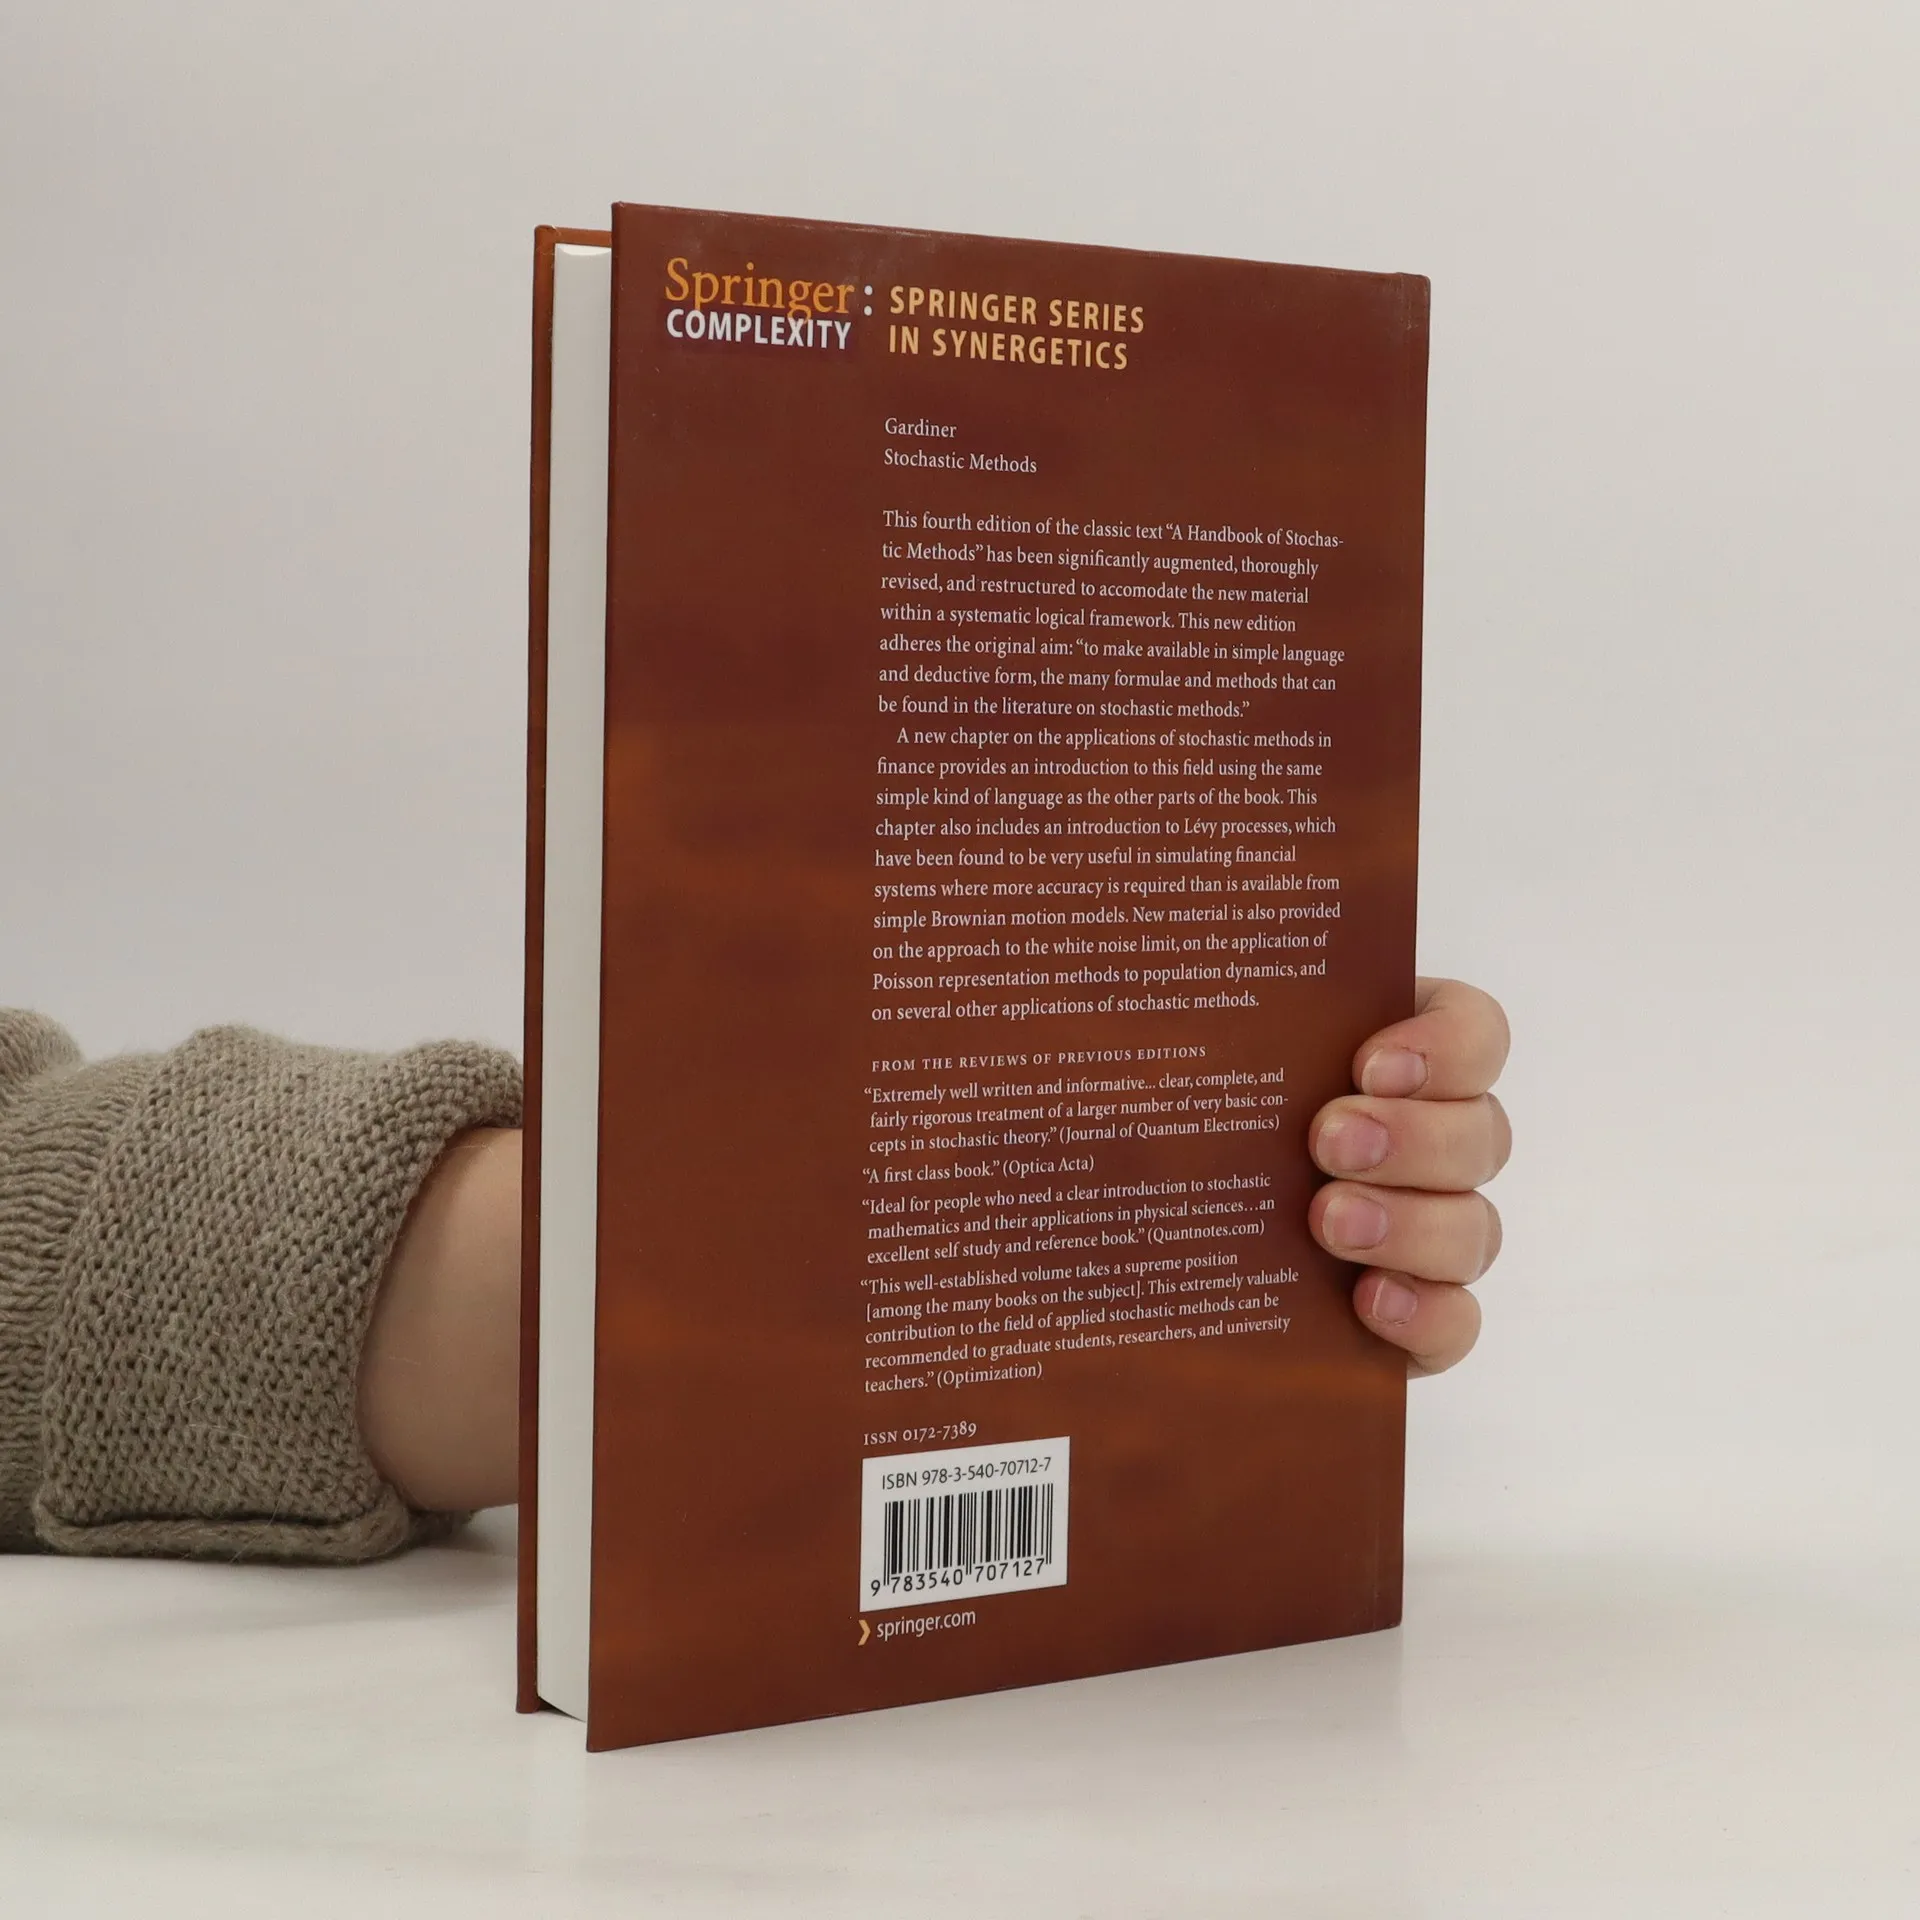
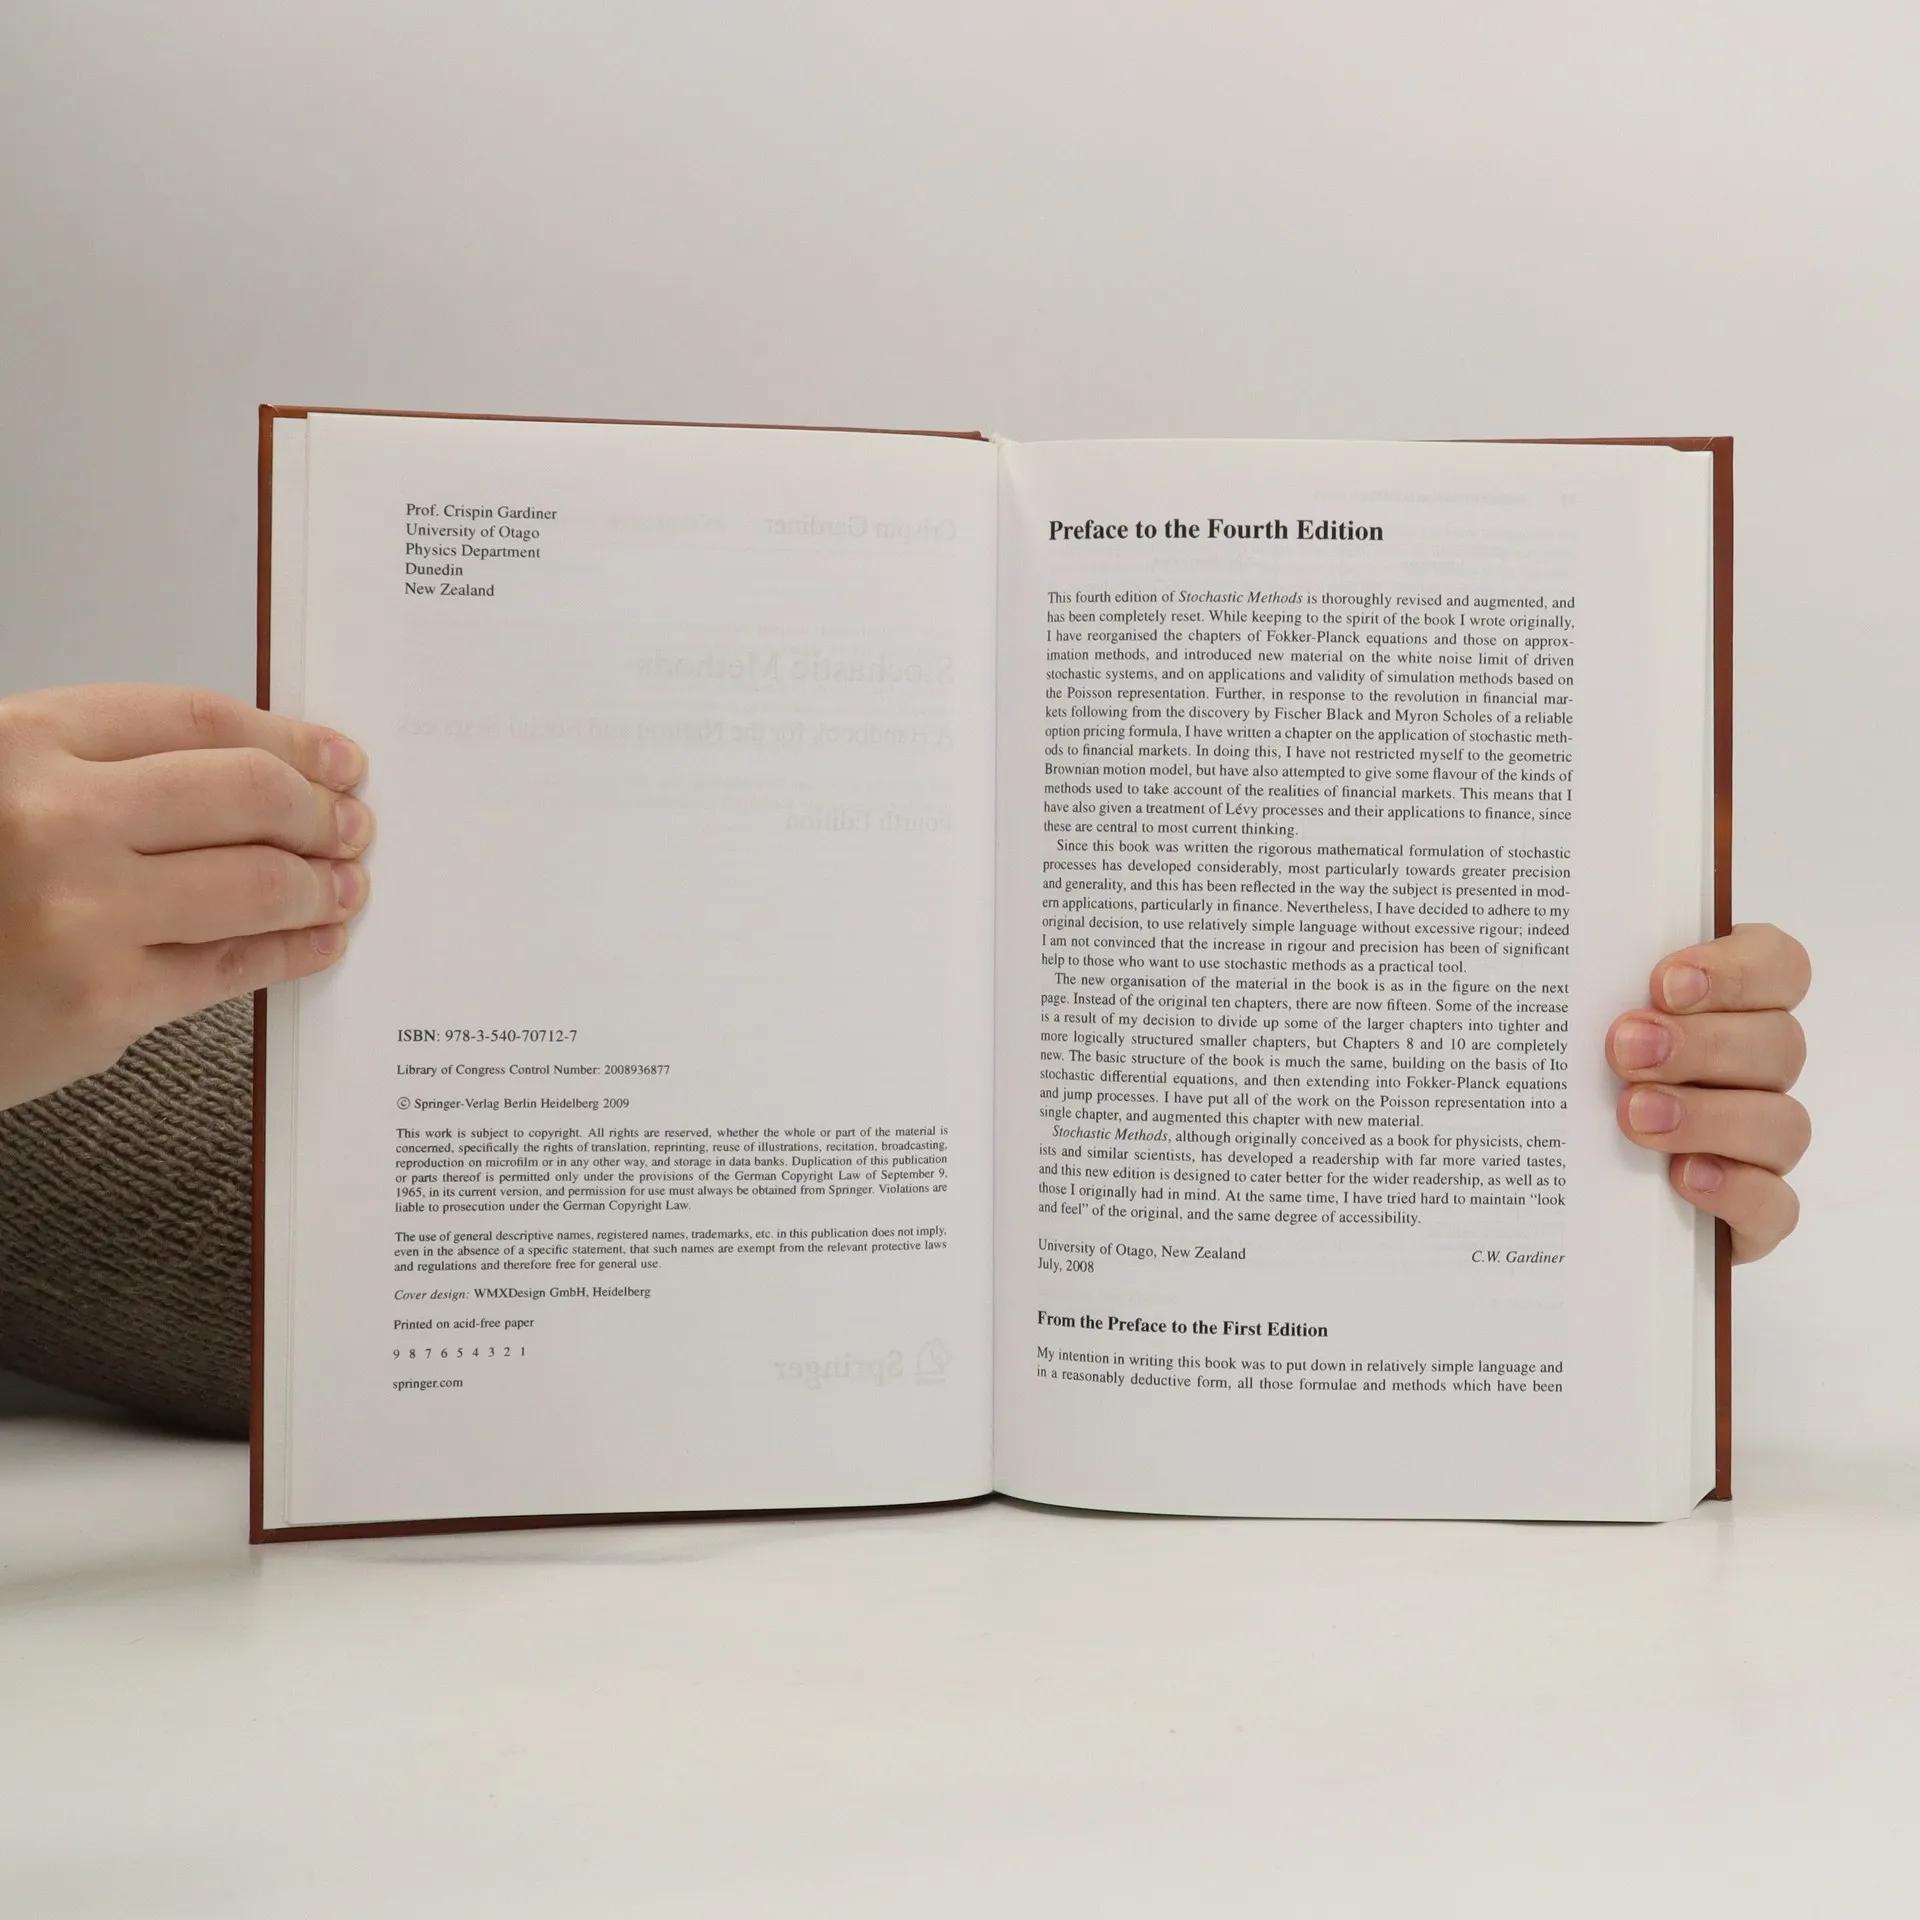
This fourth edition of Stochastic Methods is thoroughly revised and augmented, and has been completely reset. While keeping to the spirit of the book I wrote originally, I have reorganised the chapters of Fokker-Planck equations and those on appr- imation methods, and introduced new material on the white noise limit of driven stochastic systems, and on applications and validity of simulation methods based on the Poisson representation. Further, in response to the revolution in ? nancial m- kets following from the discovery by Fischer Black and Myron Scholes of a reliable option pricing formula, I have written a chapter on the application of stochastic me- ods to ? nancial markets. In doing this, I have not restricted myself to the geometric Brownian motion model, but have also attempted to give some ? avour of the kinds of methods used to take account of the realities of ? nancial markets. This means that I have also given a treatment of Levy ´ processes and their applications to ? nance, since these are central to most current thinking. Since this book was written the rigorous mathematical formulation of stochastic processes has developed considerably, most particularly towards greater precision and generality, and this has been re? ected in the way the subject is presented in m- ern applications, particularly in ? nance.
Zakup książki
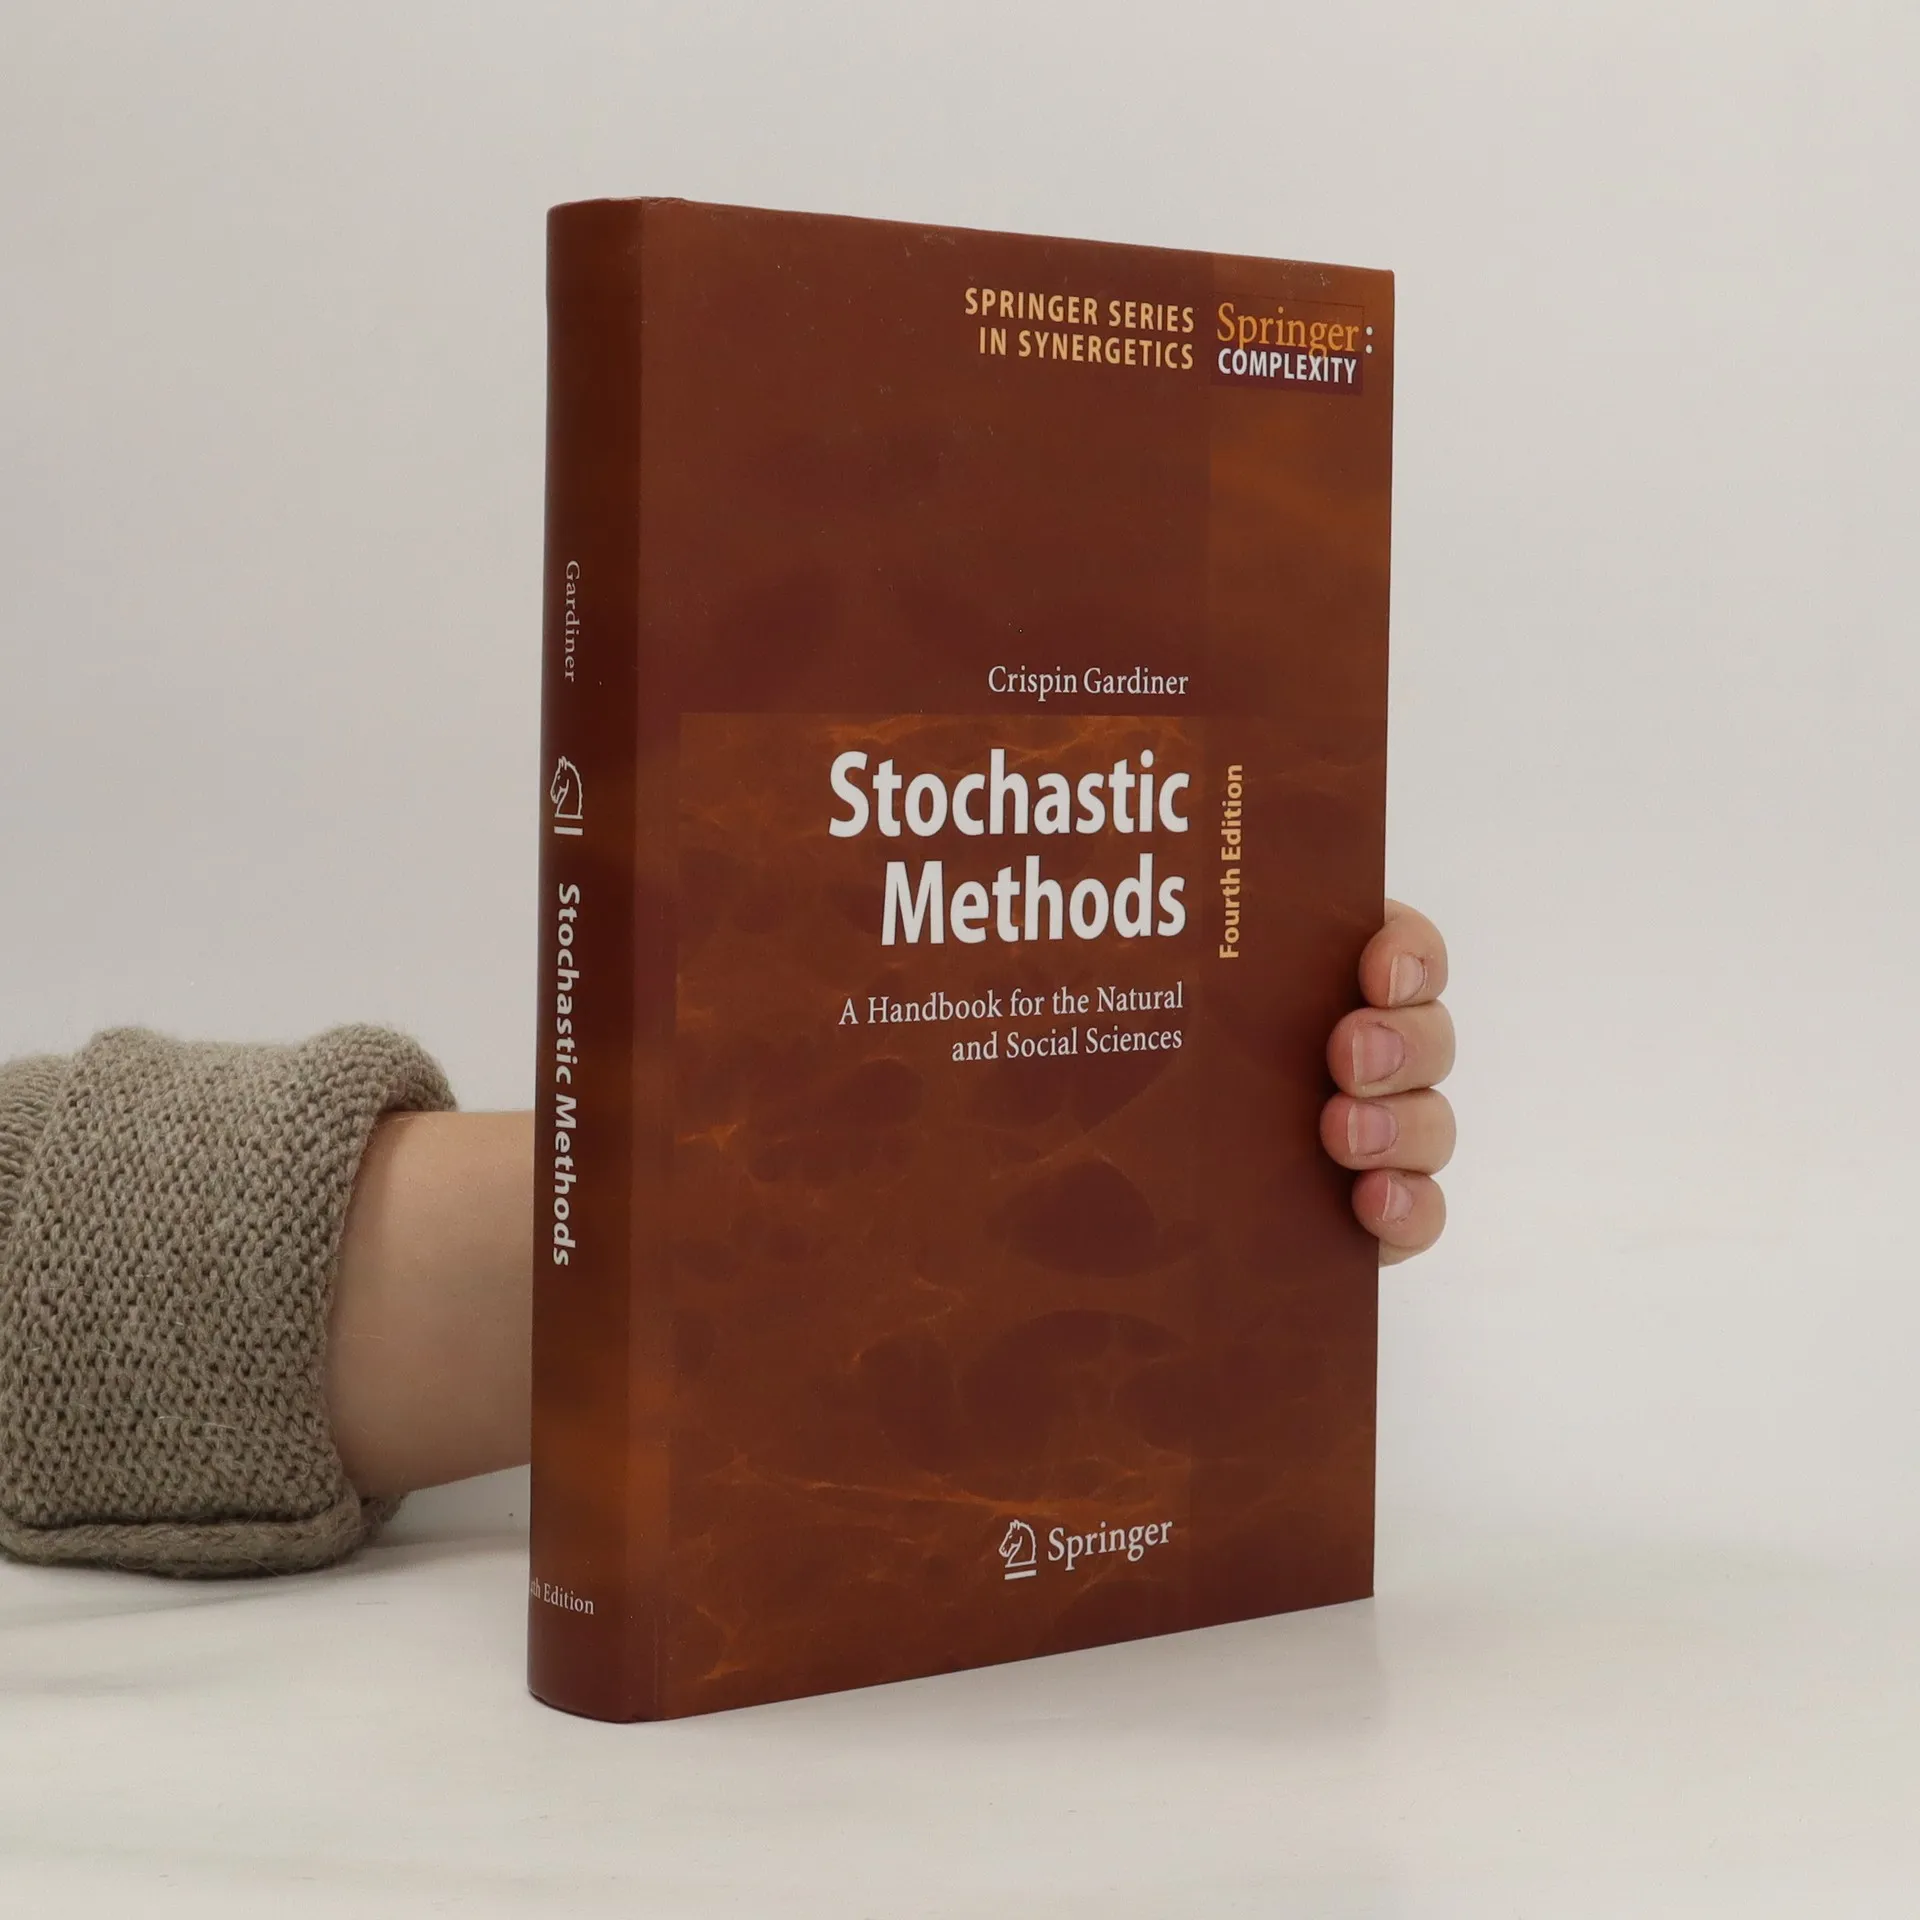
Stochastic methods, Crispin W. Gardiner
- Język

- Rok wydania
- 2009
- Oprawa
- (twarda)
Metody płatności
Brakuje nam tutaj Twojej recenzji.
- Tytuł
- Stochastic methods
- Podtytuł
- A Handbook for the Natural and Social Sciences
- Język
- angielski
- Autorzy
- Crispin W. Gardiner
- Wydawca
- Springer
- Rok wydania
- 2009
- Oprawa
- twarda
- Liczba stron
- 447
- ISBN10
- 3540707123
- ISBN13
- 9783540707127
- Seria
- Ocena
- 4,75 z 5
- Opis
- This fourth edition of Stochastic Methods is thoroughly revised and augmented, and has been completely reset. While keeping to the spirit of the book I wrote originally, I have reorganised the chapters of Fokker-Planck equations and those on appr- imation methods, and introduced new material on the white noise limit of driven stochastic systems, and on applications and validity of simulation methods based on the Poisson representation. Further, in response to the revolution in ? nancial m- kets following from the discovery by Fischer Black and Myron Scholes of a reliable option pricing formula, I have written a chapter on the application of stochastic me- ods to ? nancial markets. In doing this, I have not restricted myself to the geometric Brownian motion model, but have also attempted to give some ? avour of the kinds of methods used to take account of the realities of ? nancial markets. This means that I have also given a treatment of Levy ´ processes and their applications to ? nance, since these are central to most current thinking. Since this book was written the rigorous mathematical formulation of stochastic processes has developed considerably, most particularly towards greater precision and generality, and this has been re? ected in the way the subject is presented in m- ern applications, particularly in ? nance.