

Więcej o książce
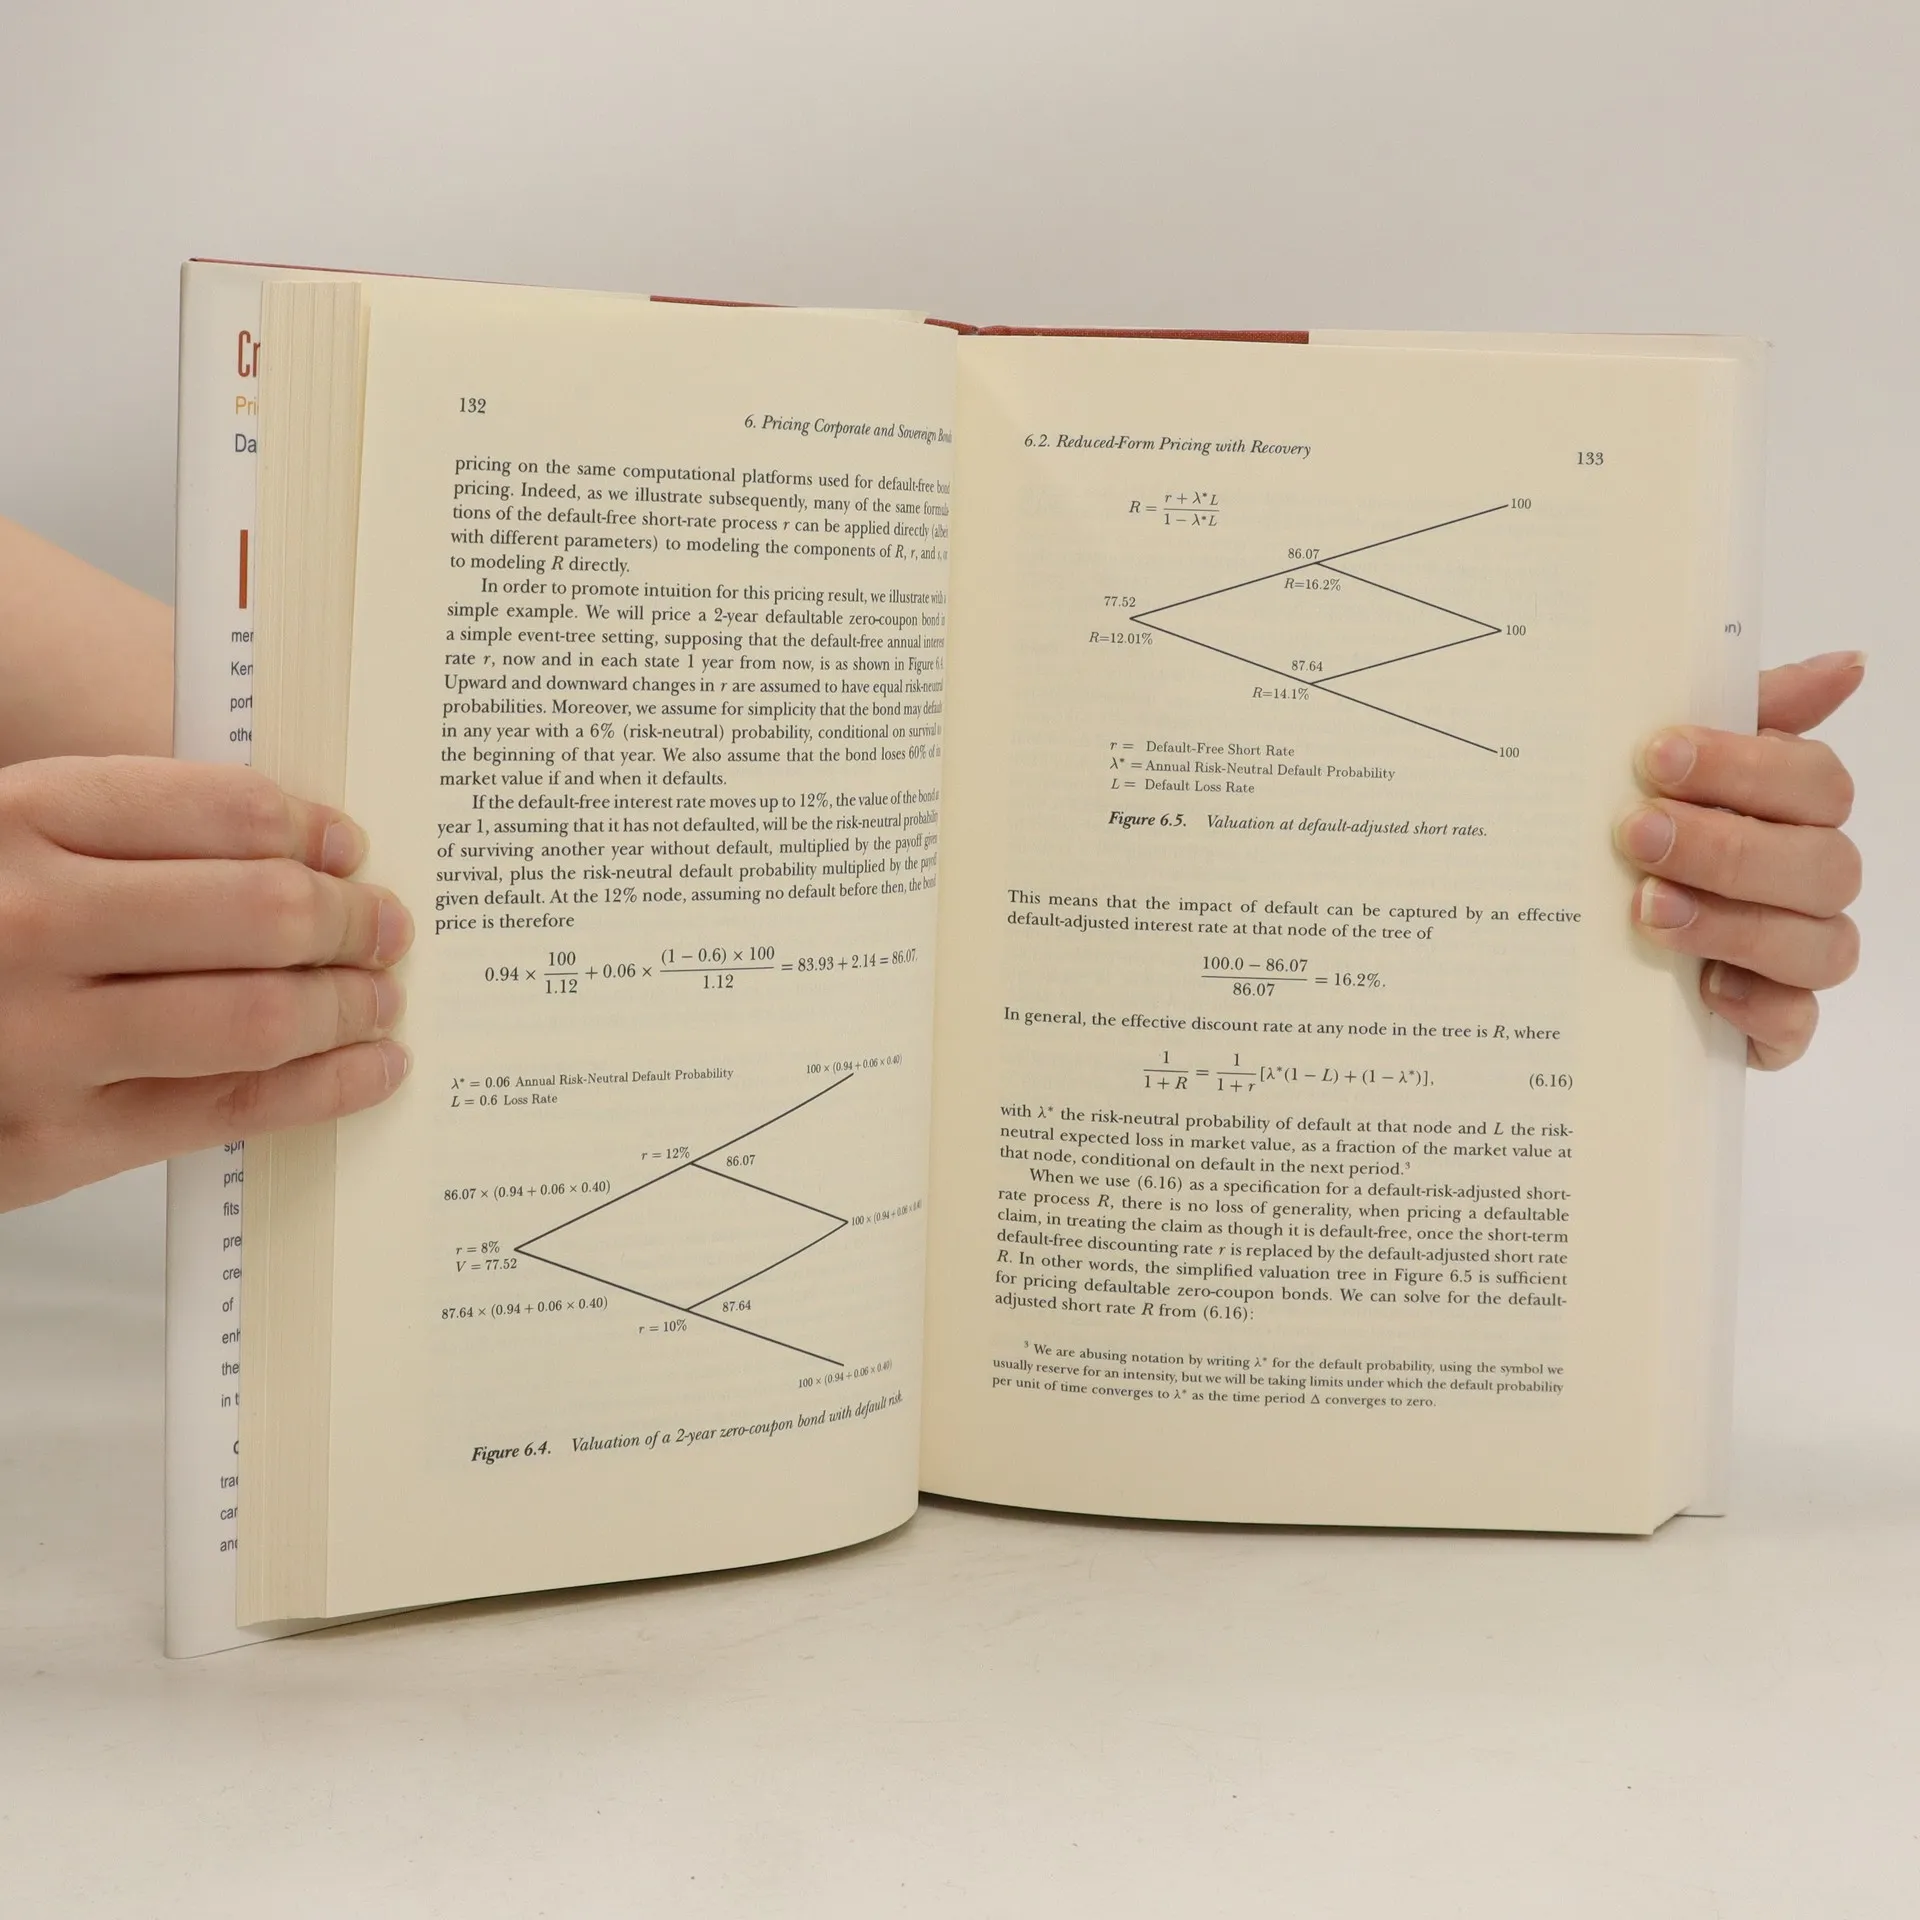
In this book, two leading economists offer a comprehensive exploration of the foundations for credit risk pricing and measurement. Darrell Duffie and Kenneth Singleton adeptly model credit risk to assess portfolio risk and price defaultable bonds, credit derivatives, and other securities subject to credit risk. Their rigorous and sophisticated analysis provides an unparalleled examination of pricing and credit derivatives, addressing a critical issue as financial institutions globally refine their credit management strategies. The authors critically evaluate various credit-risk modeling approaches, discussing their strengths and weaknesses. They combine theoretical insights with extensive empirical analyses of credit-related time series, including default probabilities, recoveries, ratings transitions, and yield spreads. Both "structural" and "reduced-form" methods for pricing defaultable securities are presented, with assessments of their historical data fits. The book also covers the pricing of credit derivatives such as credit swaps, collateralized debt obligations, credit guarantees, lines of credit, and spread options. Furthermore, the authors suggest enhancements to current pricing and management practices to better equip financial institutions for future market changes. This resource is essential for risk managers, traders, regulators, academic researchers, and students engaged with financial products carrying significa
Zakup książki
Credit Risk, Darrell Duffie, Kenneth J. Singleton
- Język

- Rok wydania
- 2003
- Oprawa
- (twarda)
Metody płatności
Brakuje nam tutaj Twojej recenzji.
- Tytuł
- Credit Risk
- Język
- angielski
- Autorzy
- Darrell Duffie, Kenneth J. Singleton
- Wydawca
- Princeton University Press
- Rok wydania
- 2003
- Oprawa
- twarda
- Liczba stron
- 464
- ISBN10
- 0691090467
- ISBN13
- 9780691090467
- Seria
- Ocena
- 2,6 z 5
- Opis
- In this book, two leading economists offer a comprehensive exploration of the foundations for credit risk pricing and measurement. Darrell Duffie and Kenneth Singleton adeptly model credit risk to assess portfolio risk and price defaultable bonds, credit derivatives, and other securities subject to credit risk. Their rigorous and sophisticated analysis provides an unparalleled examination of pricing and credit derivatives, addressing a critical issue as financial institutions globally refine their credit management strategies. The authors critically evaluate various credit-risk modeling approaches, discussing their strengths and weaknesses. They combine theoretical insights with extensive empirical analyses of credit-related time series, including default probabilities, recoveries, ratings transitions, and yield spreads. Both "structural" and "reduced-form" methods for pricing defaultable securities are presented, with assessments of their historical data fits. The book also covers the pricing of credit derivatives such as credit swaps, collateralized debt obligations, credit guarantees, lines of credit, and spread options. Furthermore, the authors suggest enhancements to current pricing and management practices to better equip financial institutions for future market changes. This resource is essential for risk managers, traders, regulators, academic researchers, and students engaged with financial products carrying significa