

Więcej o książce
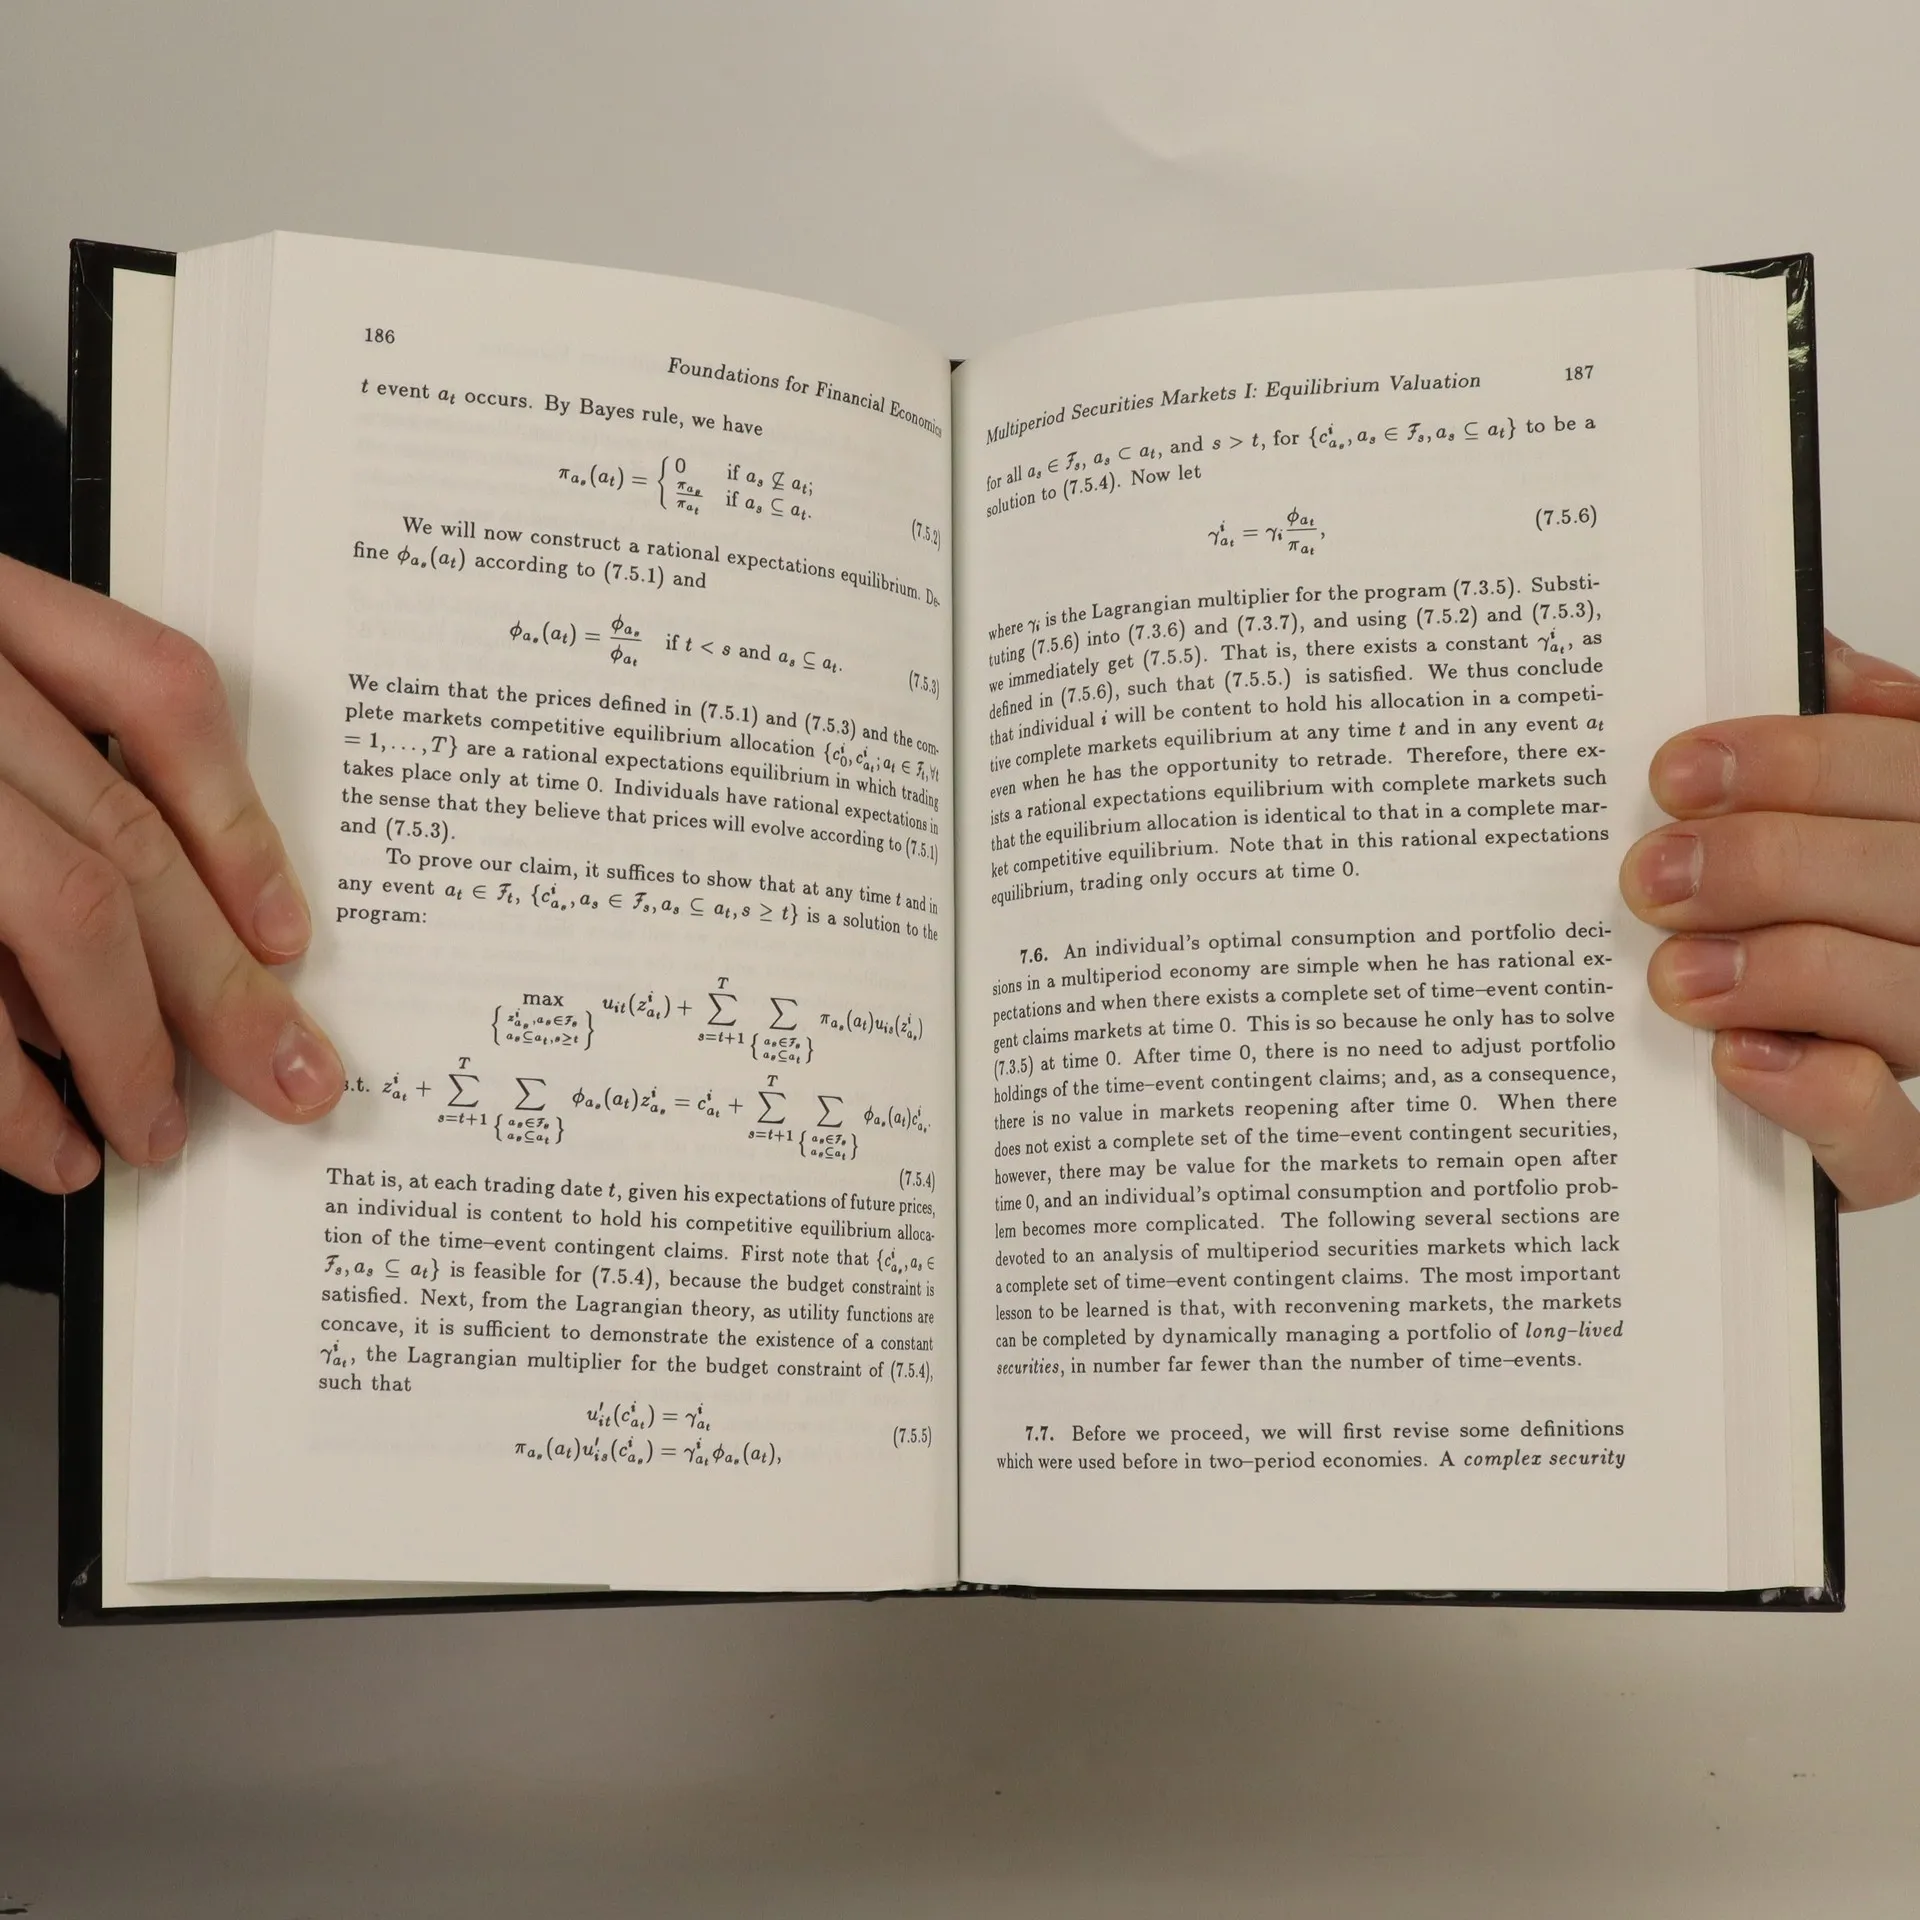
Based on formal derivations of financial theory, this volume provides a rigorous exploration of individual's consumption and portfolio decisions under uncertainty. Features in-depth coverage of such topics as: concepts of risk aversion and stochastic dominance; mathematical properties of a portfolio frontier; distributional conditions for mutual fund separation; capital asset pricing models and arbitrage pricing models; general pricing rules for securities that pay off in more than one state of nature; the pricing of options; rational expectation models of risky asset prices; signaling models; how multiperiod dynamic economies can be modeled; a multiperiod economy with emphasis on valuation by arbitrage; econometric issues associated with testing capital asset pricing models. For readers interested in a rigorous overview of financial economicsn individual consumption point of view. …• 1988
Zakup książki
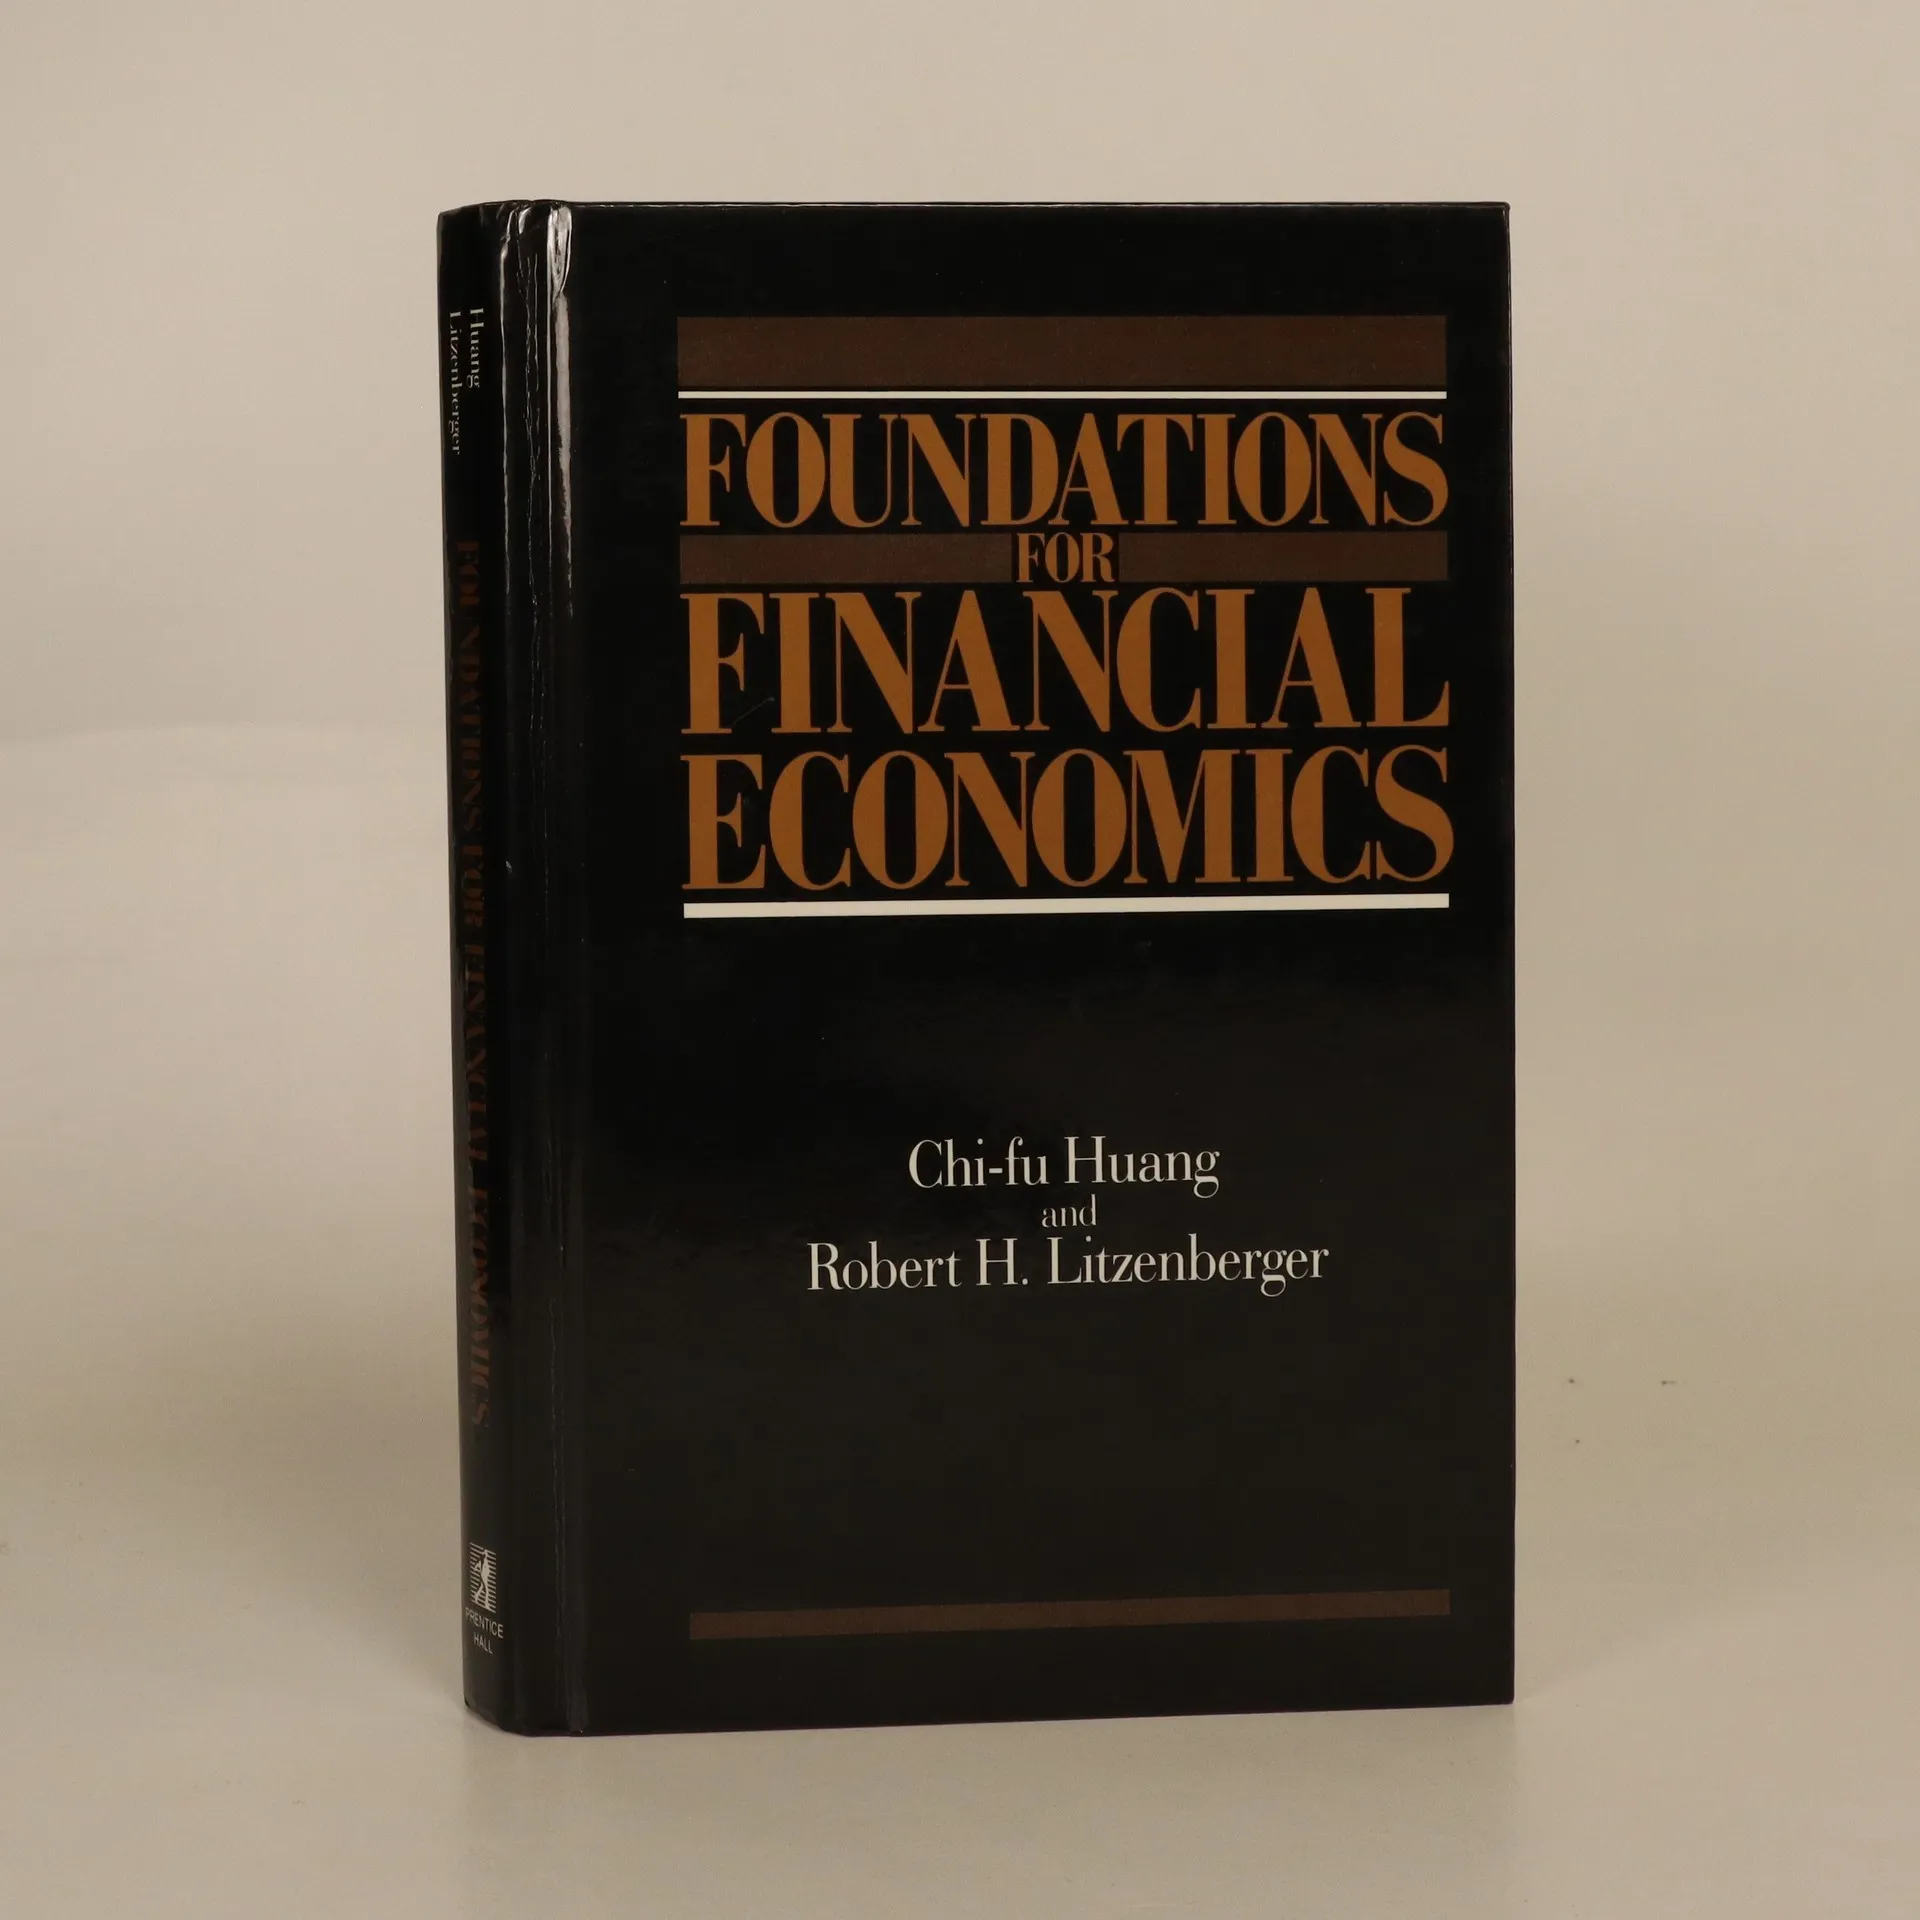
Foundations for financial economics, Chi fu Huang, Robert H. Litzenberger
- Język

- Rok wydania
- 1998
- Oprawa
- (miękka)
Metody płatności
Brakuje nam tutaj Twojej recenzji.
- Tytuł
- Foundations for financial economics
- Język
- angielski
- Autorzy
- Chi fu Huang, Robert H. Litzenberger
- Wydawca
- Prentice Hall
- Rok wydania
- 1998
- Oprawa
- miękka
- Liczba stron
- 364
- ISBN10
- 0135006538
- ISBN13
- 9780135006535
- Seria
- Ocena
- 3,5 z 5
- Opis
- Based on formal derivations of financial theory, this volume provides a rigorous exploration of individual's consumption and portfolio decisions under uncertainty. Features in-depth coverage of such topics as: concepts of risk aversion and stochastic dominance; mathematical properties of a portfolio frontier; distributional conditions for mutual fund separation; capital asset pricing models and arbitrage pricing models; general pricing rules for securities that pay off in more than one state of nature; the pricing of options; rational expectation models of risky asset prices; signaling models; how multiperiod dynamic economies can be modeled; a multiperiod economy with emphasis on valuation by arbitrage; econometric issues associated with testing capital asset pricing models. For readers interested in a rigorous overview of financial economicsn individual consumption point of view. …• 1988