

Więcej o książce
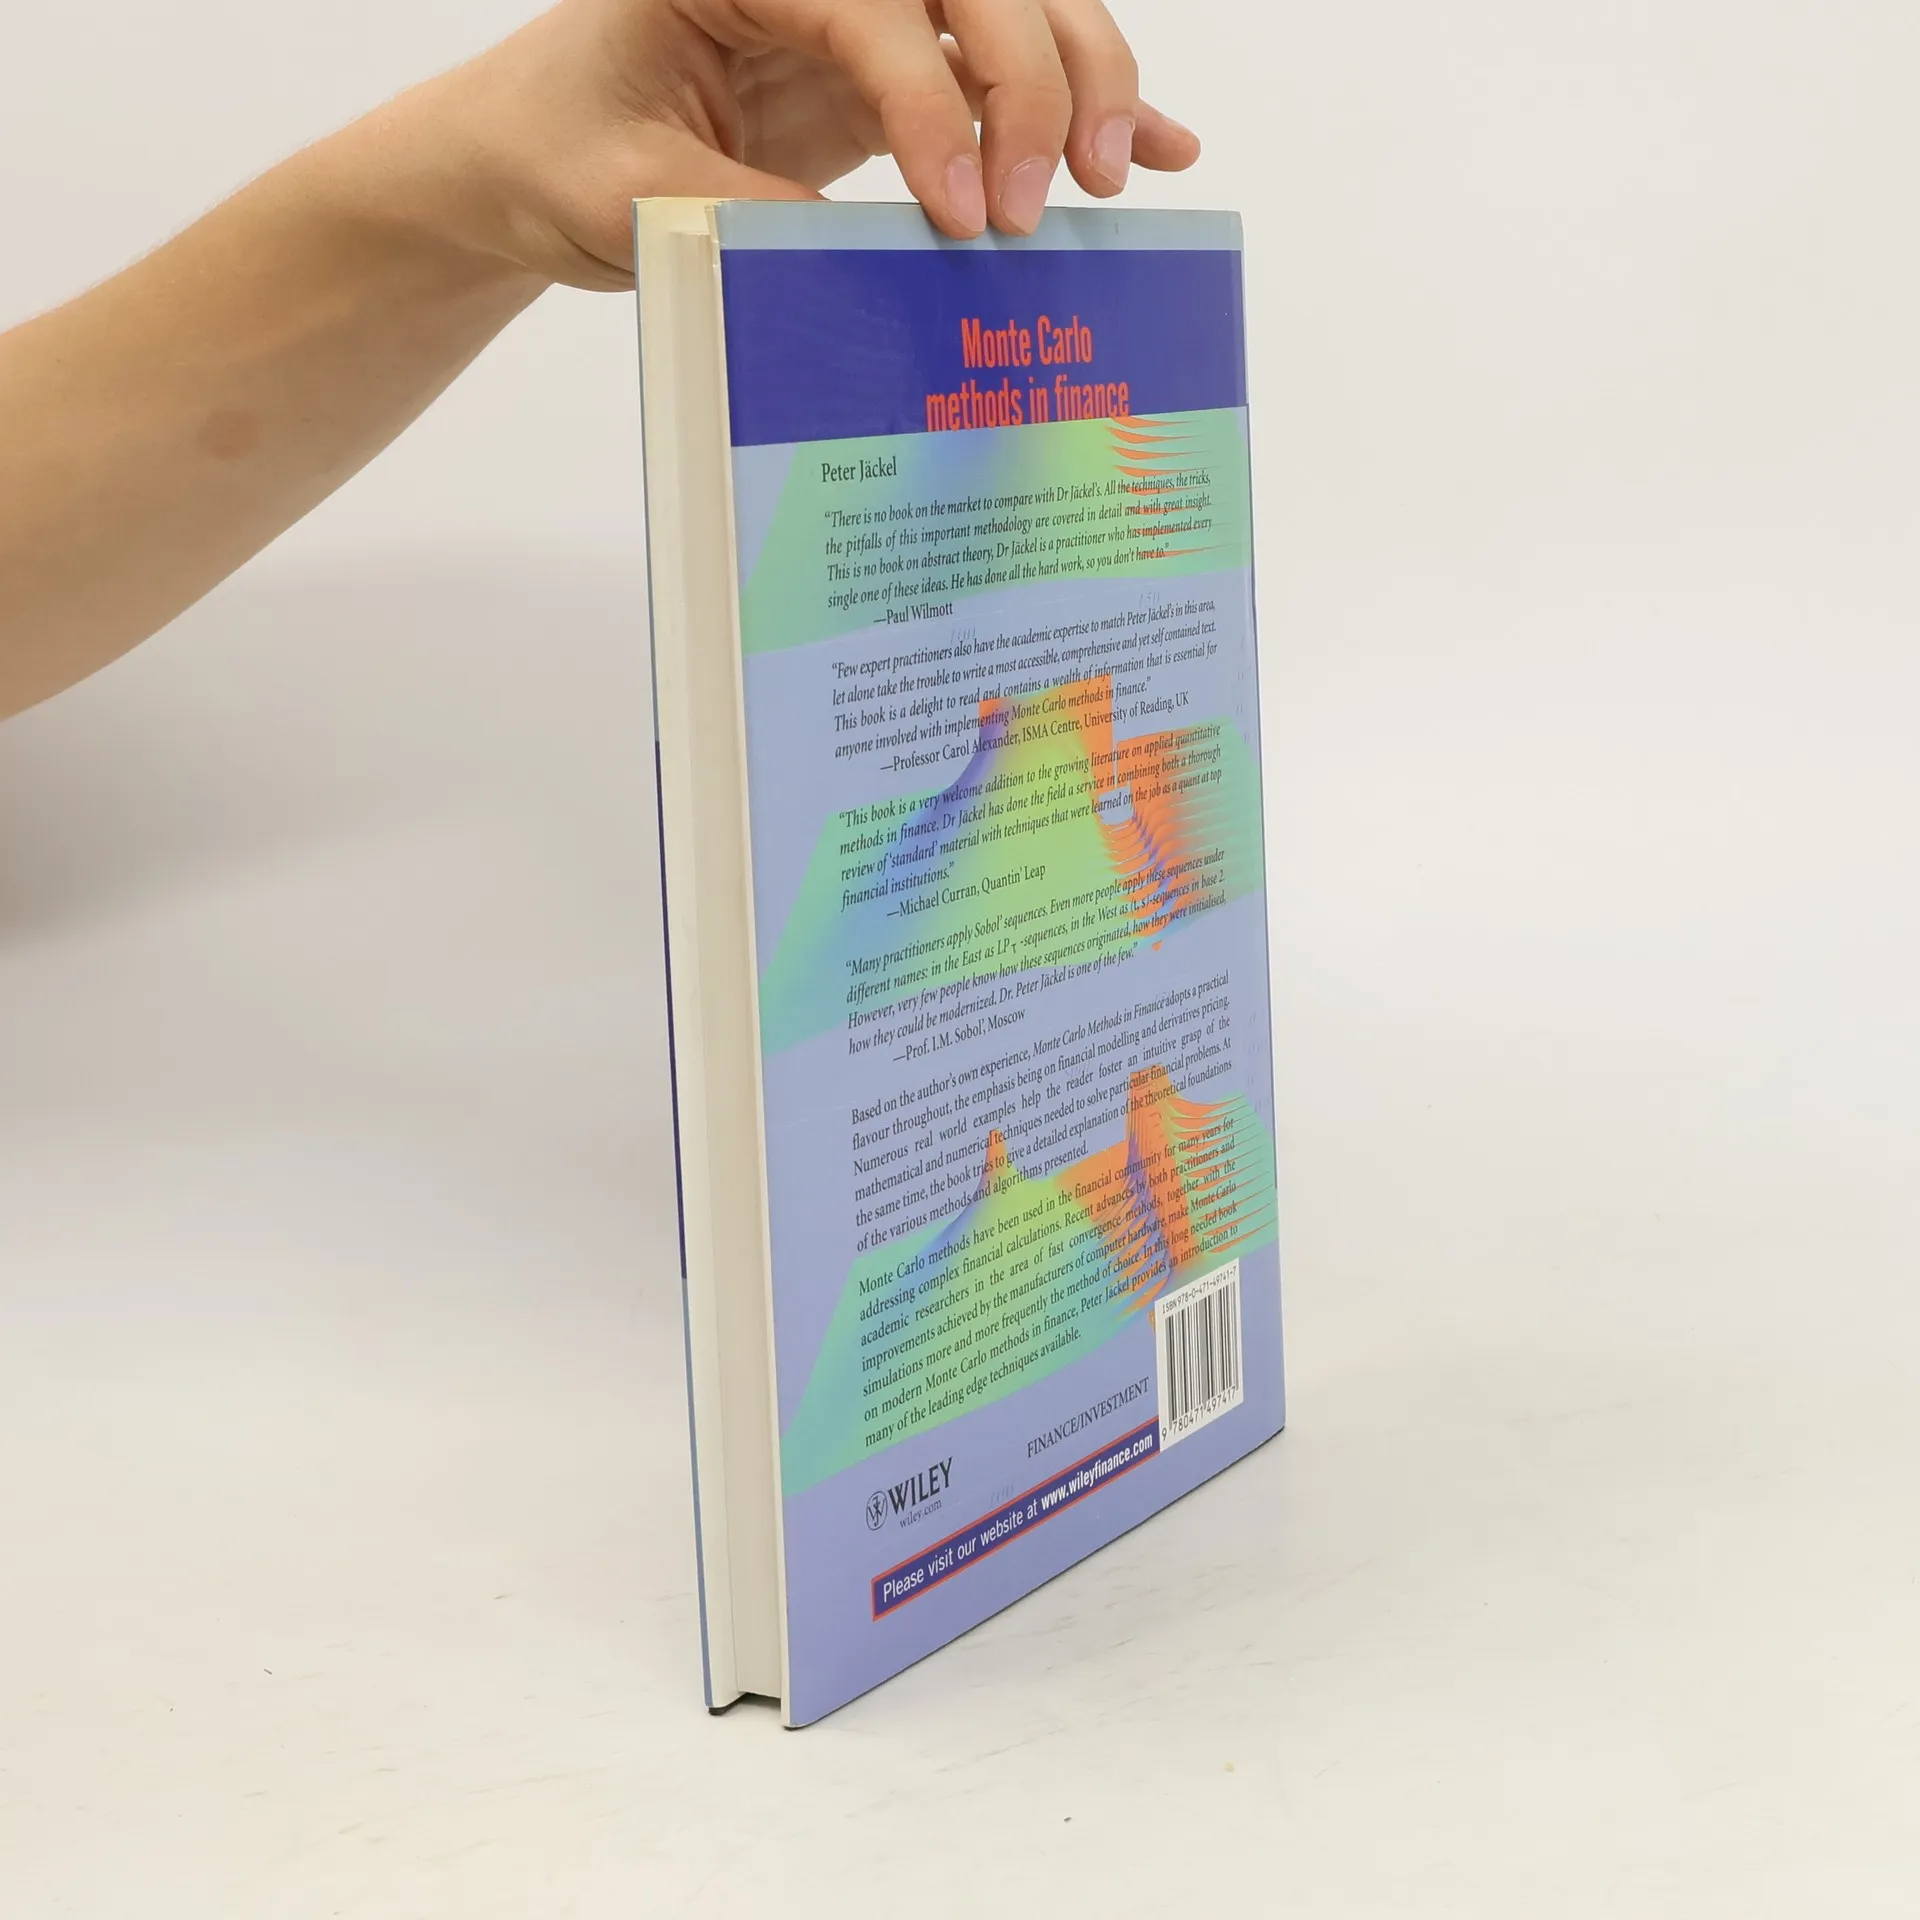
An invaluable resource for quantitative analysts who need to run models that assist in option pricing and risk management. This concise, practical hands on guide to Monte Carlo simulation introduces standard and advanced methods to the increasing complexity of derivatives portfolios. Ranging from pricing more complex derivatives, such as American and Asian options, to measuring Value at Risk, or modelling complex market dynamics, simulation is the only method general enough to capture the complexity and Monte Carlo simulation is the best pricing and risk management method available.The book is packed with numerous examples using real world data and is supplied with a CD to aid in the use of the examples.
Zakup książki
Monte Carlo Methods in Finance, Peter Jäckel
- Język

- Rok wydania
- 2002
- Oprawa
- (twarda)
Metody płatności
Brakuje nam tutaj Twojej recenzji.
- Tytuł
- Monte Carlo Methods in Finance
- Język
- angielski
- Autorzy
- Peter Jäckel
- Wydawca
- John Wiley & Sons
- Rok wydania
- 2002
- Oprawa
- twarda
- Liczba stron
- 304
- ISBN10
- 047149741X
- ISBN13
- 9780471497417
- Seria
- Ocena
- 4,35 z 5
- Opis
- An invaluable resource for quantitative analysts who need to run models that assist in option pricing and risk management. This concise, practical hands on guide to Monte Carlo simulation introduces standard and advanced methods to the increasing complexity of derivatives portfolios. Ranging from pricing more complex derivatives, such as American and Asian options, to measuring Value at Risk, or modelling complex market dynamics, simulation is the only method general enough to capture the complexity and Monte Carlo simulation is the best pricing and risk management method available.The book is packed with numerous examples using real world data and is supplied with a CD to aid in the use of the examples.