

Więcej o książce
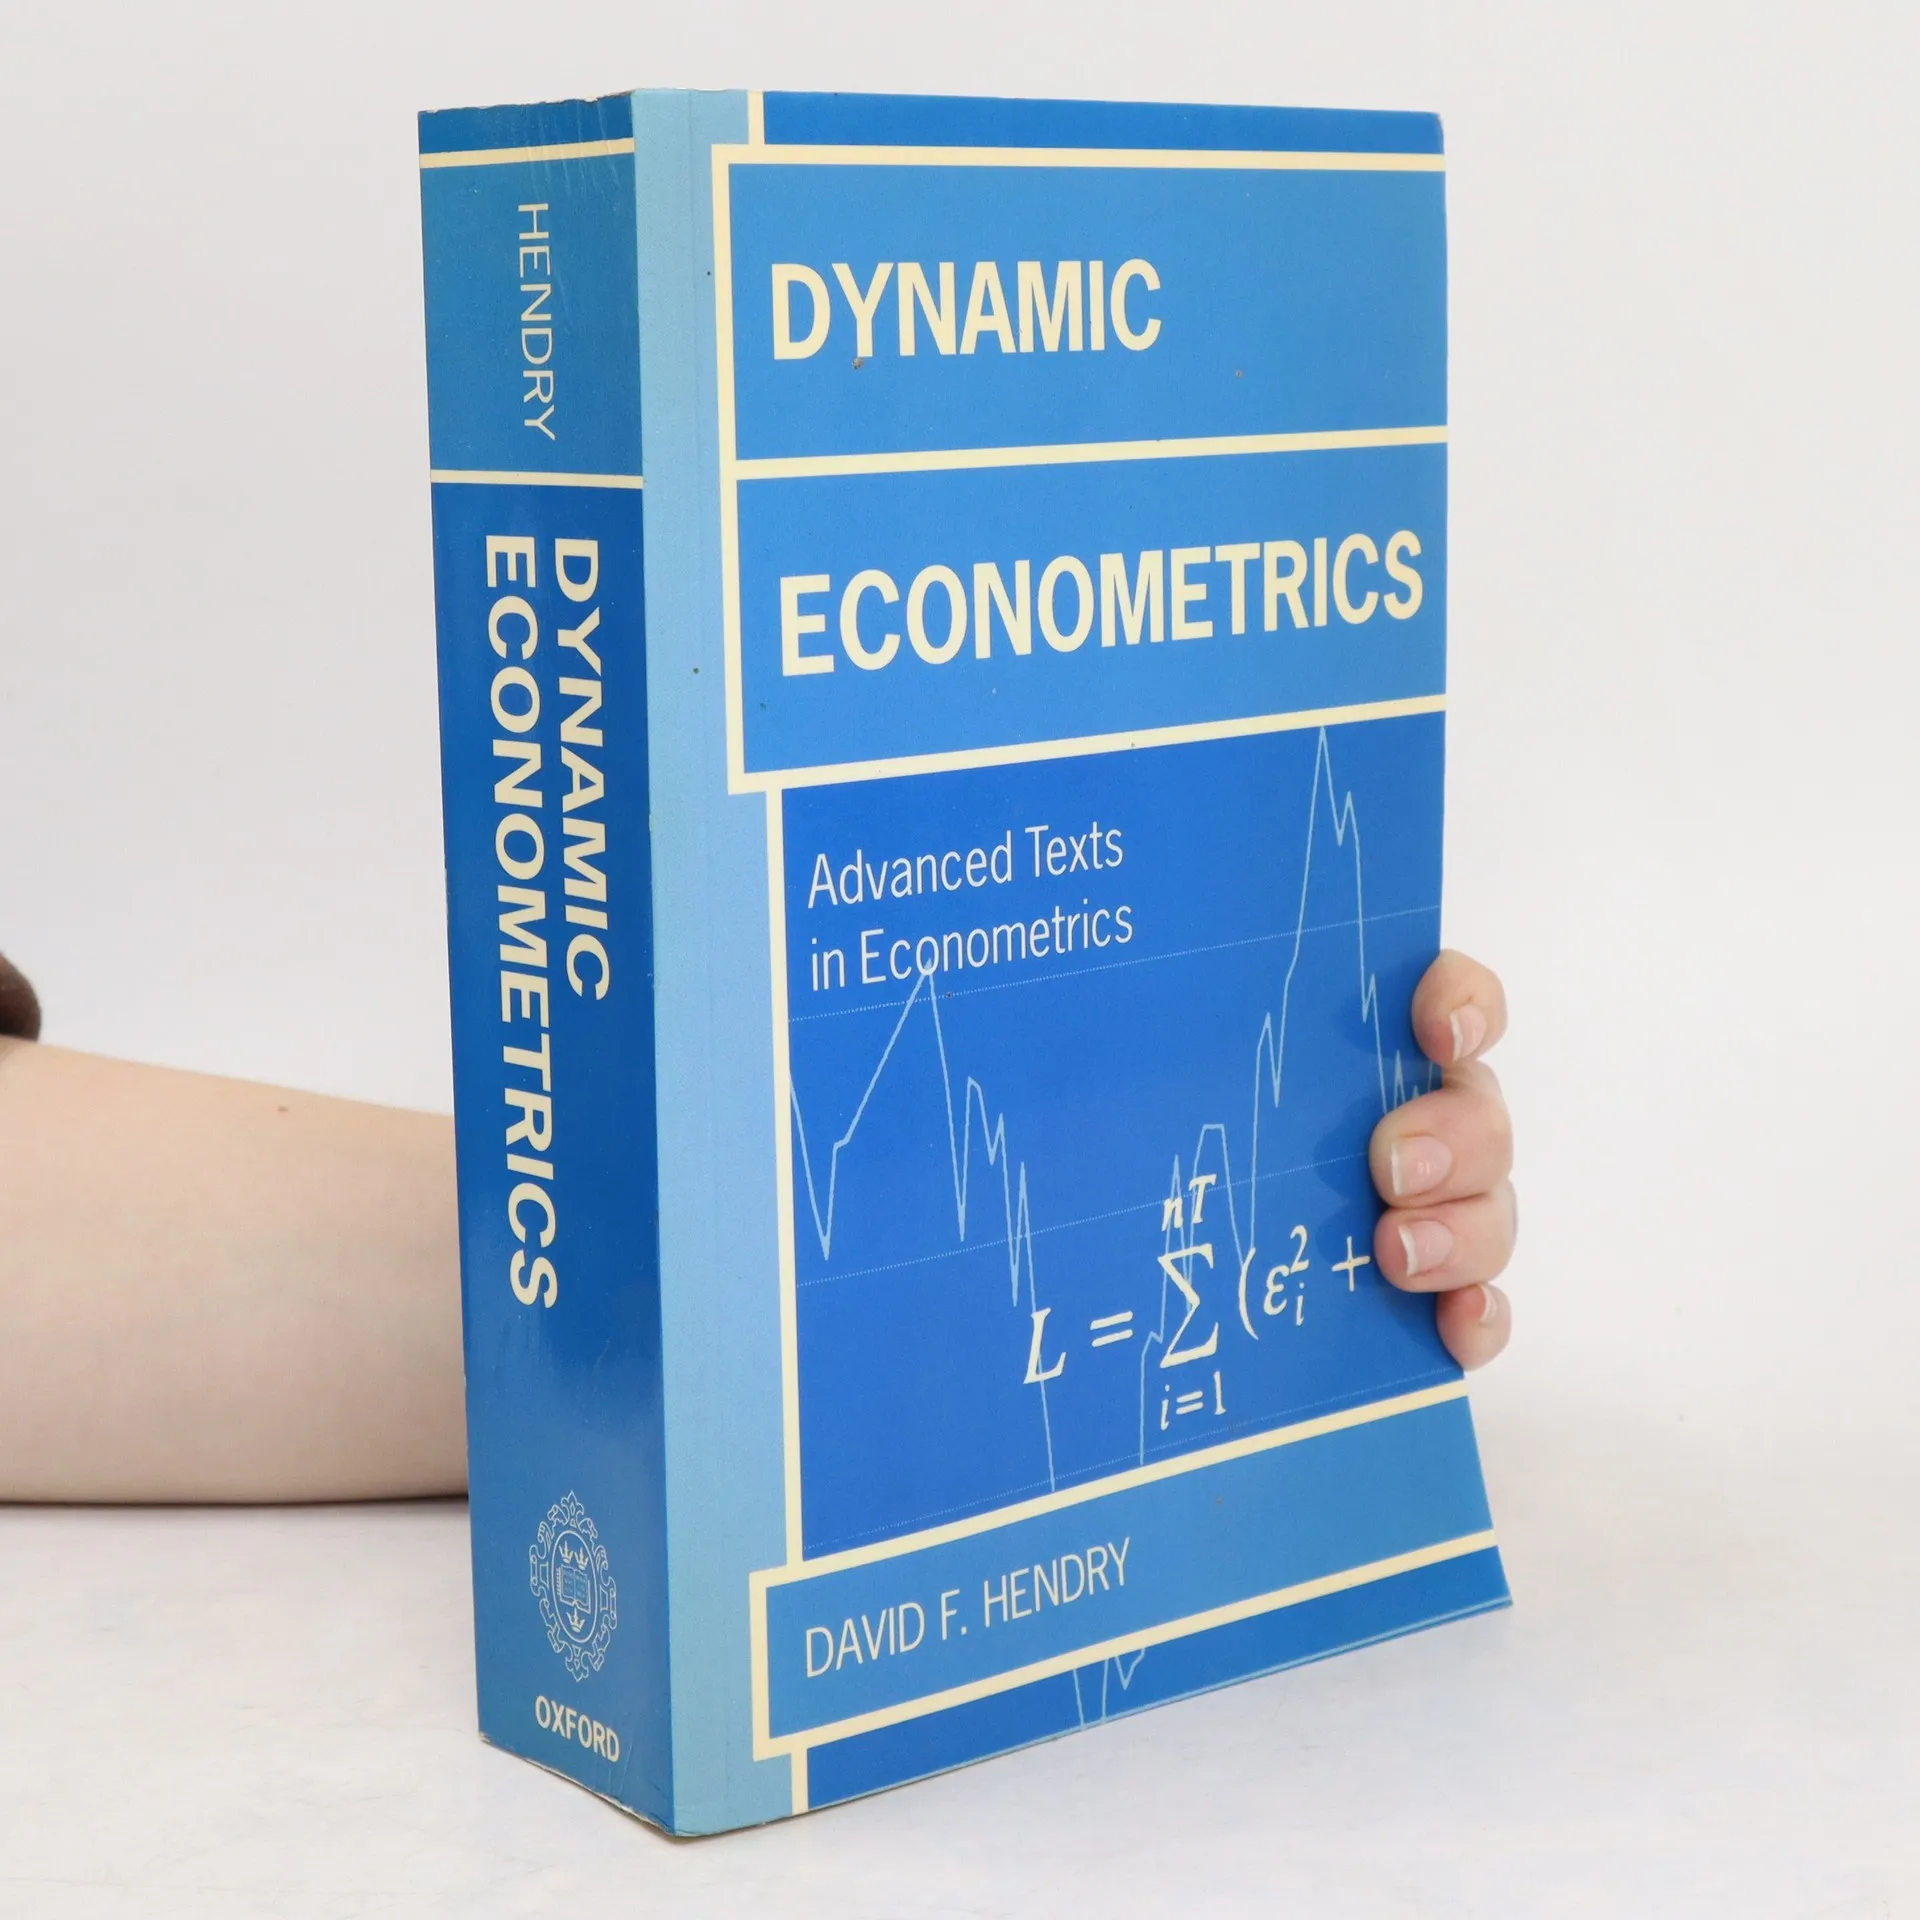
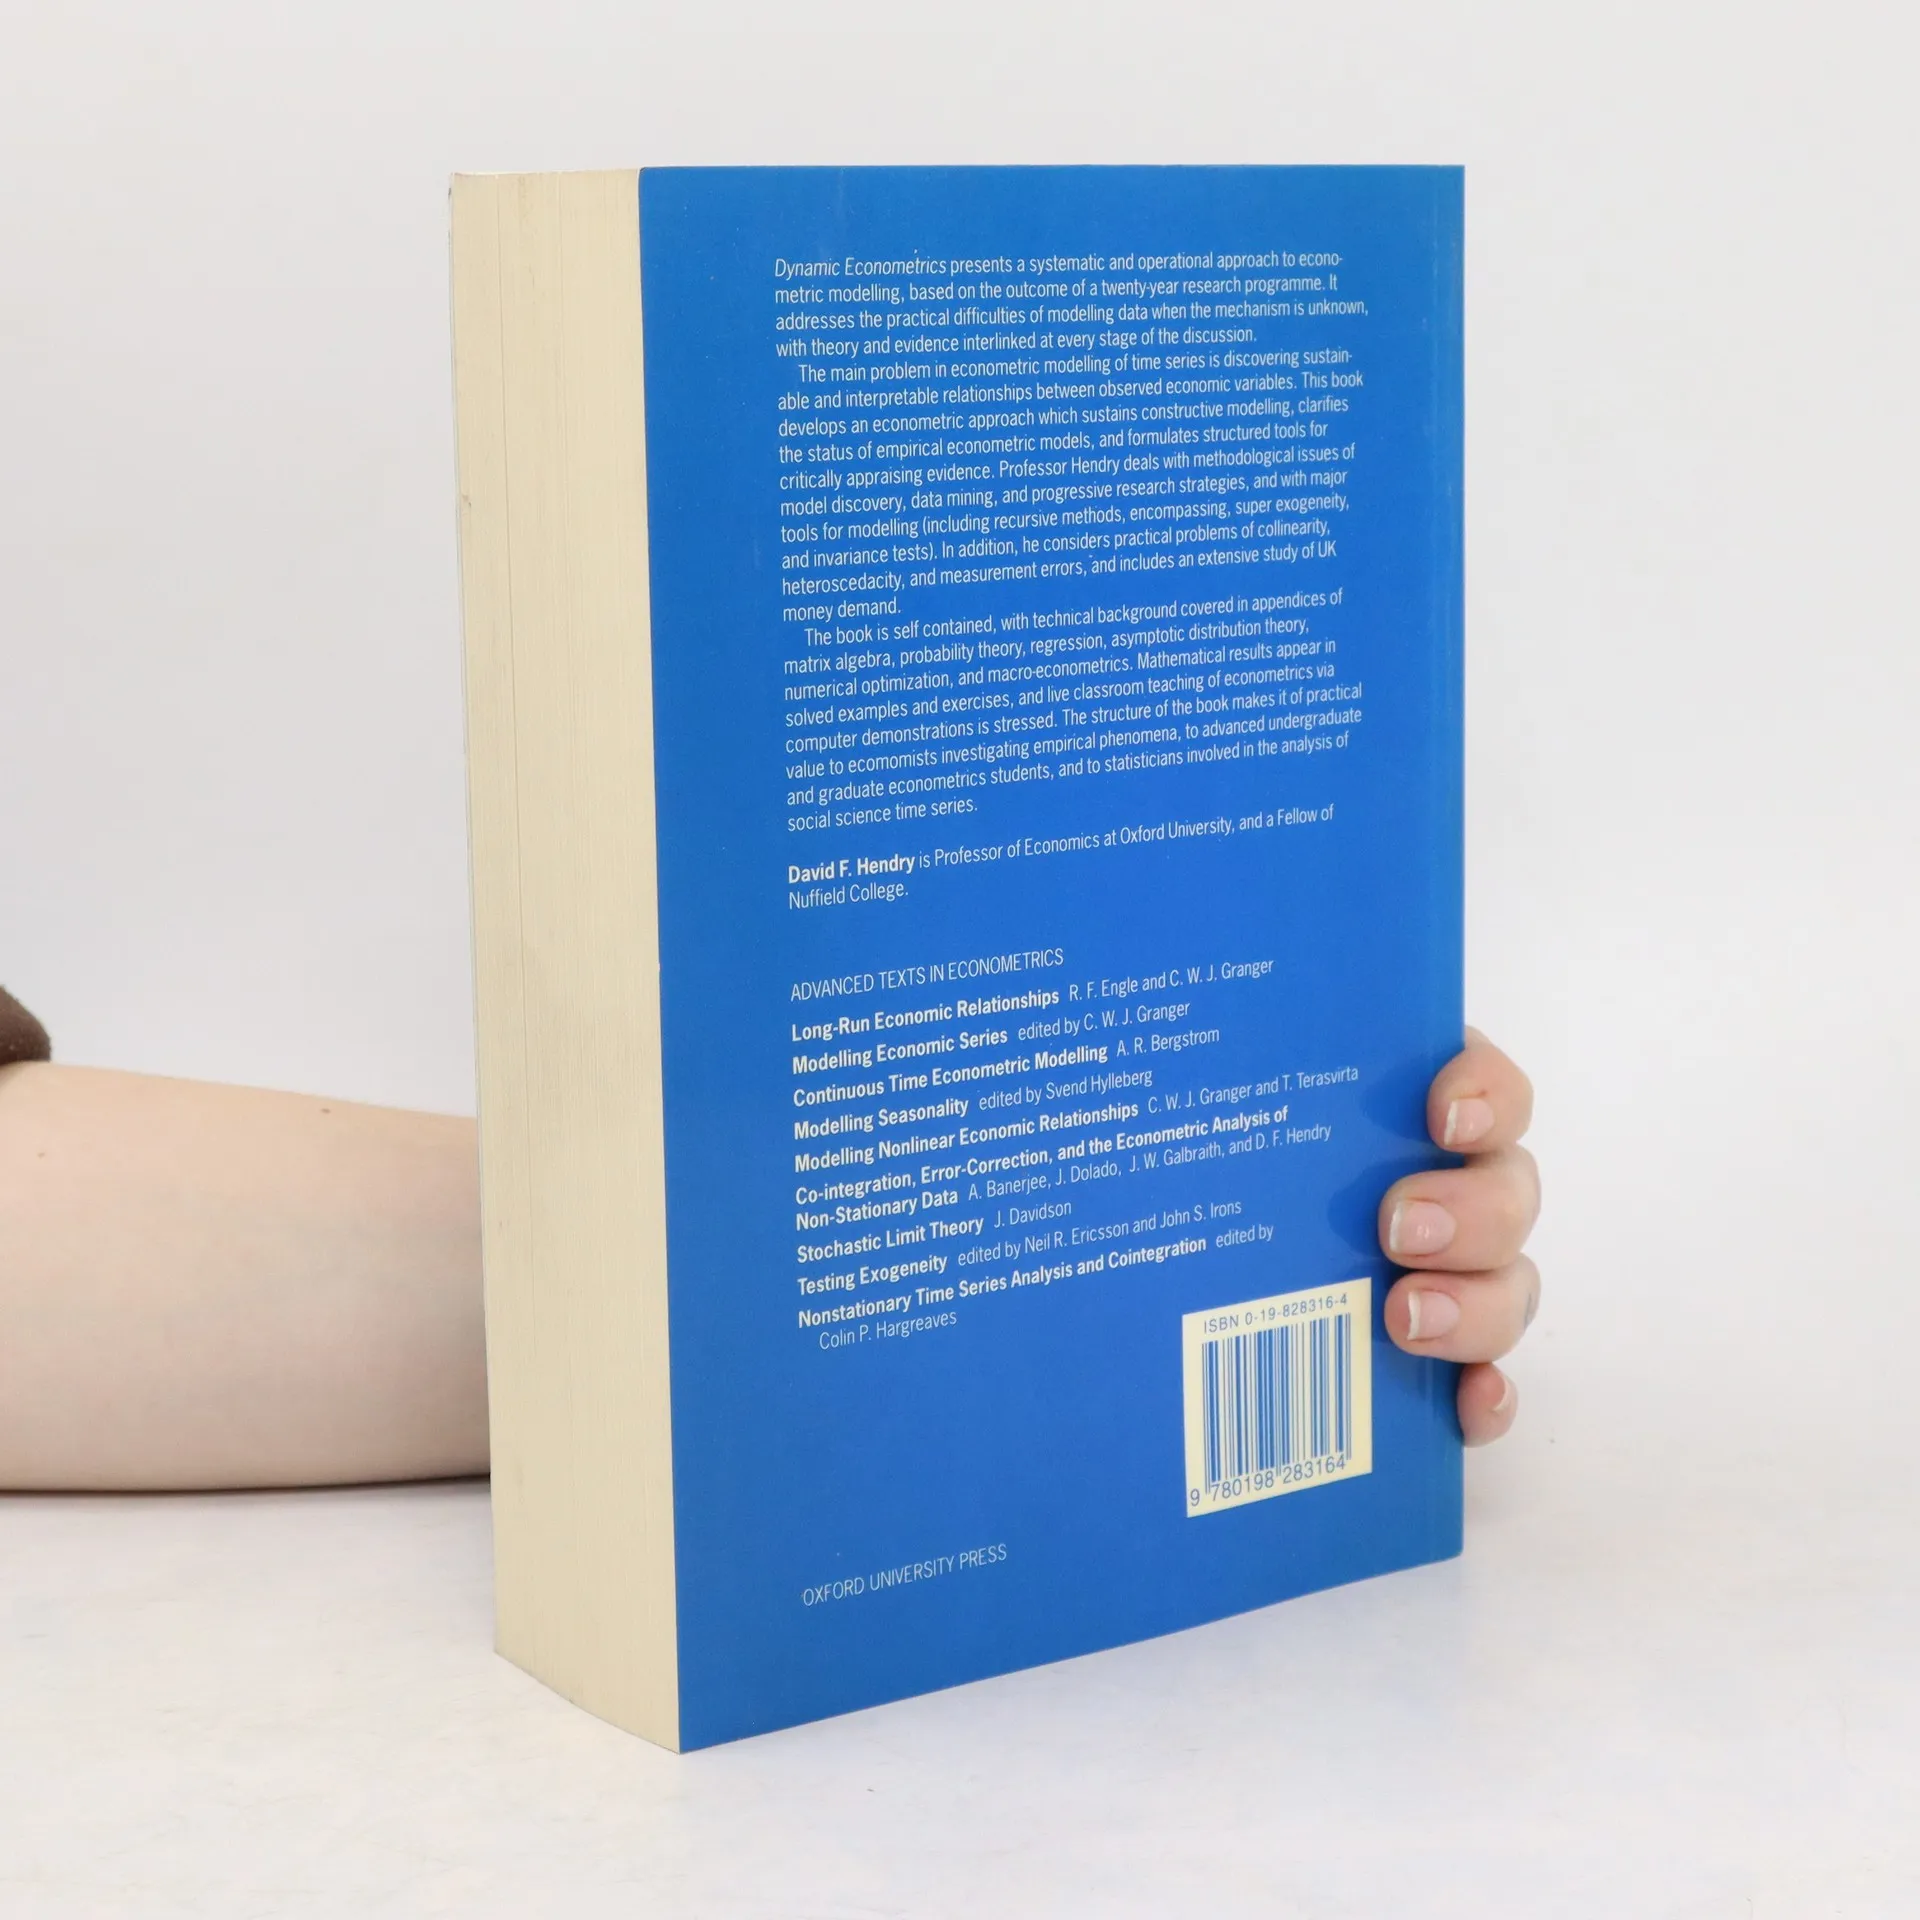
The main problem in econometric modelling of time series is discovering sustainable and interpretable relationships between observed economic variables. The primary aim of this book is to develop an operational econometric approach which allows constructive modelling. Professor Hendry deals with methodological issues (model discovery, data mining, and progressive research strategies); with major tools for modelling (recursive methods, encompassing, super exogeneity, invariance tests); and with practical problems (collinearity, heteroscedasticity, and measurement errors). He also includes an extensive study of US money demand. The book is self-contained, with the technical background covered in appendices. It is thus suitable for first year graduate students, and includes solved examples and exercises to facilitate its use in teaching.About the SeriesAdvanced Texts in Econometrics is a distinguished and rapidly expanding series in which leading econometricians assess recent developments in such areas as stochastic probability, panel and time series data analysis, modeling, and cointegration. In both hardback and affordable paperback, each volume explains the nature and applicability of a topic in greater depth than possible in introductory textbooks or single journal articles. Each definitive work is formatted to be as accessible and convenient for those who are not familiar with the detailed primary literature.
Zakup książki
Dynamic Econometrics, David F. Hendry
- Język

- Rok wydania
- 1995
- Oprawa
- (miękka)
Metody płatności
Brakuje nam tutaj Twojej recenzji.
- Tytuł
- Dynamic Econometrics
- Podtytuł
- Advanced Texts in Econometrics
- Język
- angielski
- Autorzy
- David F. Hendry
- Wydawca
- Oxford
- Rok wydania
- 1995
- Oprawa
- miękka
- Liczba stron
- 904
- ISBN10
- 0198283164
- ISBN13
- 9780198283164
- Seria
- Tagi
- Biznes
- Ocena
- 4,1 z 5
- Opis
- The main problem in econometric modelling of time series is discovering sustainable and interpretable relationships between observed economic variables. The primary aim of this book is to develop an operational econometric approach which allows constructive modelling. Professor Hendry deals with methodological issues (model discovery, data mining, and progressive research strategies); with major tools for modelling (recursive methods, encompassing, super exogeneity, invariance tests); and with practical problems (collinearity, heteroscedasticity, and measurement errors). He also includes an extensive study of US money demand. The book is self-contained, with the technical background covered in appendices. It is thus suitable for first year graduate students, and includes solved examples and exercises to facilitate its use in teaching.About the SeriesAdvanced Texts in Econometrics is a distinguished and rapidly expanding series in which leading econometricians assess recent developments in such areas as stochastic probability, panel and time series data analysis, modeling, and cointegration. In both hardback and affordable paperback, each volume explains the nature and applicability of a topic in greater depth than possible in introductory textbooks or single journal articles. Each definitive work is formatted to be as accessible and convenient for those who are not familiar with the detailed primary literature.