

Parametry
Więcej o książce
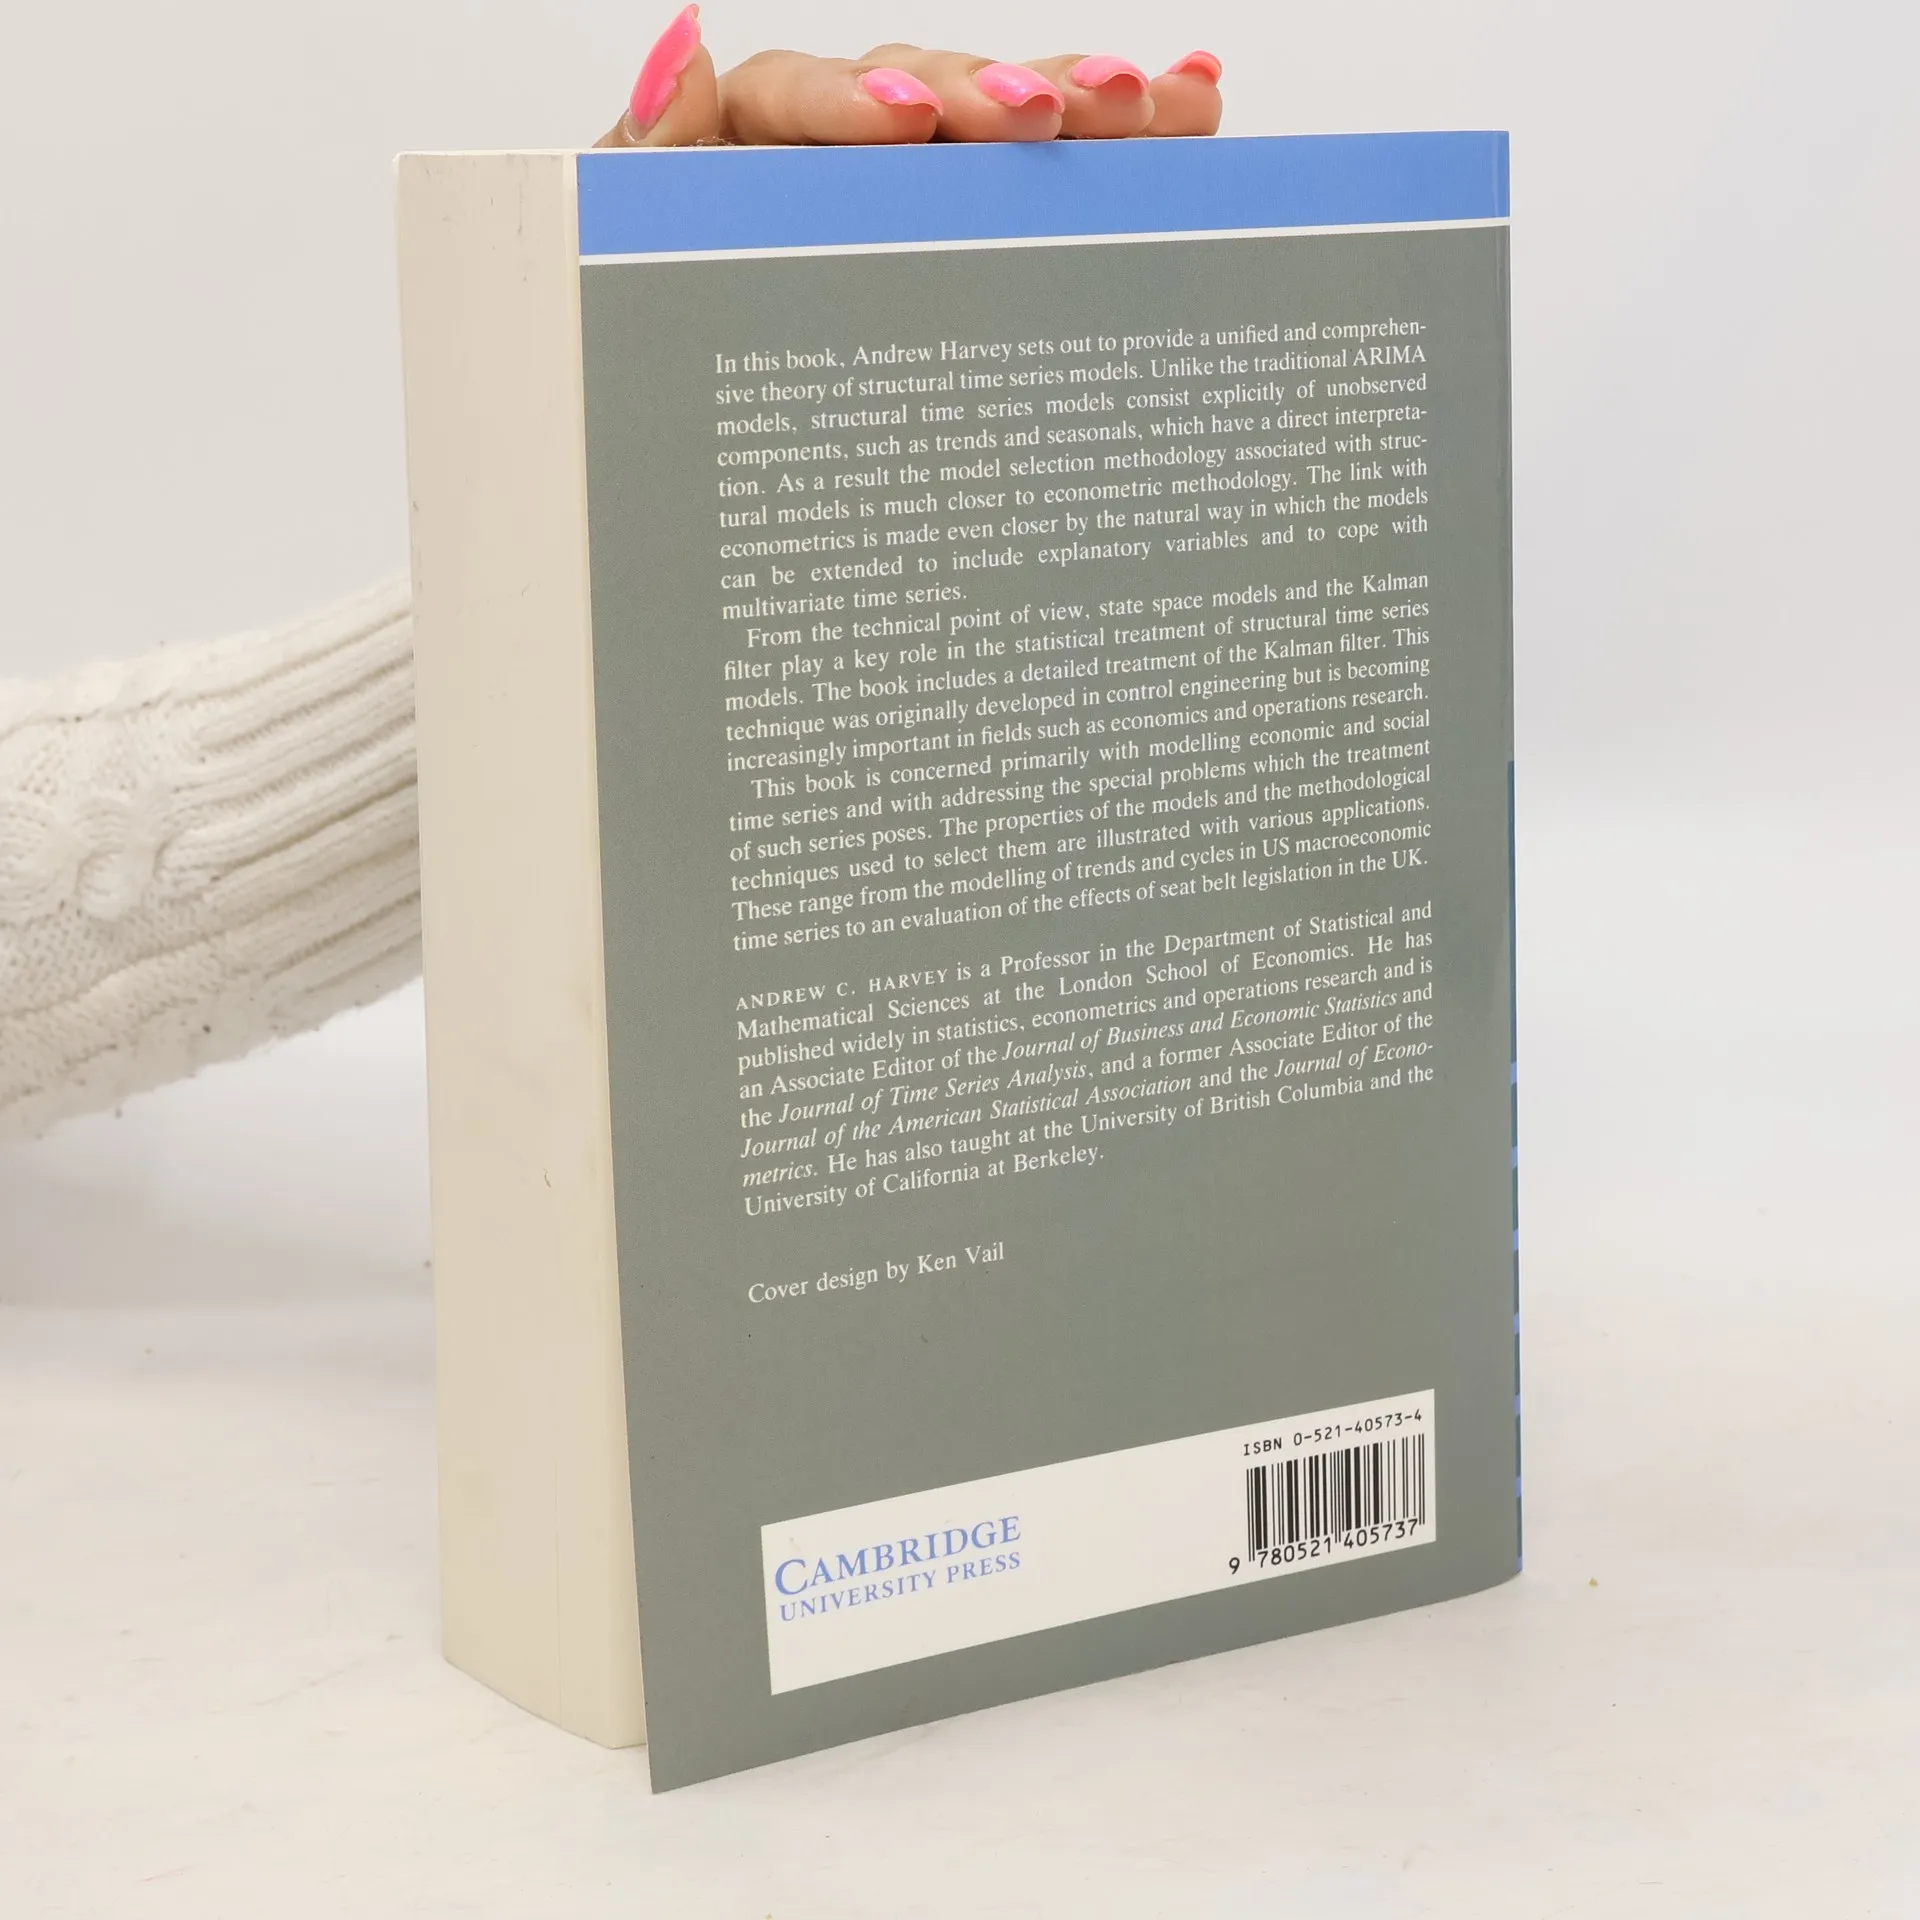
This book provides a synthesis of concepts and materials that ordinarily appear separately in time series and econometrics literature, presenting a comprehensive review of both theoretical and applied concepts. Perhaps the most novel feature of the book is its use of Kalman filtering together with econometric and time series methodology. From a technical point of view, state space models and the Kalman filter play a key role in the statistical treatment of structural time series models. This technique was originally developed in control engineering but is becoming increasingly important in economics and operations research. The book is primarily concerned with modeling economic and social time series and with addressing the special problems that the treatment of such series pose.
Zakup książki
Forecasting, structural time series models and the Kalman filter, Andrew C. Harvey
- Język

- Rok wydania
- 1990
- Oprawa
- (miękka)
Metody płatności
Brakuje nam tutaj Twojej recenzji.
- Tytuł
- Forecasting, structural time series models and the Kalman filter
- Język
- angielski
- Autorzy
- Andrew C. Harvey
- Rok wydania
- 1990
- Oprawa
- miękka
- ISBN10
- 0521405734
- ISBN13
- 9780521405737
- Seria
- Kategorie
- Tagi
- Biznes
- Ocena
- 4,1 z 5
- Opis
- This book provides a synthesis of concepts and materials that ordinarily appear separately in time series and econometrics literature, presenting a comprehensive review of both theoretical and applied concepts. Perhaps the most novel feature of the book is its use of Kalman filtering together with econometric and time series methodology. From a technical point of view, state space models and the Kalman filter play a key role in the statistical treatment of structural time series models. This technique was originally developed in control engineering but is becoming increasingly important in economics and operations research. The book is primarily concerned with modeling economic and social time series and with addressing the special problems that the treatment of such series pose.