

Parametry
- 544 strony
- 20 godzin czytania
Więcej o książce
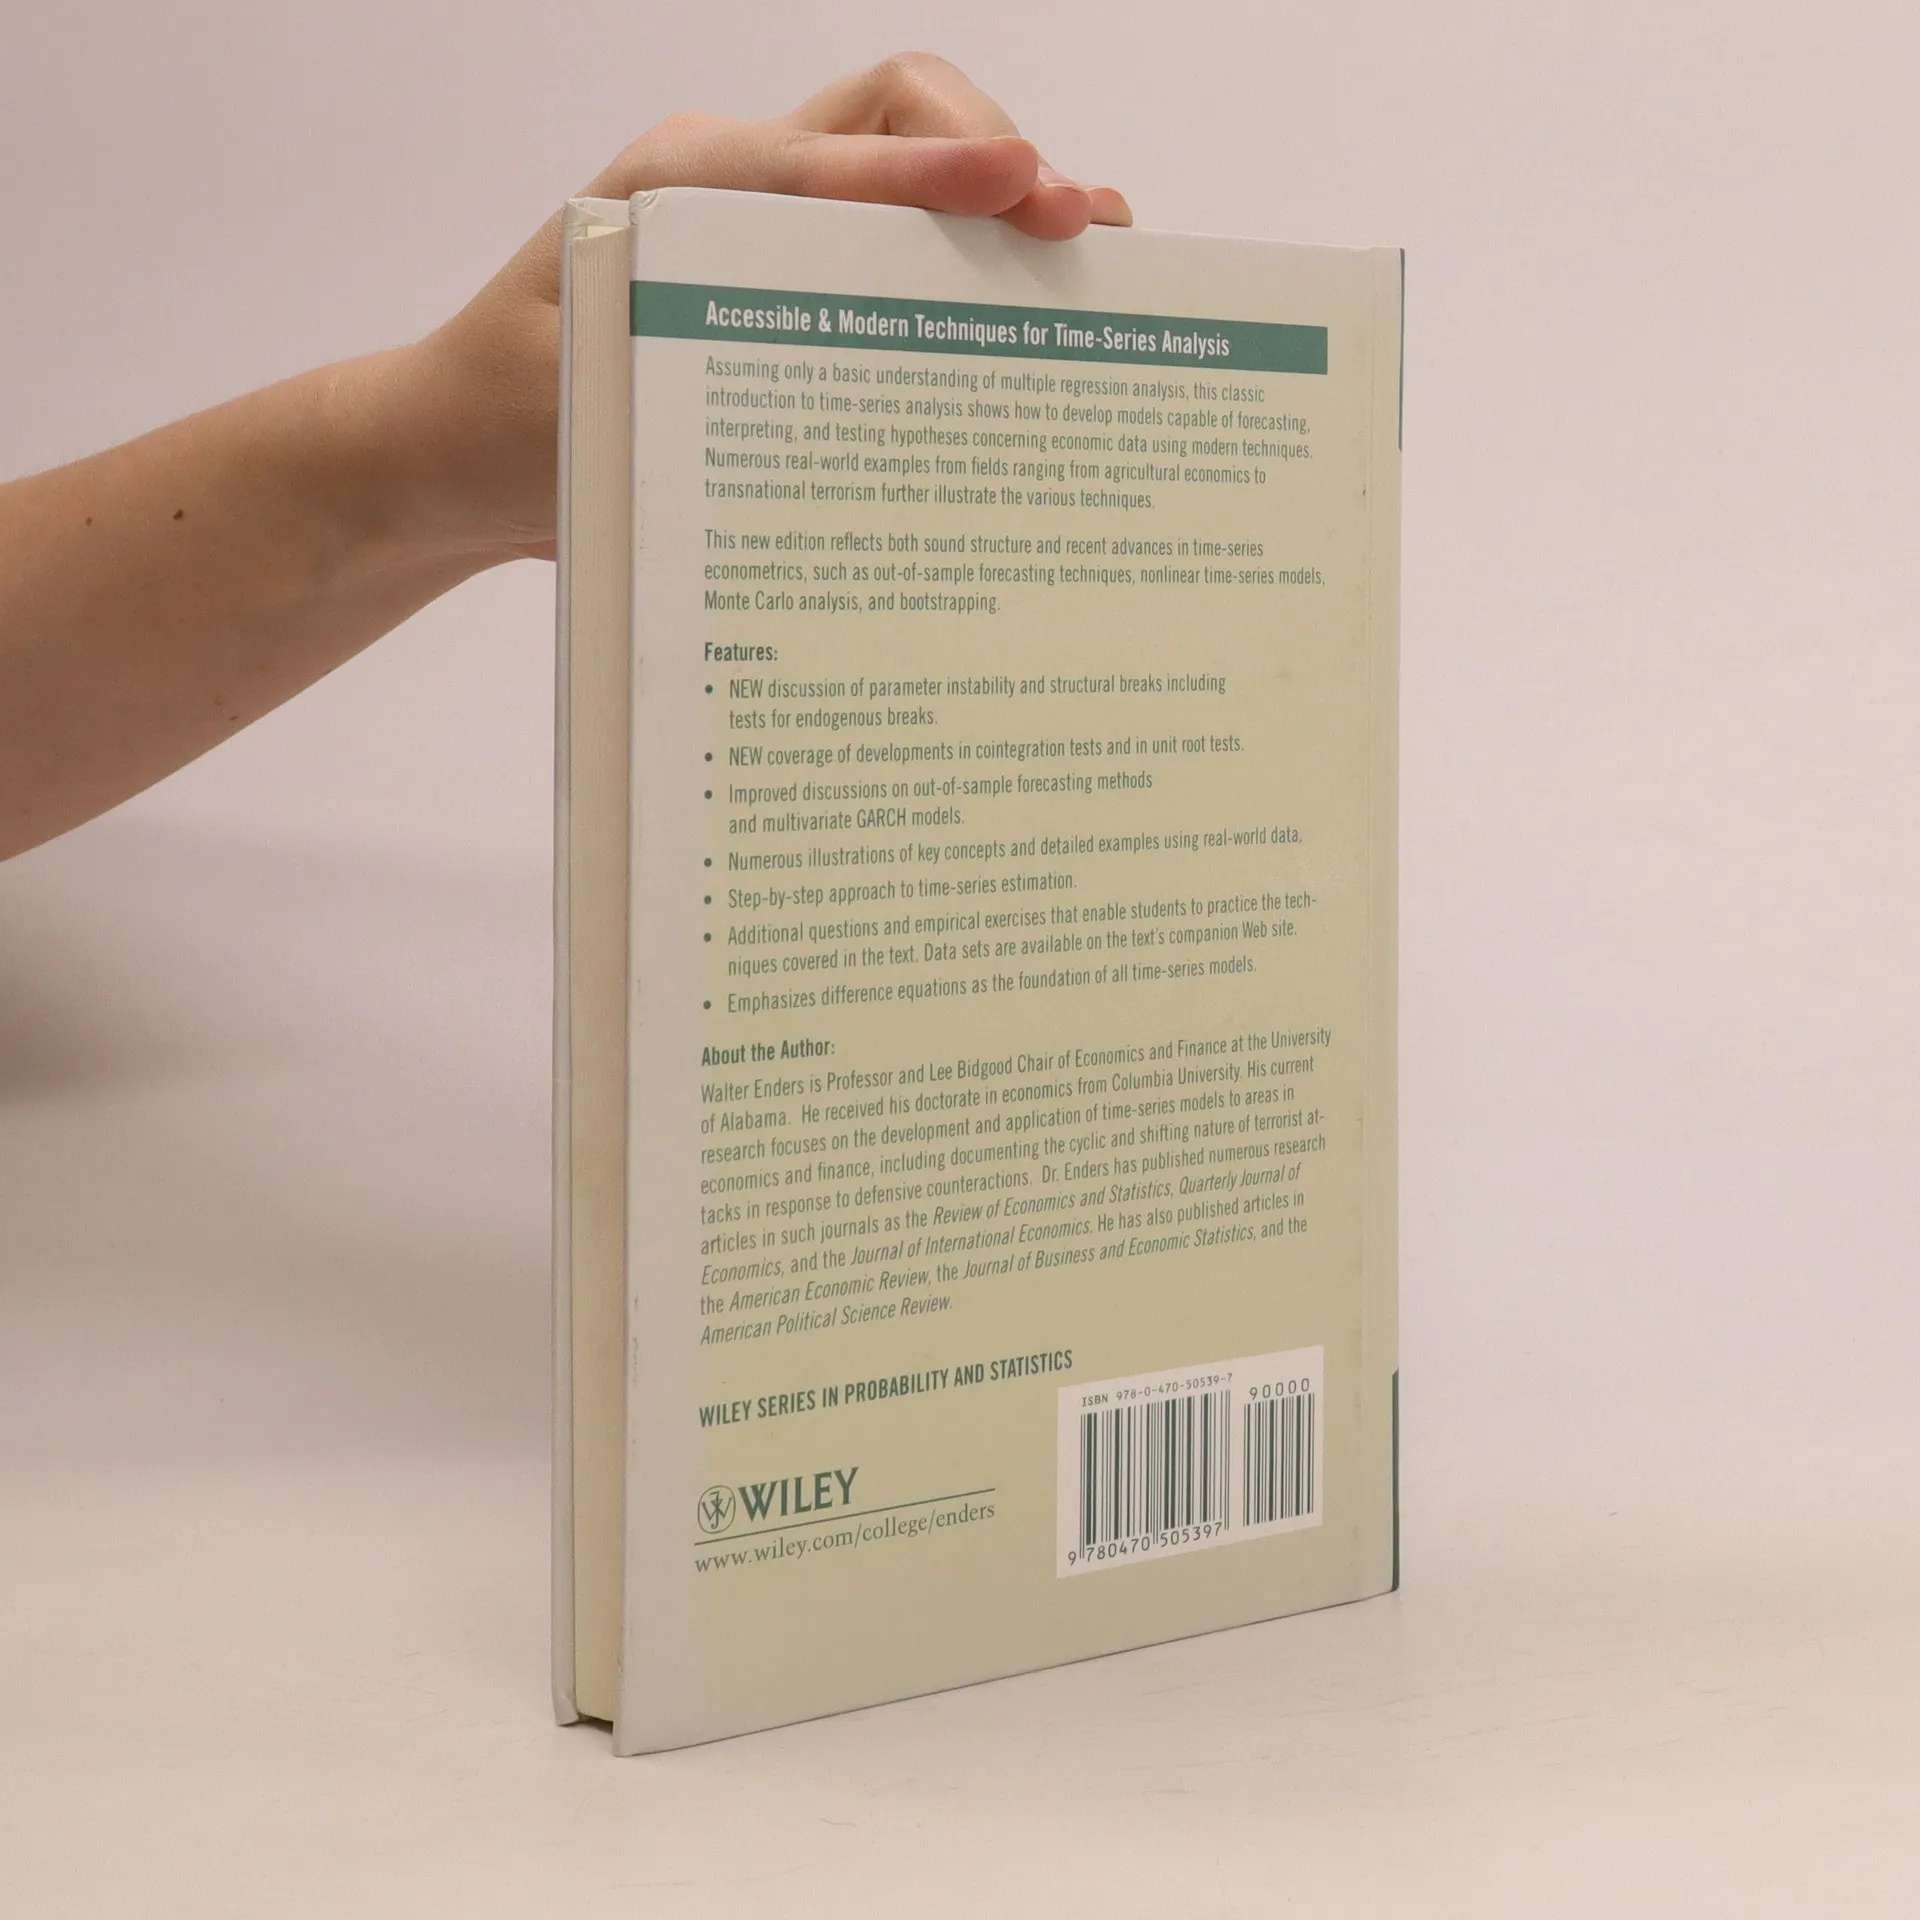
Enders continues to provide business professionals with an accessible introduction to time-series analysis. He clearly shows them how to develop models capable of forecasting, interpreting, and testing hypotheses concerning economic data using the latest techniques. The third edition includes new discussions on parameter instability and structural breaks as well as out-of-sample forecasting methods. New developments in unit root test and cointegration tests are covered. Multivariate GARCH models are also presented. In addition, several statistical examples have been updated with real-world data to help business professionals understand the relevance of the material.
Zakup książki
Applied Econometric Time Series, Walter Enders
- Język

- Rok wydania
- 2010
- Oprawa
- (twarda)
Metody płatności
Brakuje nam tutaj Twojej recenzji.
- Tytuł
- Applied Econometric Time Series
- Język
- angielski
- Autorzy
- Walter Enders
- Wydawca
- WILEY
- Rok wydania
- 2010
- Oprawa
- twarda
- Liczba stron
- 544
- ISBN10
- 0470505397
- ISBN13
- 9780470505397
- Seria
- Ocena
- 3,65 z 5
- Opis
- Enders continues to provide business professionals with an accessible introduction to time-series analysis. He clearly shows them how to develop models capable of forecasting, interpreting, and testing hypotheses concerning economic data using the latest techniques. The third edition includes new discussions on parameter instability and structural breaks as well as out-of-sample forecasting methods. New developments in unit root test and cointegration tests are covered. Multivariate GARCH models are also presented. In addition, several statistical examples have been updated with real-world data to help business professionals understand the relevance of the material.