

Więcej o książce
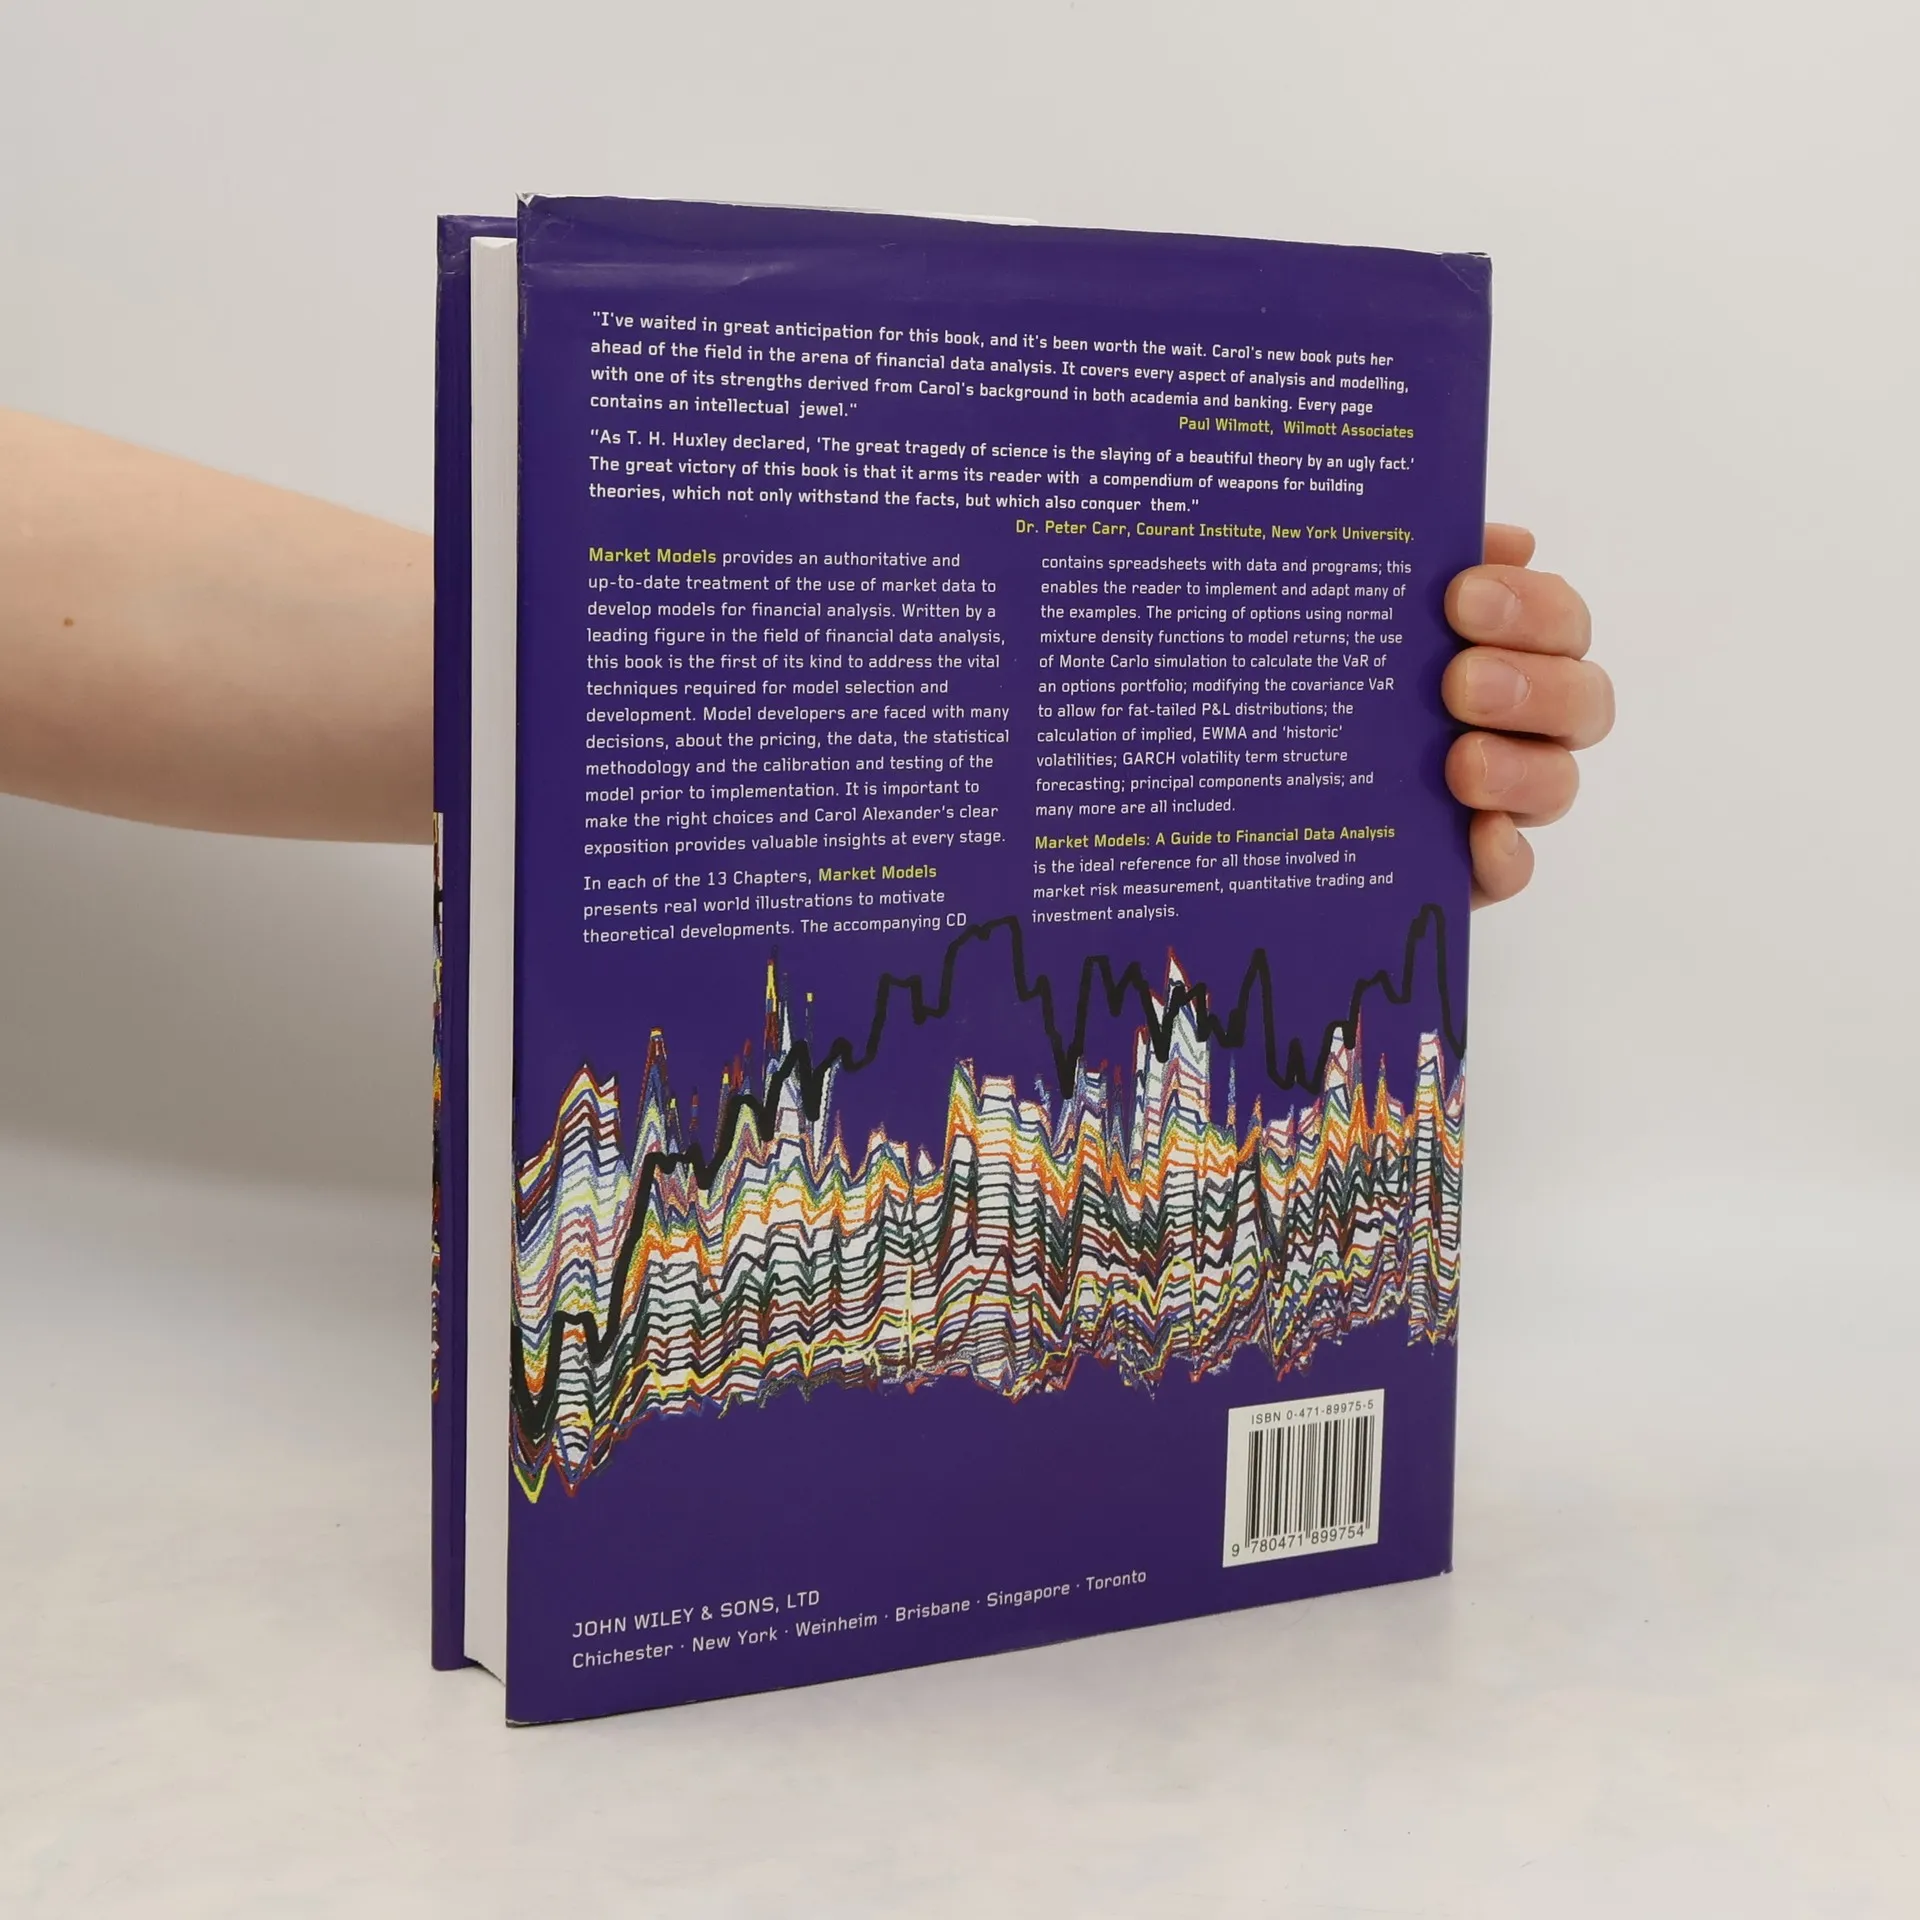
In part 1, Carol Alexander brings many new insights to the pricing and hedging of options with her understanding of volatility and correlation, and the uncertainty which surrounds these key determinants of option portfolio risk. Modelling the market risk of portfolios is covered in part 2 where the main focus is on a linear algebraic approach; the covariance matrix and principal component analysis are developed as key tools for the analysis of financial systems. The traditional time series econometric approach is explained in part 3, with coverage ranging from the application cointegration to long-short equity hedge funds, to high-frequency data prediction using neural networks and nearest neighbour algorithms . Throughout this text the emphasis is on understanding concepts and implementing solutions. It has been designed to be accessible to a very wide audience: the coverage is comprehensive and complete and the technical appendix makes the book largely self-contained.
Zakup książki
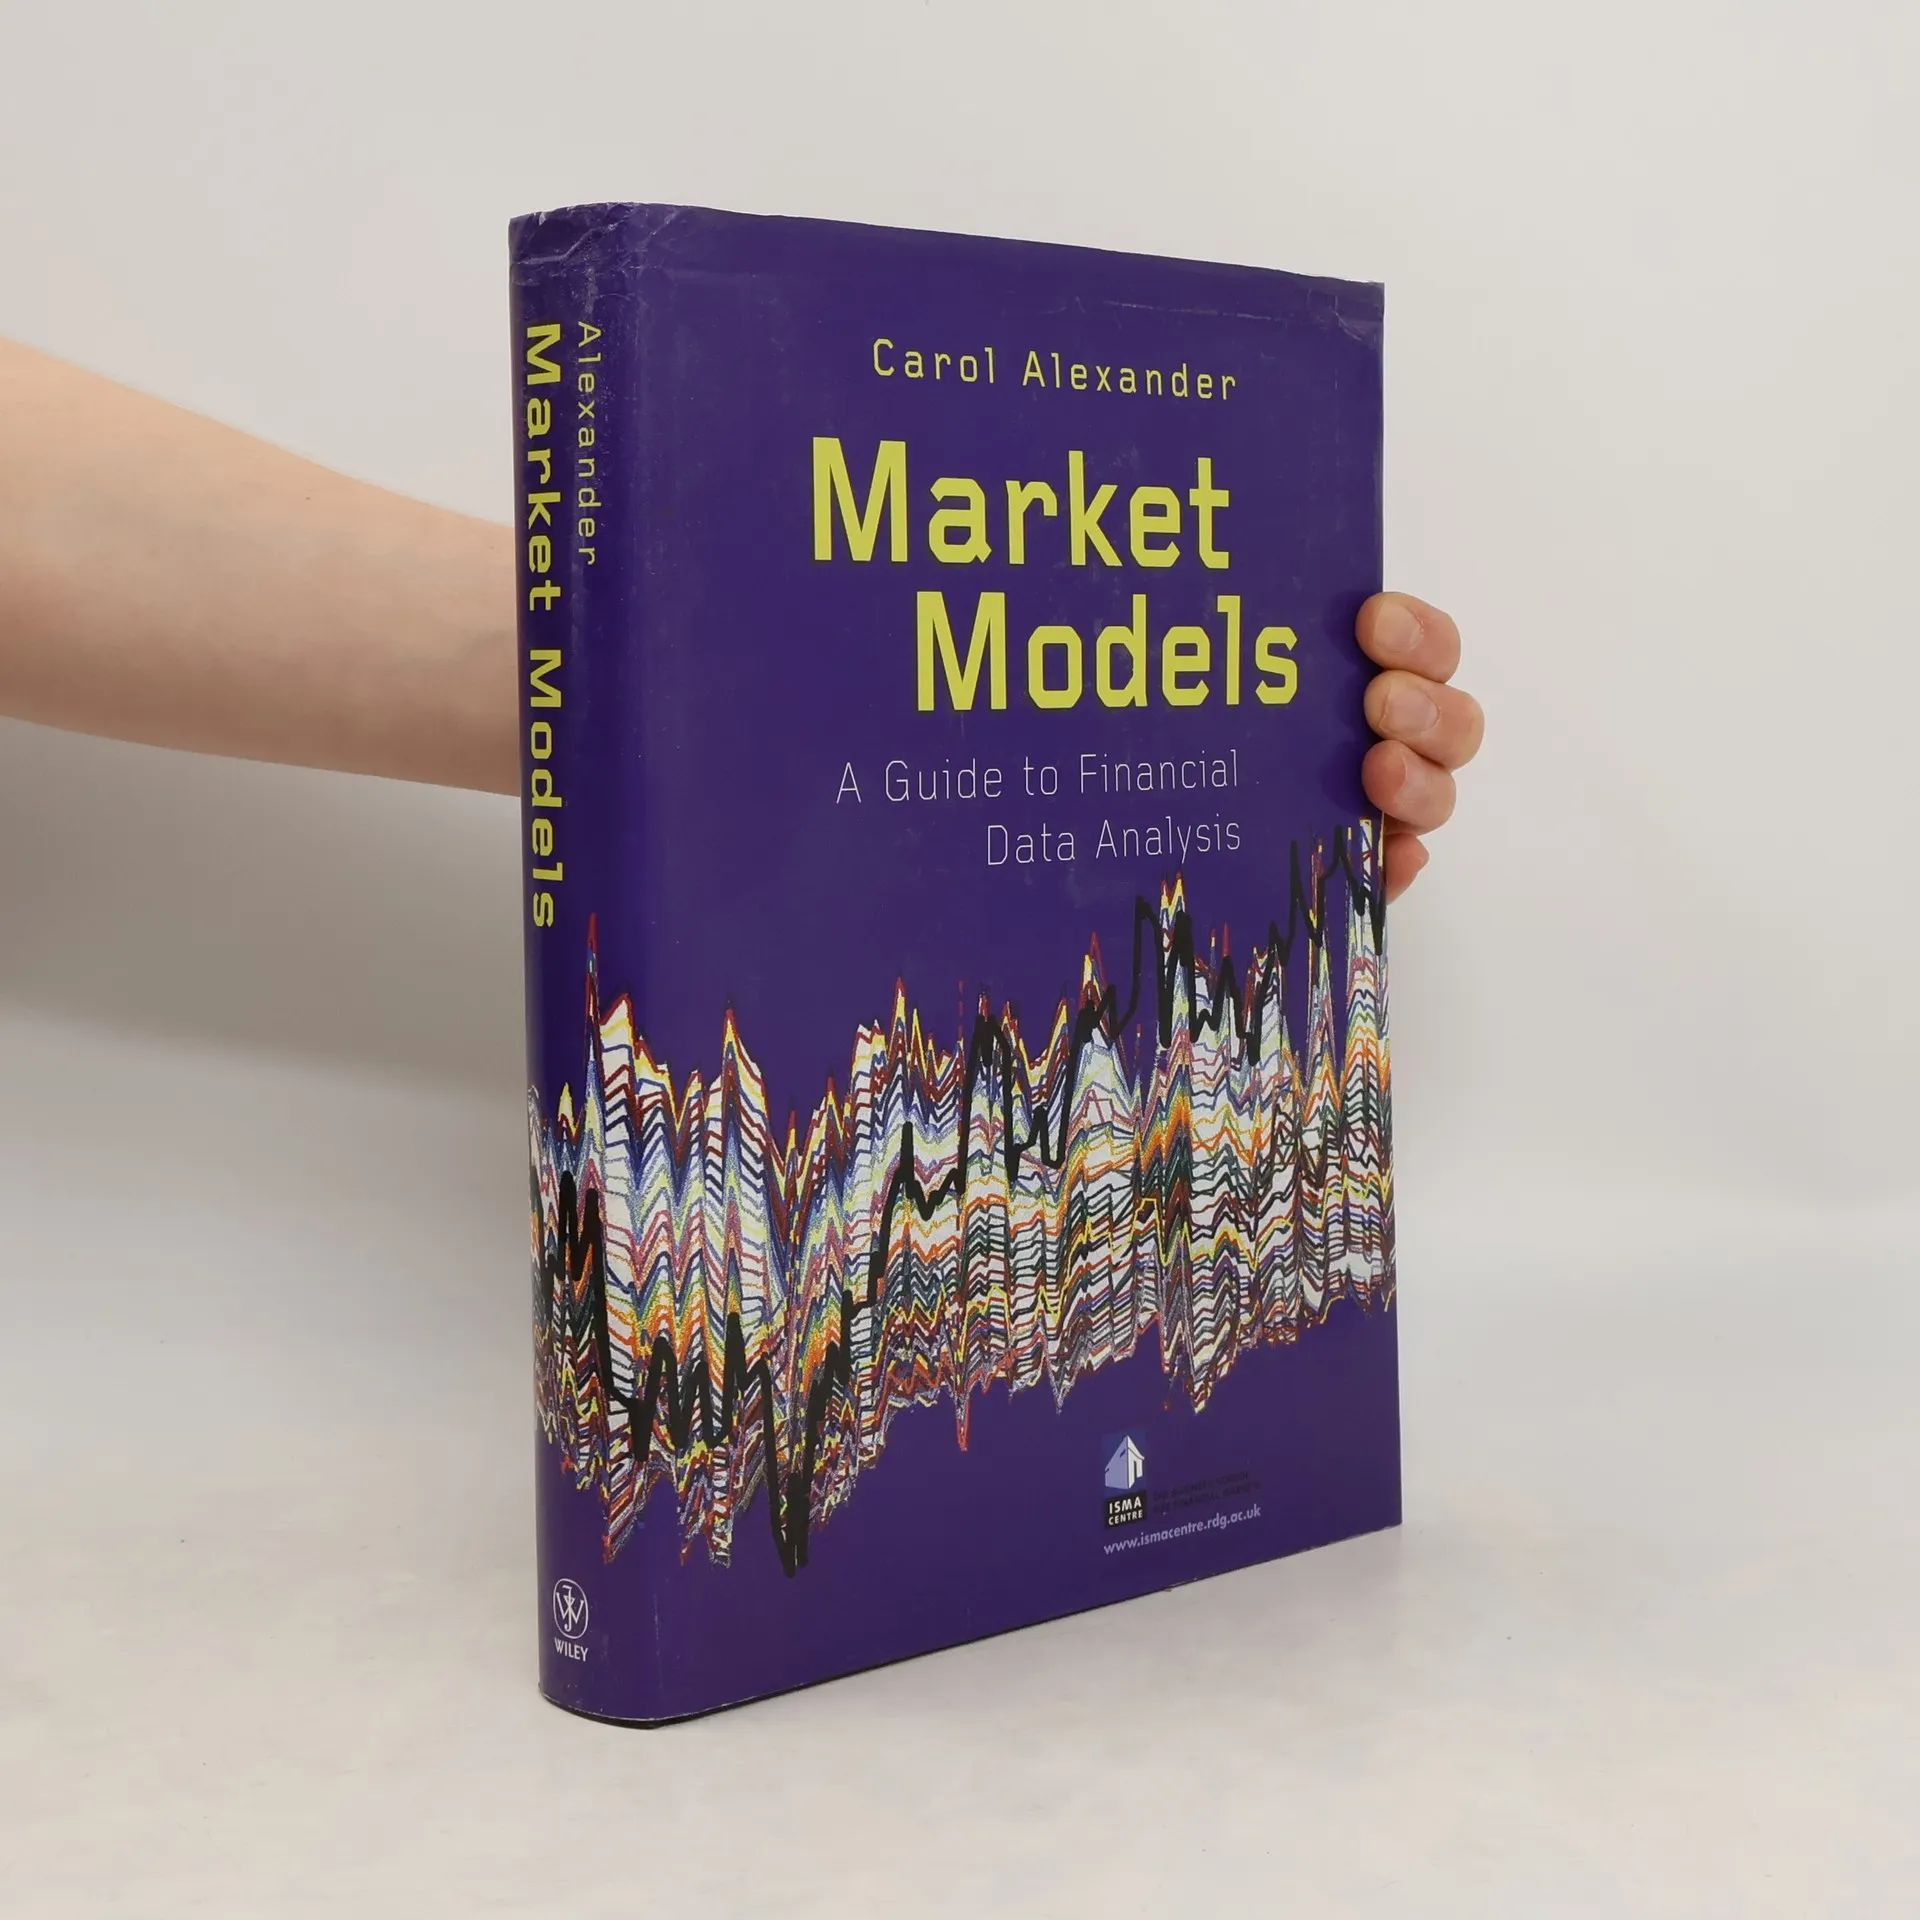
Market Models. A Guide to Financial Data Analysis, Carol Alexander
- Język

- Rok wydania
- 2001
- Oprawa
- (twarda)
Metody płatności
Brakuje nam tutaj Twojej recenzji.
- Tytuł
- Market Models. A Guide to Financial Data Analysis
- Język
- angielski
- Autorzy
- Carol Alexander
- Wydawca
- WILEY
- Rok wydania
- 2001
- Oprawa
- twarda
- Liczba stron
- 445
- ISBN10
- 0471899755
- ISBN13
- 9780471899754
- Seria
- Ocena
- 3,75 z 5
- Opis
- In part 1, Carol Alexander brings many new insights to the pricing and hedging of options with her understanding of volatility and correlation, and the uncertainty which surrounds these key determinants of option portfolio risk. Modelling the market risk of portfolios is covered in part 2 where the main focus is on a linear algebraic approach; the covariance matrix and principal component analysis are developed as key tools for the analysis of financial systems. The traditional time series econometric approach is explained in part 3, with coverage ranging from the application cointegration to long-short equity hedge funds, to high-frequency data prediction using neural networks and nearest neighbour algorithms . Throughout this text the emphasis is on understanding concepts and implementing solutions. It has been designed to be accessible to a very wide audience: the coverage is comprehensive and complete and the technical appendix makes the book largely self-contained.