

Parametry
Więcej o książce
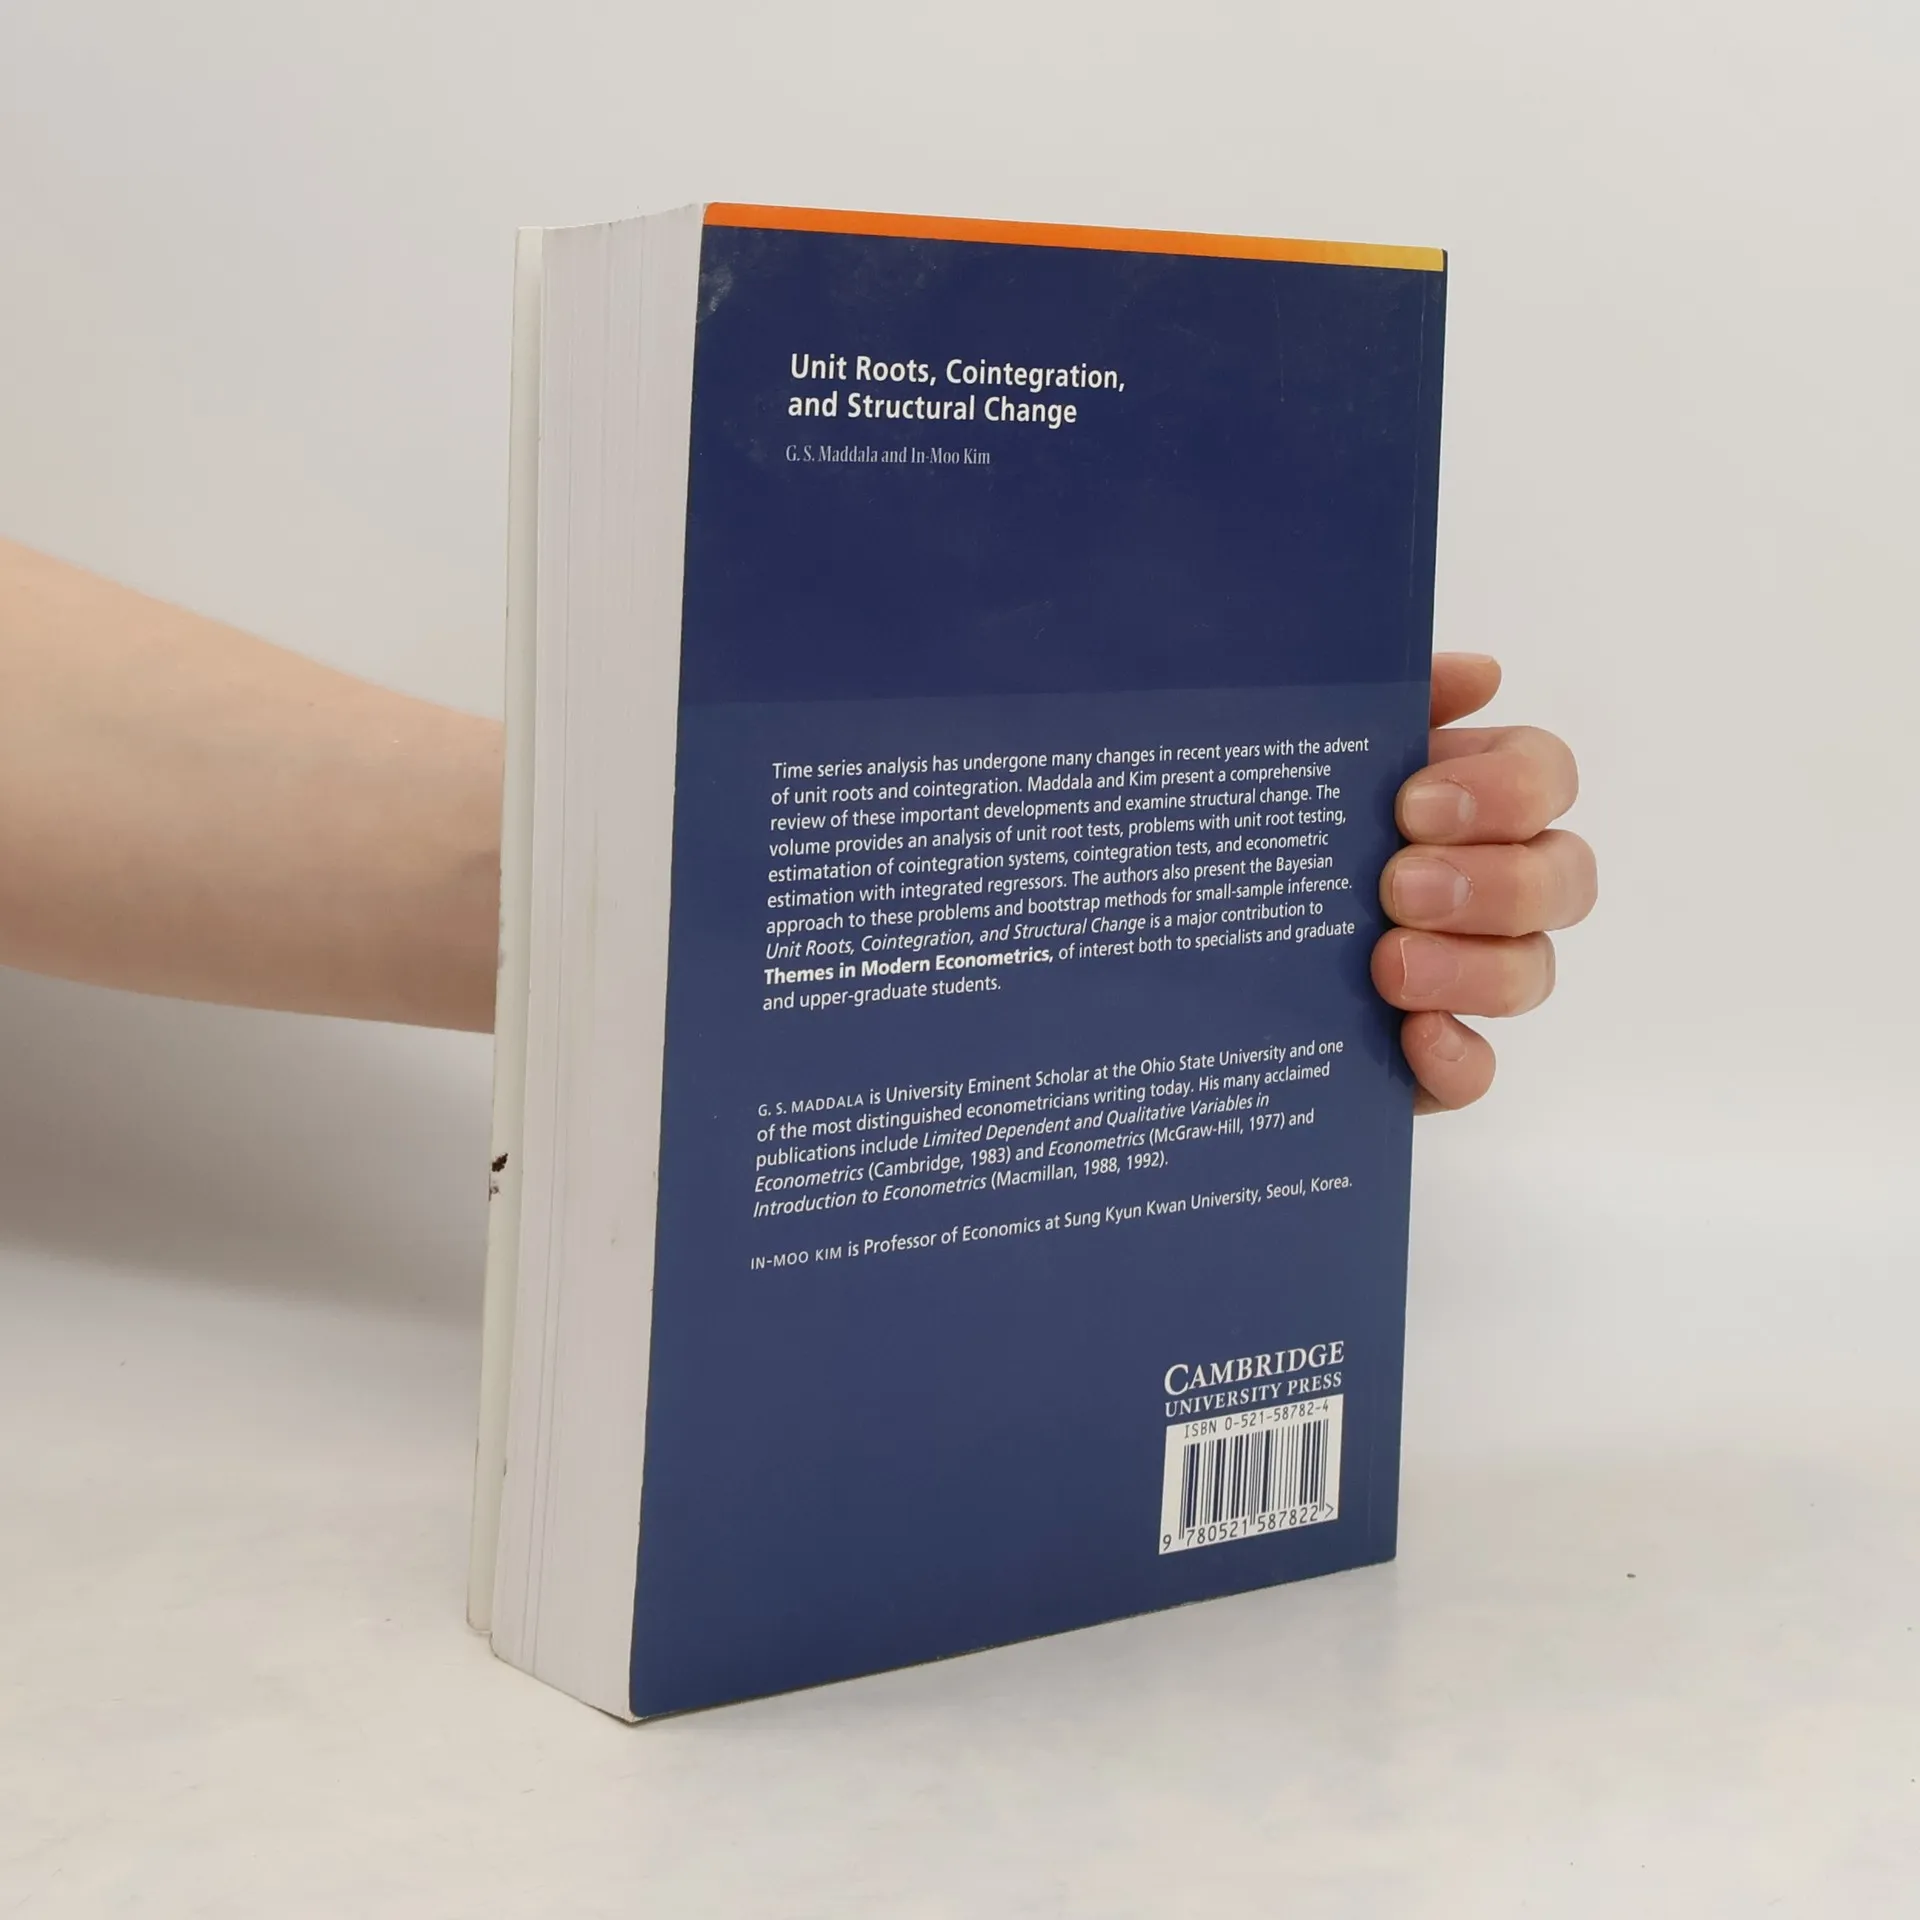
Time series analysis has undergone many changes in recent years with the advent of unit roots and cointegration. Maddala and Kim present a comprehensive review of these important developments and examine structural change. The volume provides an analysis of unit root tests, problems with unit root testing, estimation of cointegration systems, cointegration tests, and econometric estimation with integrated regressors. The authors also present the Bayesian approach to these problems and bootstrap methods for small-sample inference. The chapters on structural change discuss the problems of unit root tests and cointegration under structural change, outliers and robust methods, the Markov-switching model and Harvey's structural time series model. Unit Roots, Cointegration and Structural Change is a major contribution to Themes in Modern Econometrics, of interest both to specialists and graduate and upper-undergraduate students.
Zakup książki
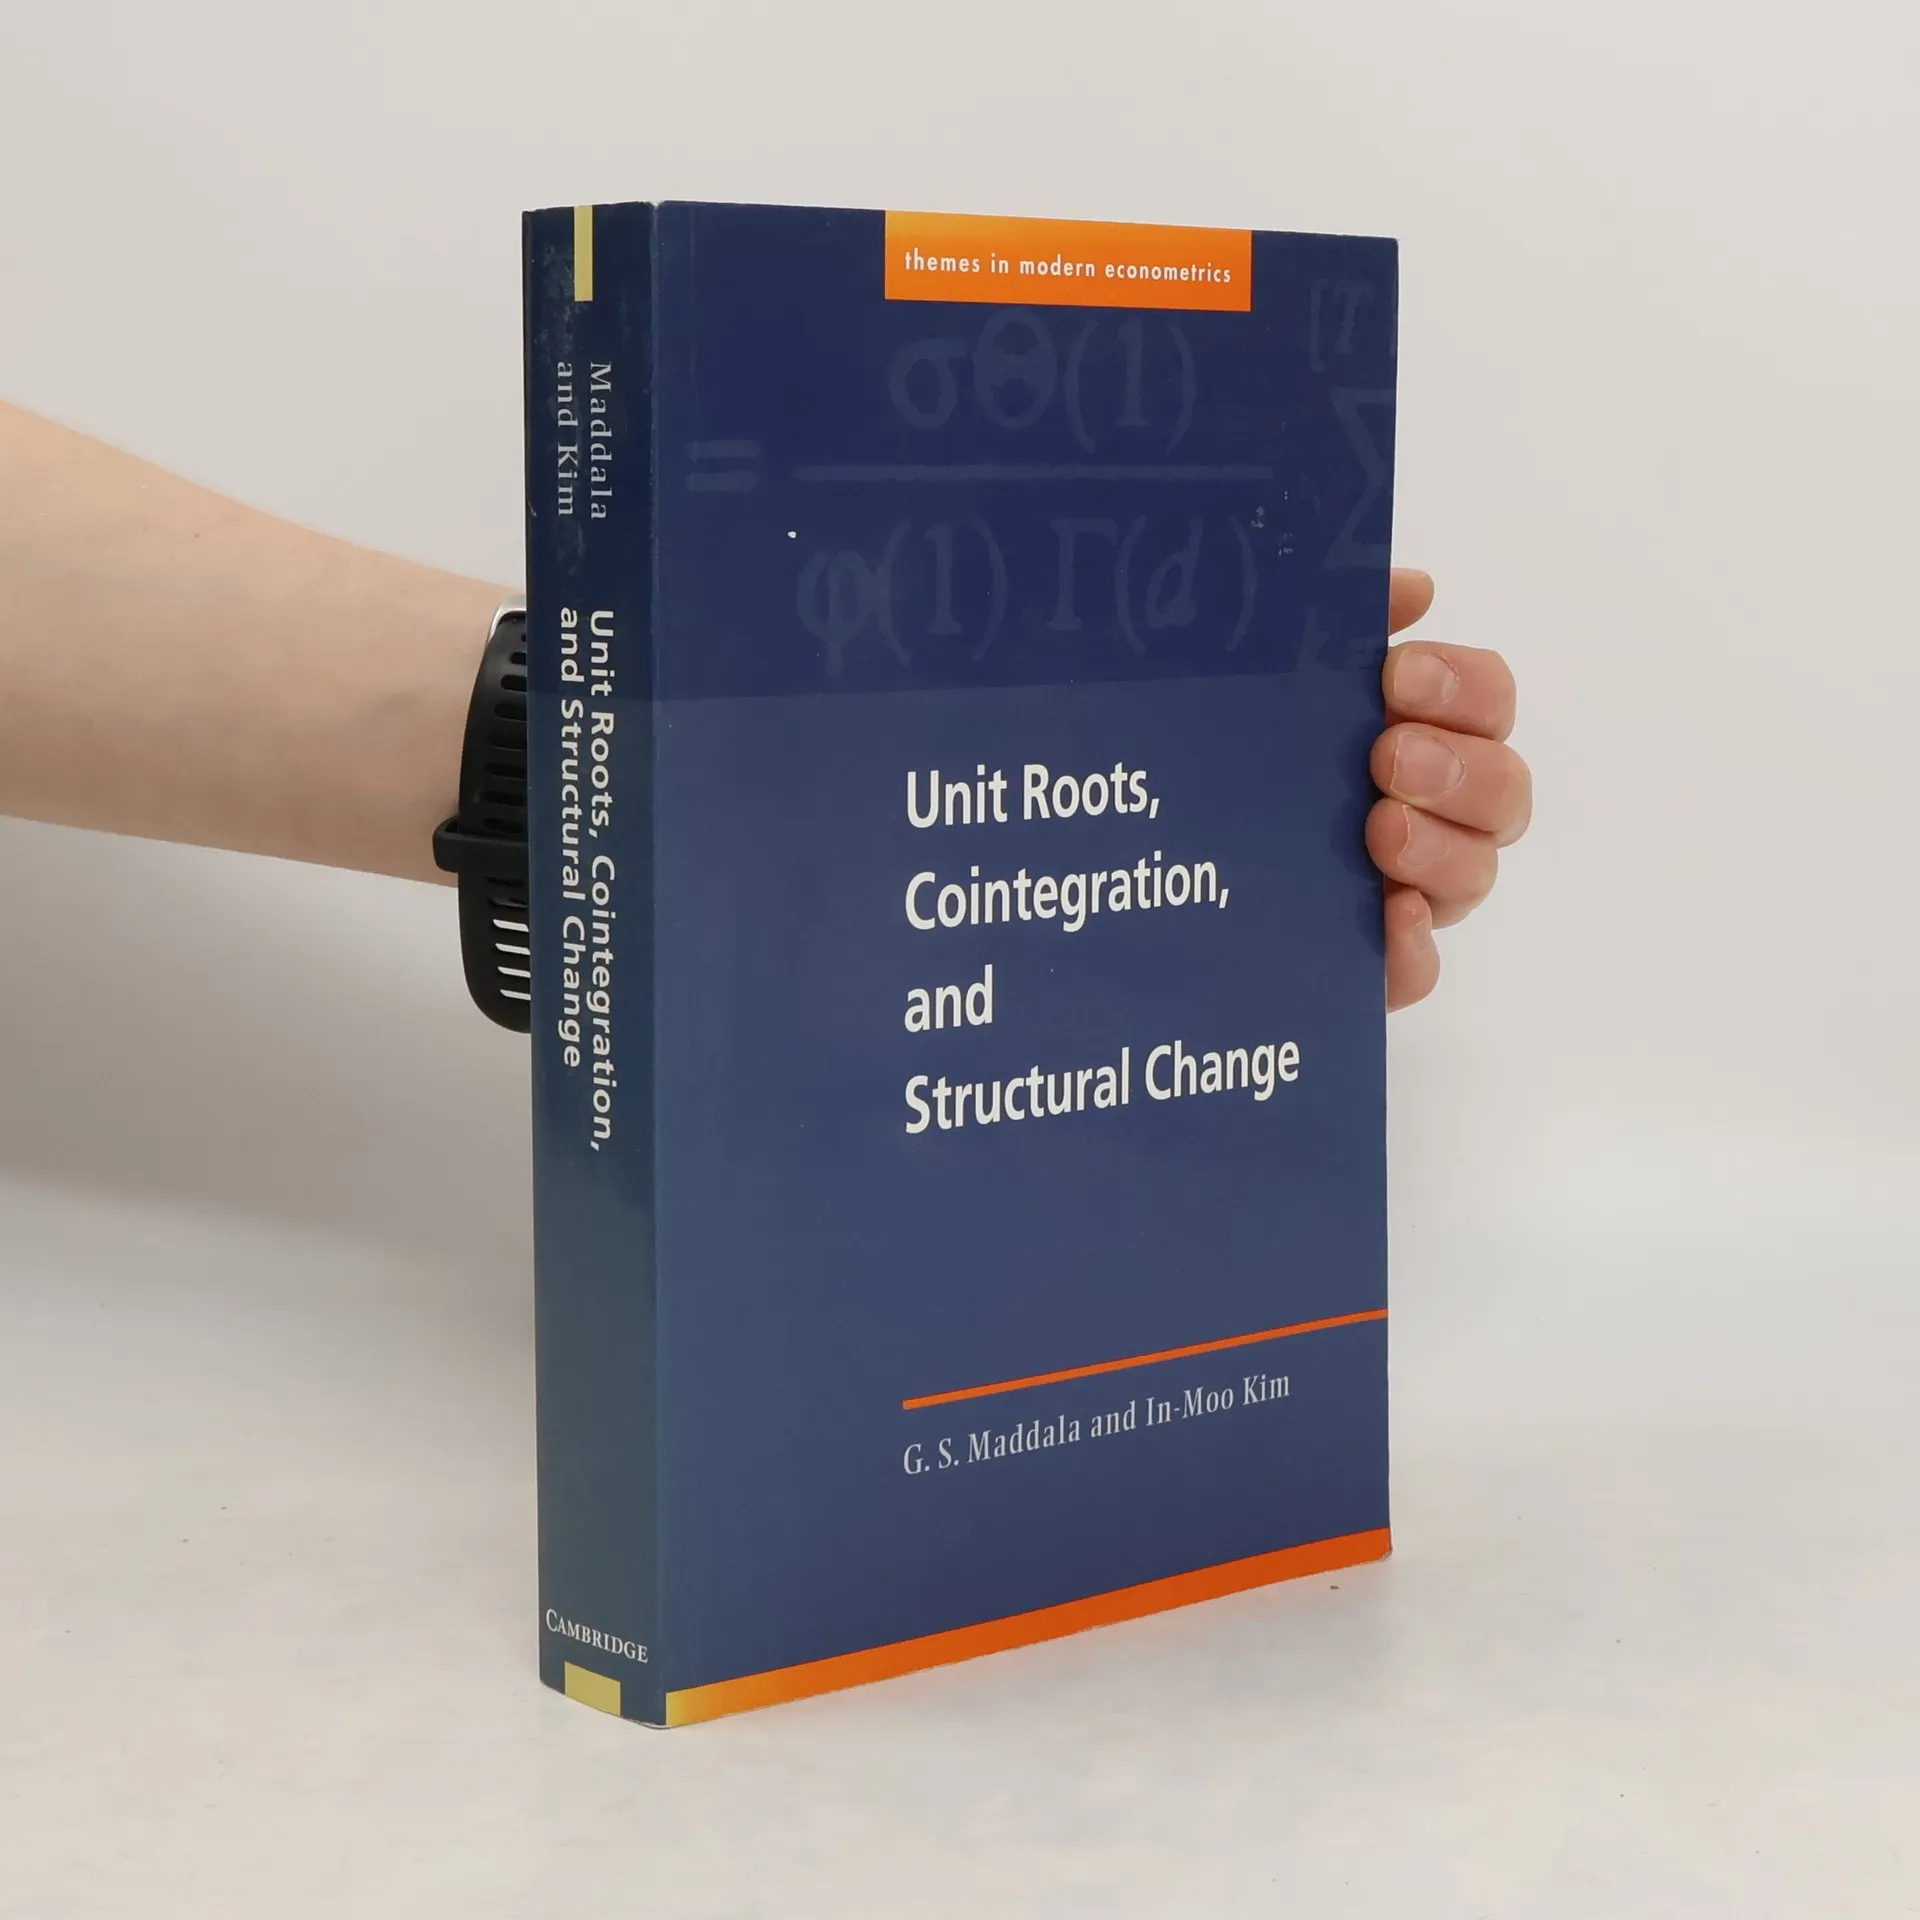
Unit Roots, Cointegration, and Structural Change, G.S. Maddala, In-Moo Kim
- Język

- Rok wydania
- 1998
- Oprawa
- (miękka)
Metody płatności
Brakuje nam tutaj Twojej recenzji.
- Tytuł
- Unit Roots, Cointegration, and Structural Change
- Język
- angielski
- Autorzy
- G.S. Maddala, In-Moo Kim
- Wydawca
- Cambridge University Press
- Rok wydania
- 1998
- Oprawa
- miękka
- ISBN10
- 0521587824
- ISBN13
- 9780521587822
- Tagi
- Ocena
- 4,25 z 5
- Opis
- Time series analysis has undergone many changes in recent years with the advent of unit roots and cointegration. Maddala and Kim present a comprehensive review of these important developments and examine structural change. The volume provides an analysis of unit root tests, problems with unit root testing, estimation of cointegration systems, cointegration tests, and econometric estimation with integrated regressors. The authors also present the Bayesian approach to these problems and bootstrap methods for small-sample inference. The chapters on structural change discuss the problems of unit root tests and cointegration under structural change, outliers and robust methods, the Markov-switching model and Harvey's structural time series model. Unit Roots, Cointegration and Structural Change is a major contribution to Themes in Modern Econometrics, of interest both to specialists and graduate and upper-undergraduate students.