

Więcej o książce
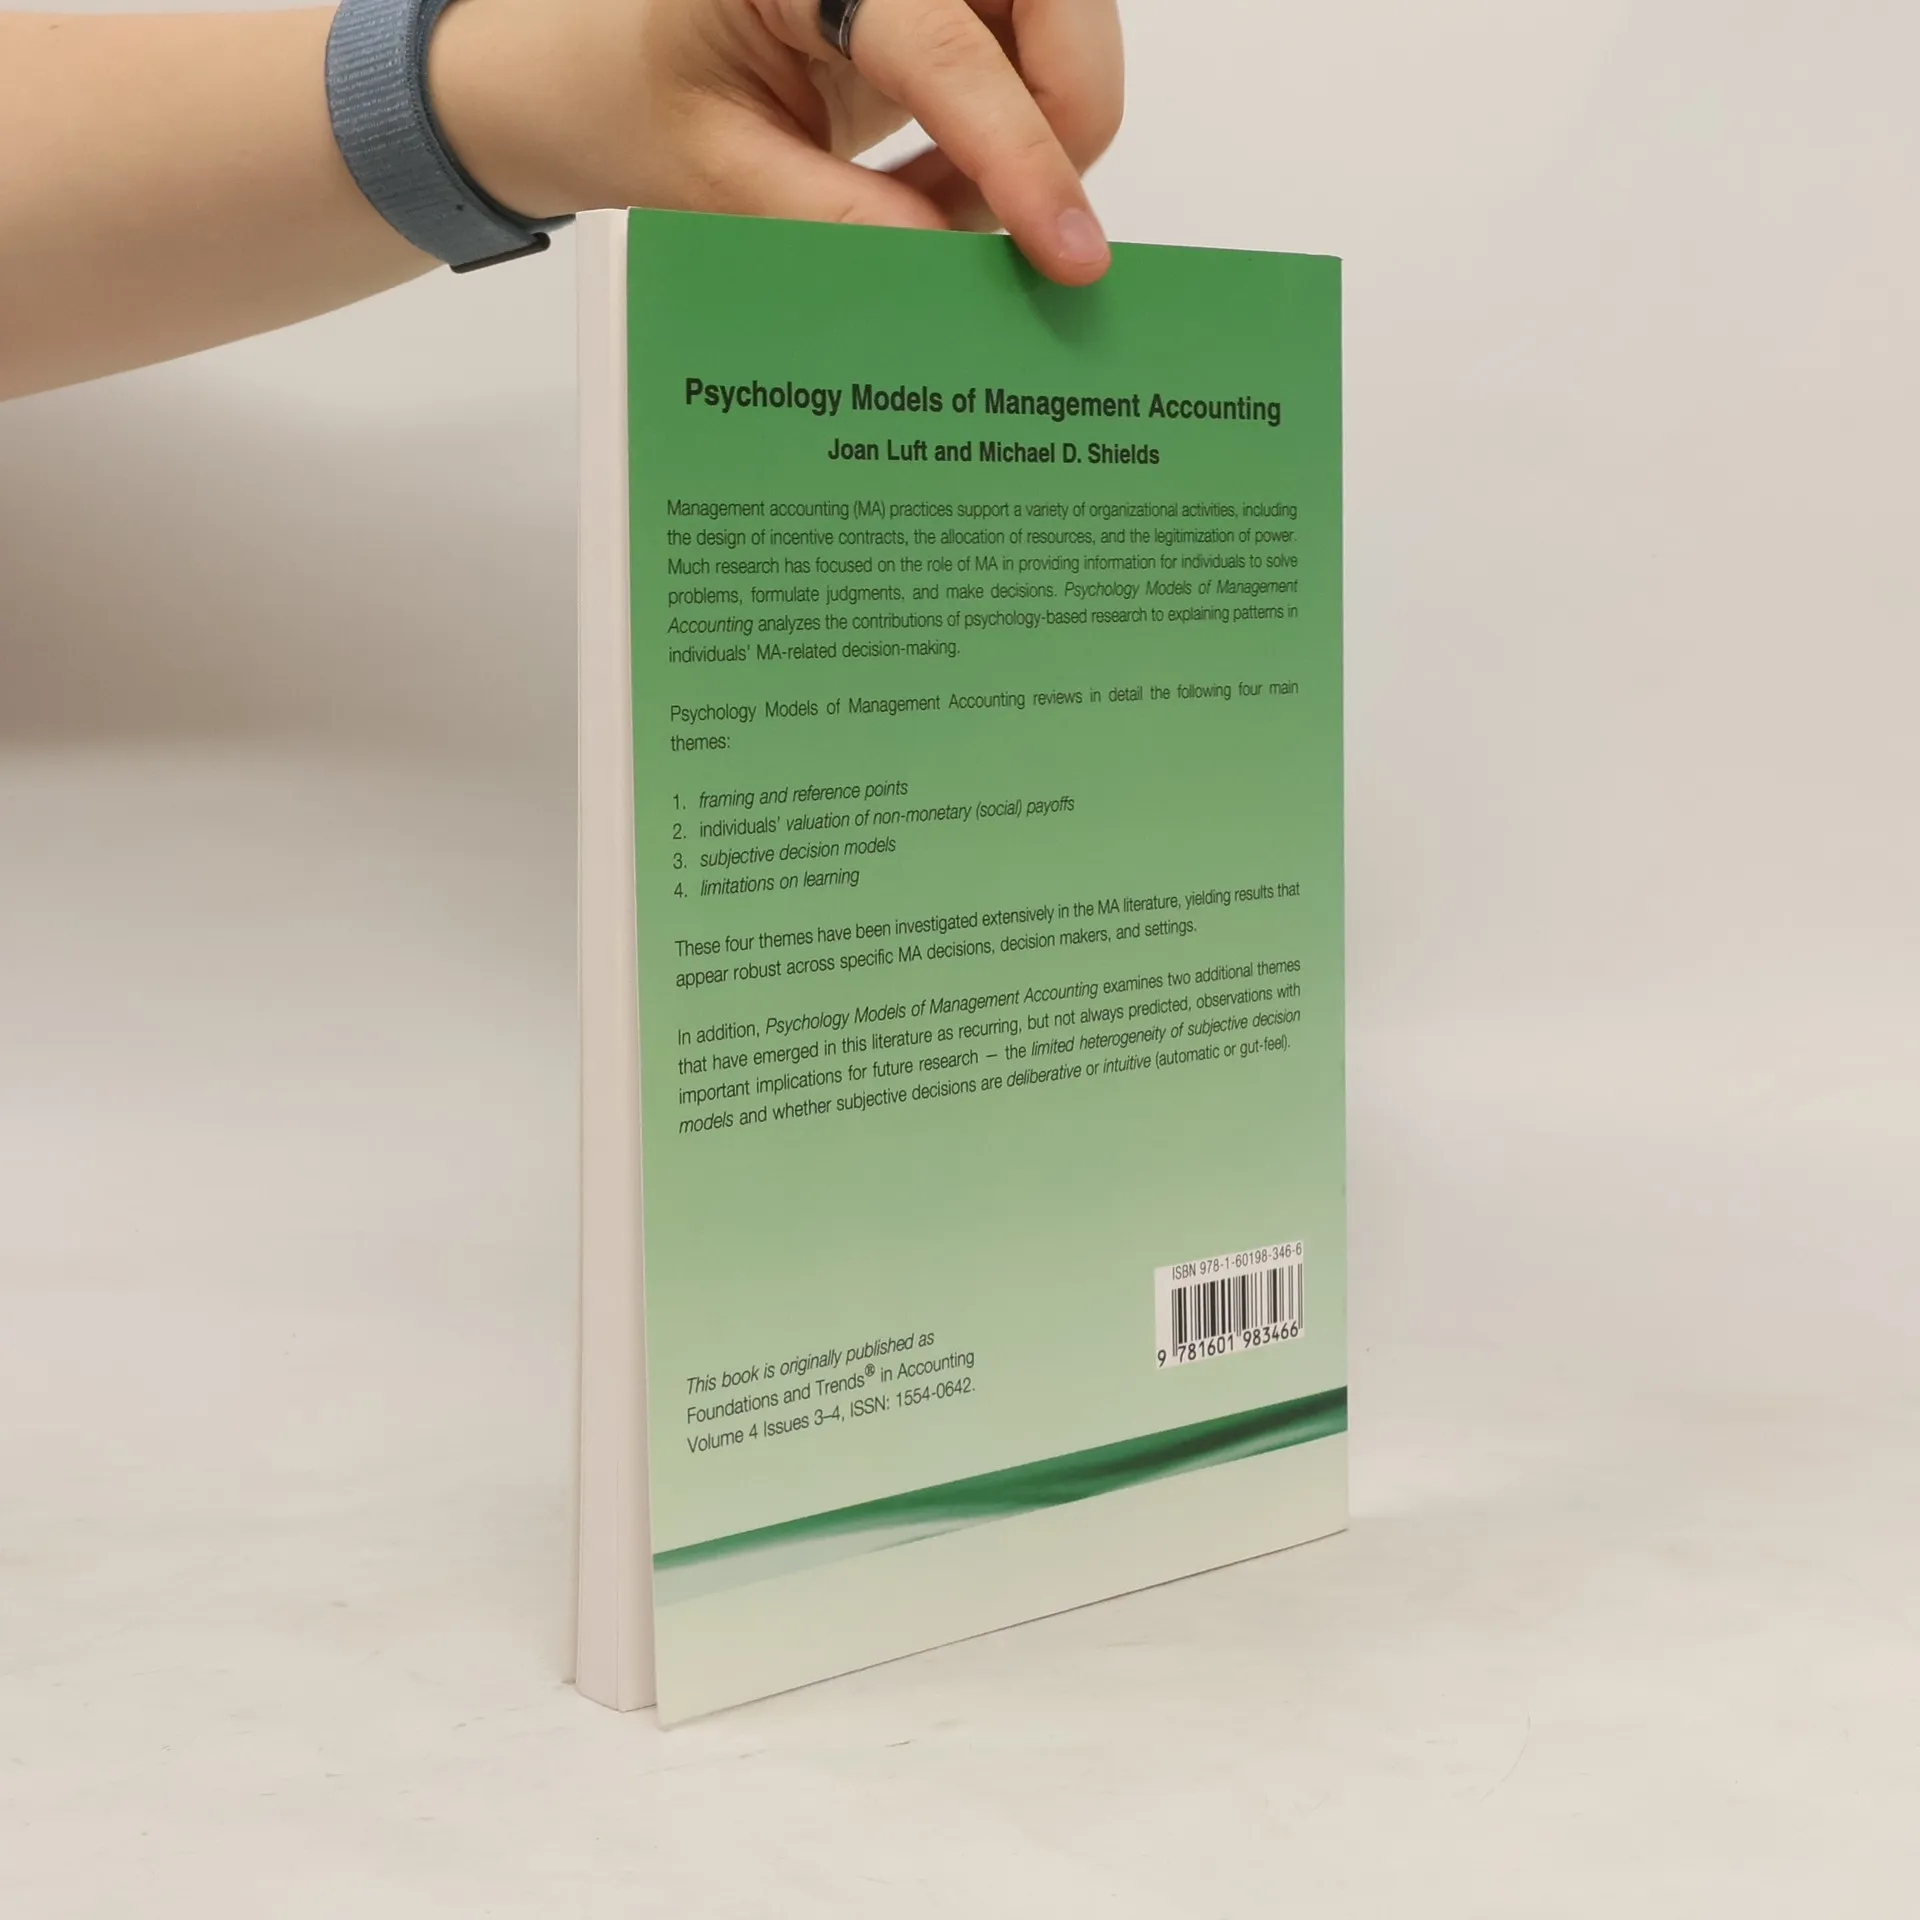
Management accounting (MA) practices support a variety of organizational activities, including the design of incentive contracts, the allocation of resources, and the legitimization of power. Much research has focused on the role of MA in providing information for individuals to solve problems, formulate judgments, and make decisions. Psychology Models of Management Accounting analyzes the contributions of psychology-based research to explaining patterns in individuals' MA-related decision-making. Psychology Models of Management Accounting reviews in detail the following four main 1. framing and reference points 2. individuals' valuation of non-monetary (social) payoffs 3. subjective decision models 4. limitations on learning These four themes have been investigated extensively in the MA literature, yielding results that appear robust across specific MA decisions, decision makers, and settings. In addition, Psychology Models of Management Accounting examines two additional themes that have emerged in this literature as recurring, but not always predicted, observations with important implications for future research - the limited heterogeneity of subjective decision models and whether subjective decisions are deliberative or intuitive (automatic or gut-feel).
Zakup książki
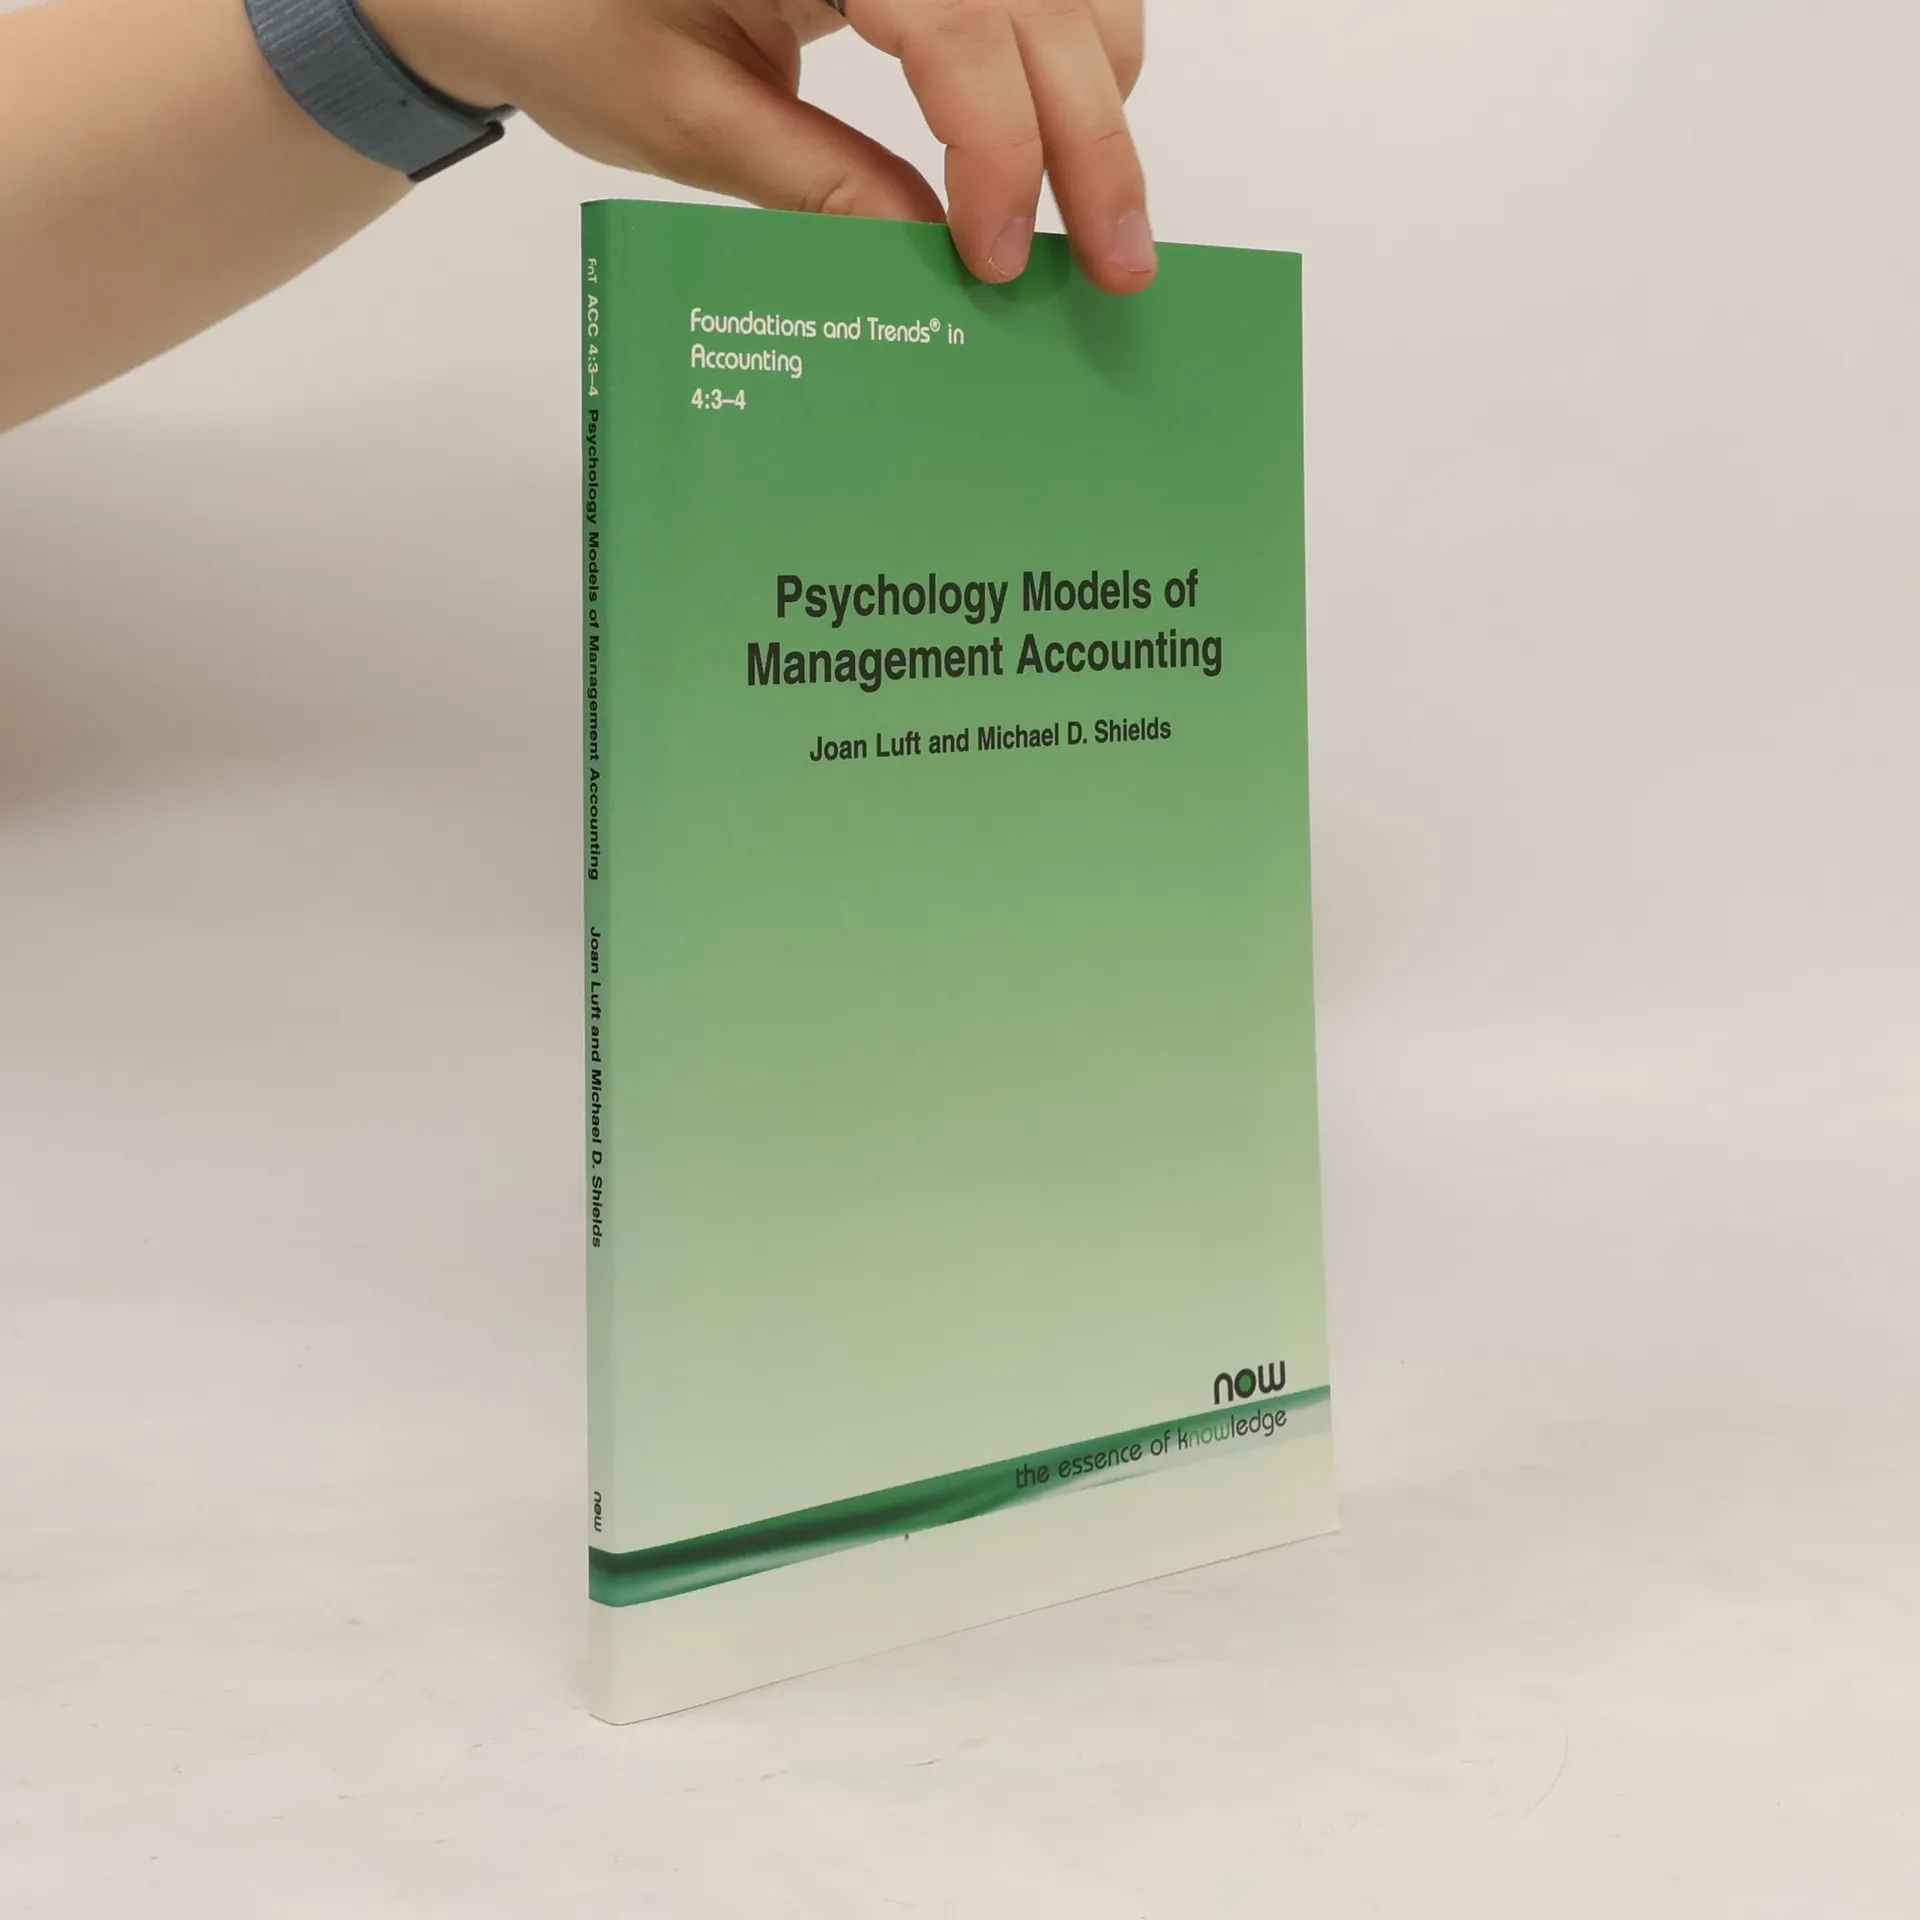
Psychology Models of Management Accounting, Joan Luft, Michael D. Shields
- Język

- Rok wydania
- 2010
- Oprawa
- (miękka)
Metody płatności
Nikt jeszcze nie ocenił.
- Tytuł
- Psychology Models of Management Accounting
- Język
- angielski
- Autorzy
- Joan Luft, Michael D. Shields
- Wydawca
- Now Publishers Inc
- Rok wydania
- 2010
- Oprawa
- miękka
- Liczba stron
- 162
- ISBN10
- 1601983468
- ISBN13
- 9781601983466
- Seria
- Tagi
- Biznes, Księgowość
- Opis
- Management accounting (MA) practices support a variety of organizational activities, including the design of incentive contracts, the allocation of resources, and the legitimization of power. Much research has focused on the role of MA in providing information for individuals to solve problems, formulate judgments, and make decisions. Psychology Models of Management Accounting analyzes the contributions of psychology-based research to explaining patterns in individuals' MA-related decision-making. Psychology Models of Management Accounting reviews in detail the following four main 1. framing and reference points 2. individuals' valuation of non-monetary (social) payoffs 3. subjective decision models 4. limitations on learning These four themes have been investigated extensively in the MA literature, yielding results that appear robust across specific MA decisions, decision makers, and settings. In addition, Psychology Models of Management Accounting examines two additional themes that have emerged in this literature as recurring, but not always predicted, observations with important implications for future research - the limited heterogeneity of subjective decision models and whether subjective decisions are deliberative or intuitive (automatic or gut-feel).