

Parametry
- 306 stron
- 11 godzin czytania
Więcej o książce
How much of a portfolio should be allocated to the stock market? This question is crucial for both institutional and individual investors. The text explores this vital investment dilemma, advocating for active management of asset allocation within a long-term passive framework. Central to this strategy is a novel approach to stock market valuation developed through the authors' experience with large institutional investors. Traditionally, active management and passive investing are seen as opposing strategies. However, the authors propose a decision-making process that challenges this notion. By using market prices as a repository of information, they identify three key measures related to business outlook, interest rates, and investor confidence that can predict stock market changes. The text provides a comprehensive blueprint for implementing active asset allocation within a long-term passive plan. It delves into how to uncover hidden information in financial markets, focus on the limited opportunities available to active managers, assess the impact of earnings forecasts on stock performance, and identify critical variables in the decision-making process. Additionally, it addresses the importance of controlling investment-manager bias, which can lead to errors in active asset allocation, and warns against the risks of "backdoor market timing," a common pitfall for those committed to passive strategies.
Zakup książki
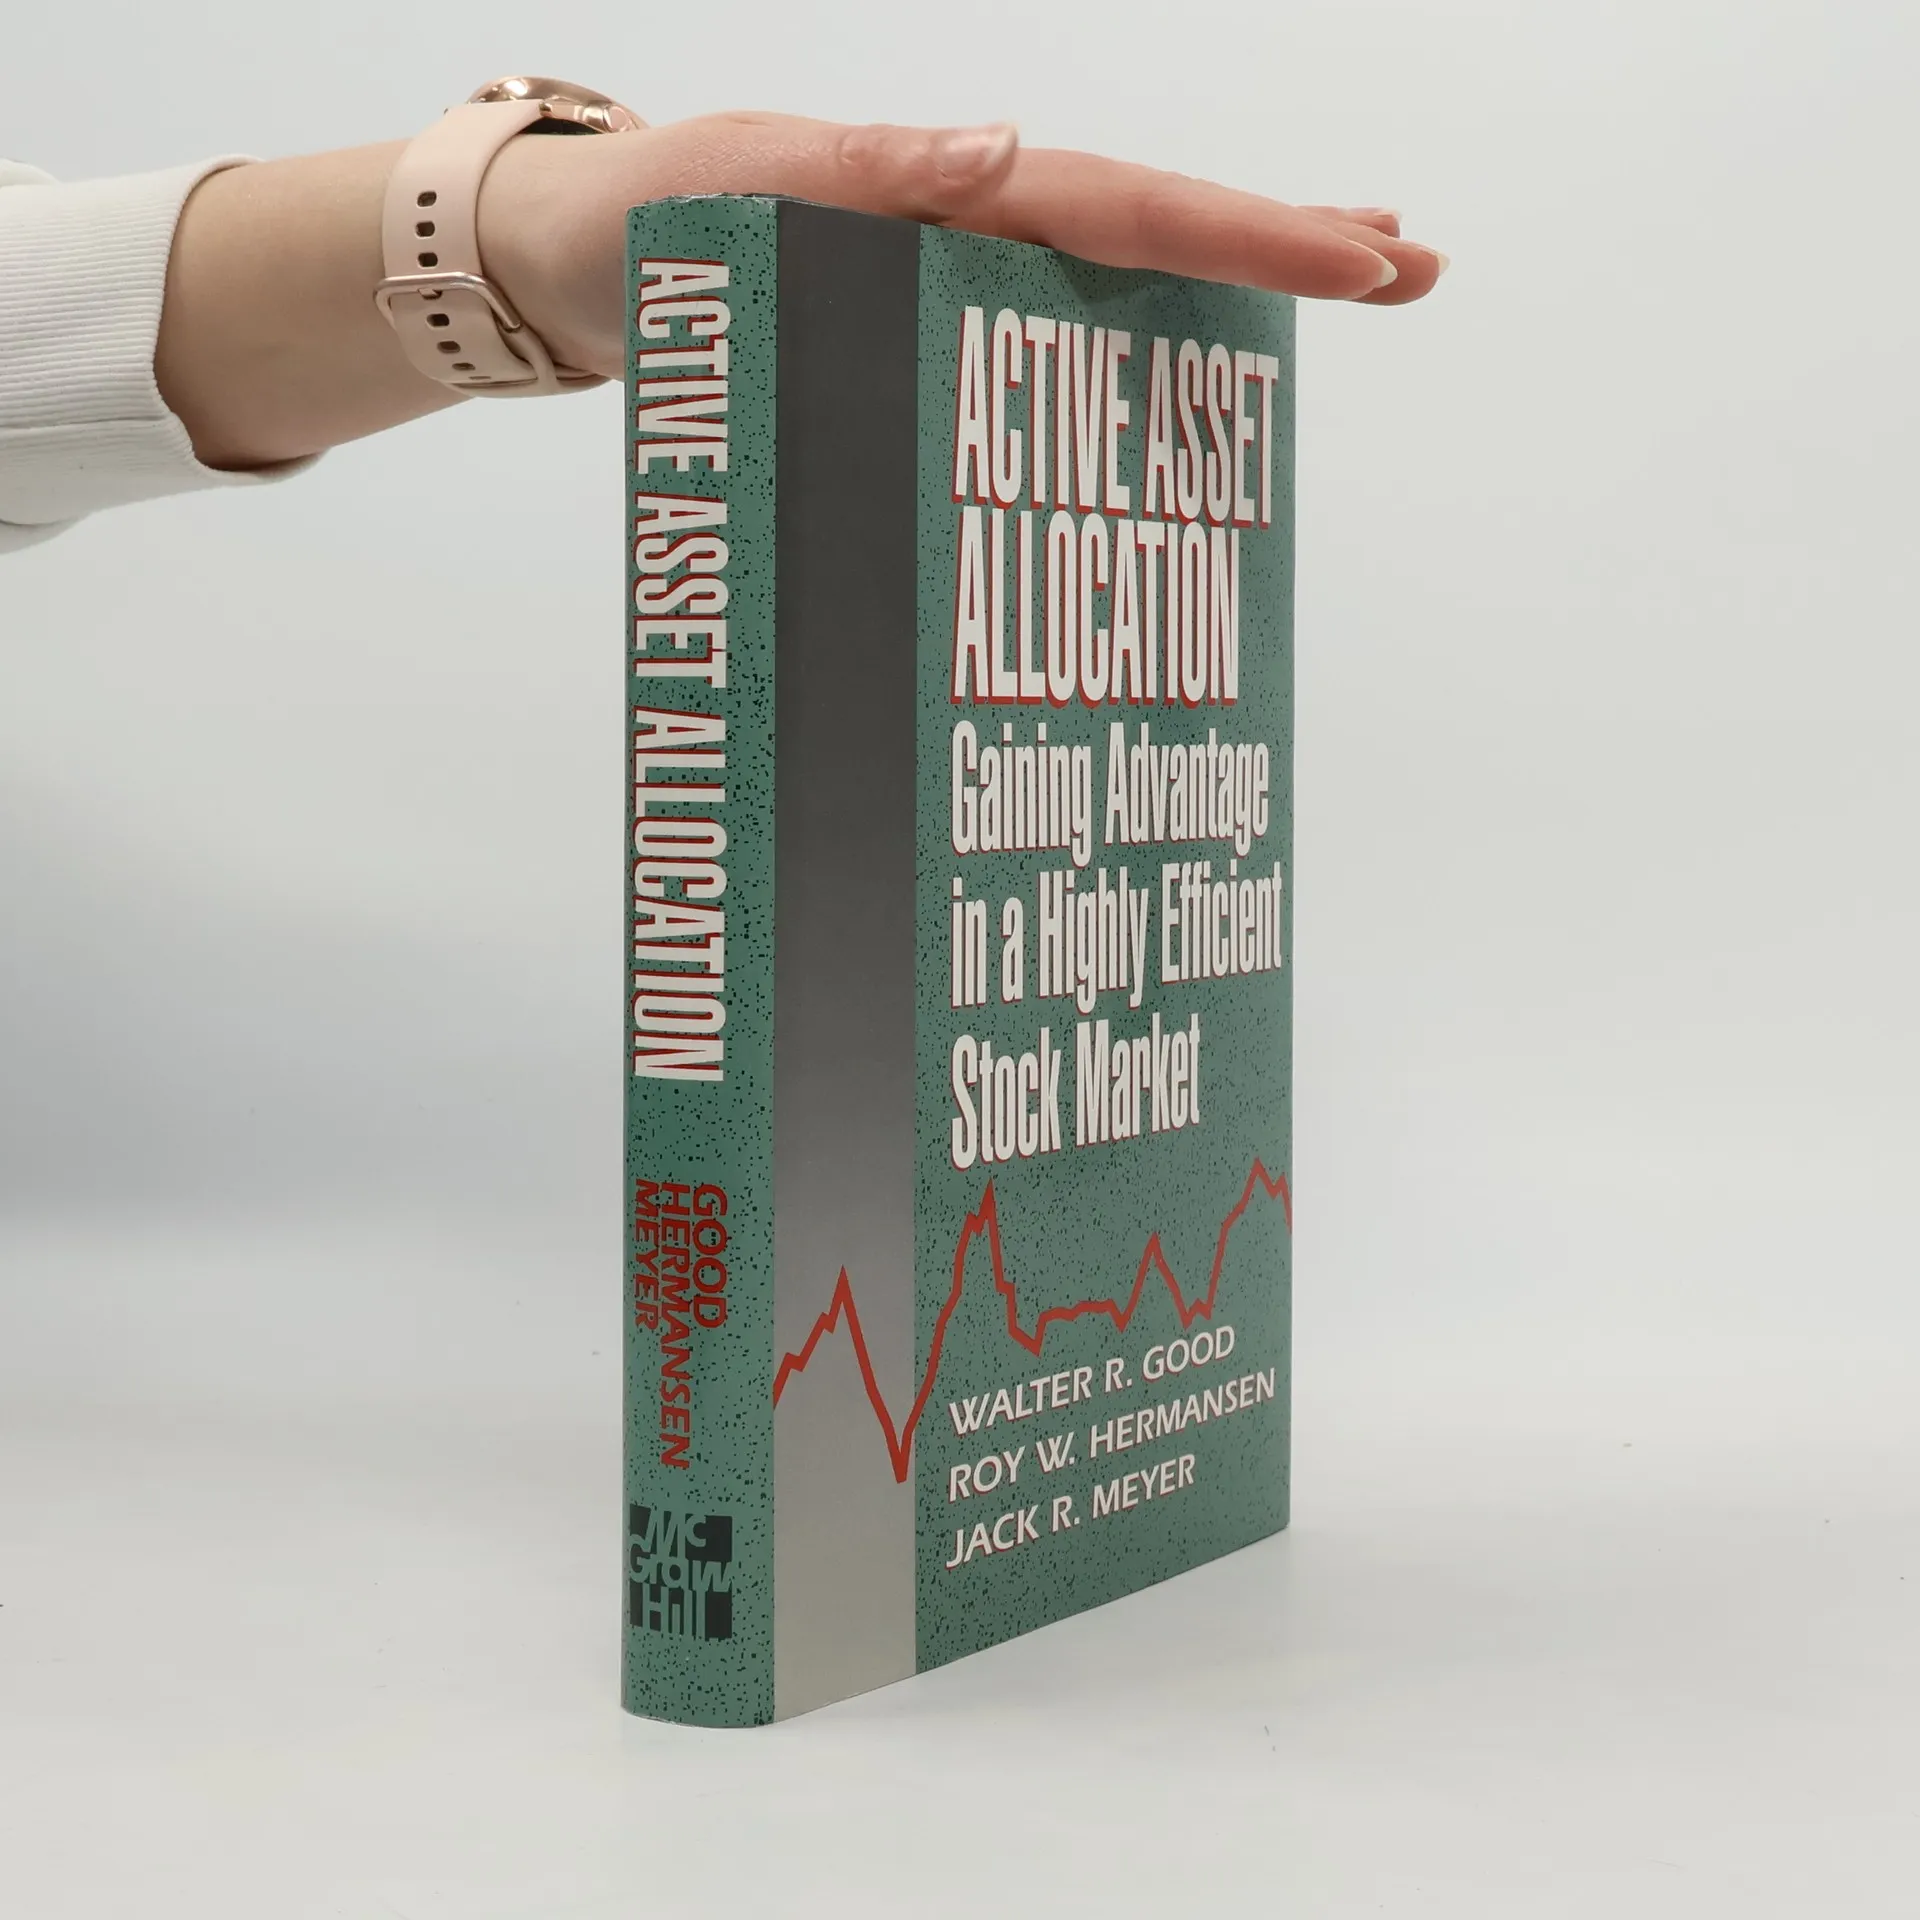
Active Asset Allocation, Walter R. Good, Roy W. Hermansen, Jack R. Meyer
- Język

- Rok wydania
- 1993
- Oprawa
- (twarda)
Metody płatności
Nikt jeszcze nie ocenił.
- Tytuł
- Active Asset Allocation
- Podtytuł
- Gaining Advantage in a Highly Efficient Stock Market
- Język
- angielski
- Autorzy
- Walter R. Good, Roy W. Hermansen, Jack R. Meyer
- Wydawca
- McGraw-Hill
- Rok wydania
- 1993
- Oprawa
- twarda
- Liczba stron
- 306
- ISBN10
- 0070237301
- ISBN13
- 9780070237308
- Seria
- Kategorie
- Tagi
- Biznes, USA, Inwestowanie, Akcje, Analiza inwestycyjna
- Opis
- How much of a portfolio should be allocated to the stock market? This question is crucial for both institutional and individual investors. The text explores this vital investment dilemma, advocating for active management of asset allocation within a long-term passive framework. Central to this strategy is a novel approach to stock market valuation developed through the authors' experience with large institutional investors. Traditionally, active management and passive investing are seen as opposing strategies. However, the authors propose a decision-making process that challenges this notion. By using market prices as a repository of information, they identify three key measures related to business outlook, interest rates, and investor confidence that can predict stock market changes. The text provides a comprehensive blueprint for implementing active asset allocation within a long-term passive plan. It delves into how to uncover hidden information in financial markets, focus on the limited opportunities available to active managers, assess the impact of earnings forecasts on stock performance, and identify critical variables in the decision-making process. Additionally, it addresses the importance of controlling investment-manager bias, which can lead to errors in active asset allocation, and warns against the risks of "backdoor market timing," a common pitfall for those committed to passive strategies.