

Parametry
- 736 stron
- 26 godzin czytania
Więcej o książce
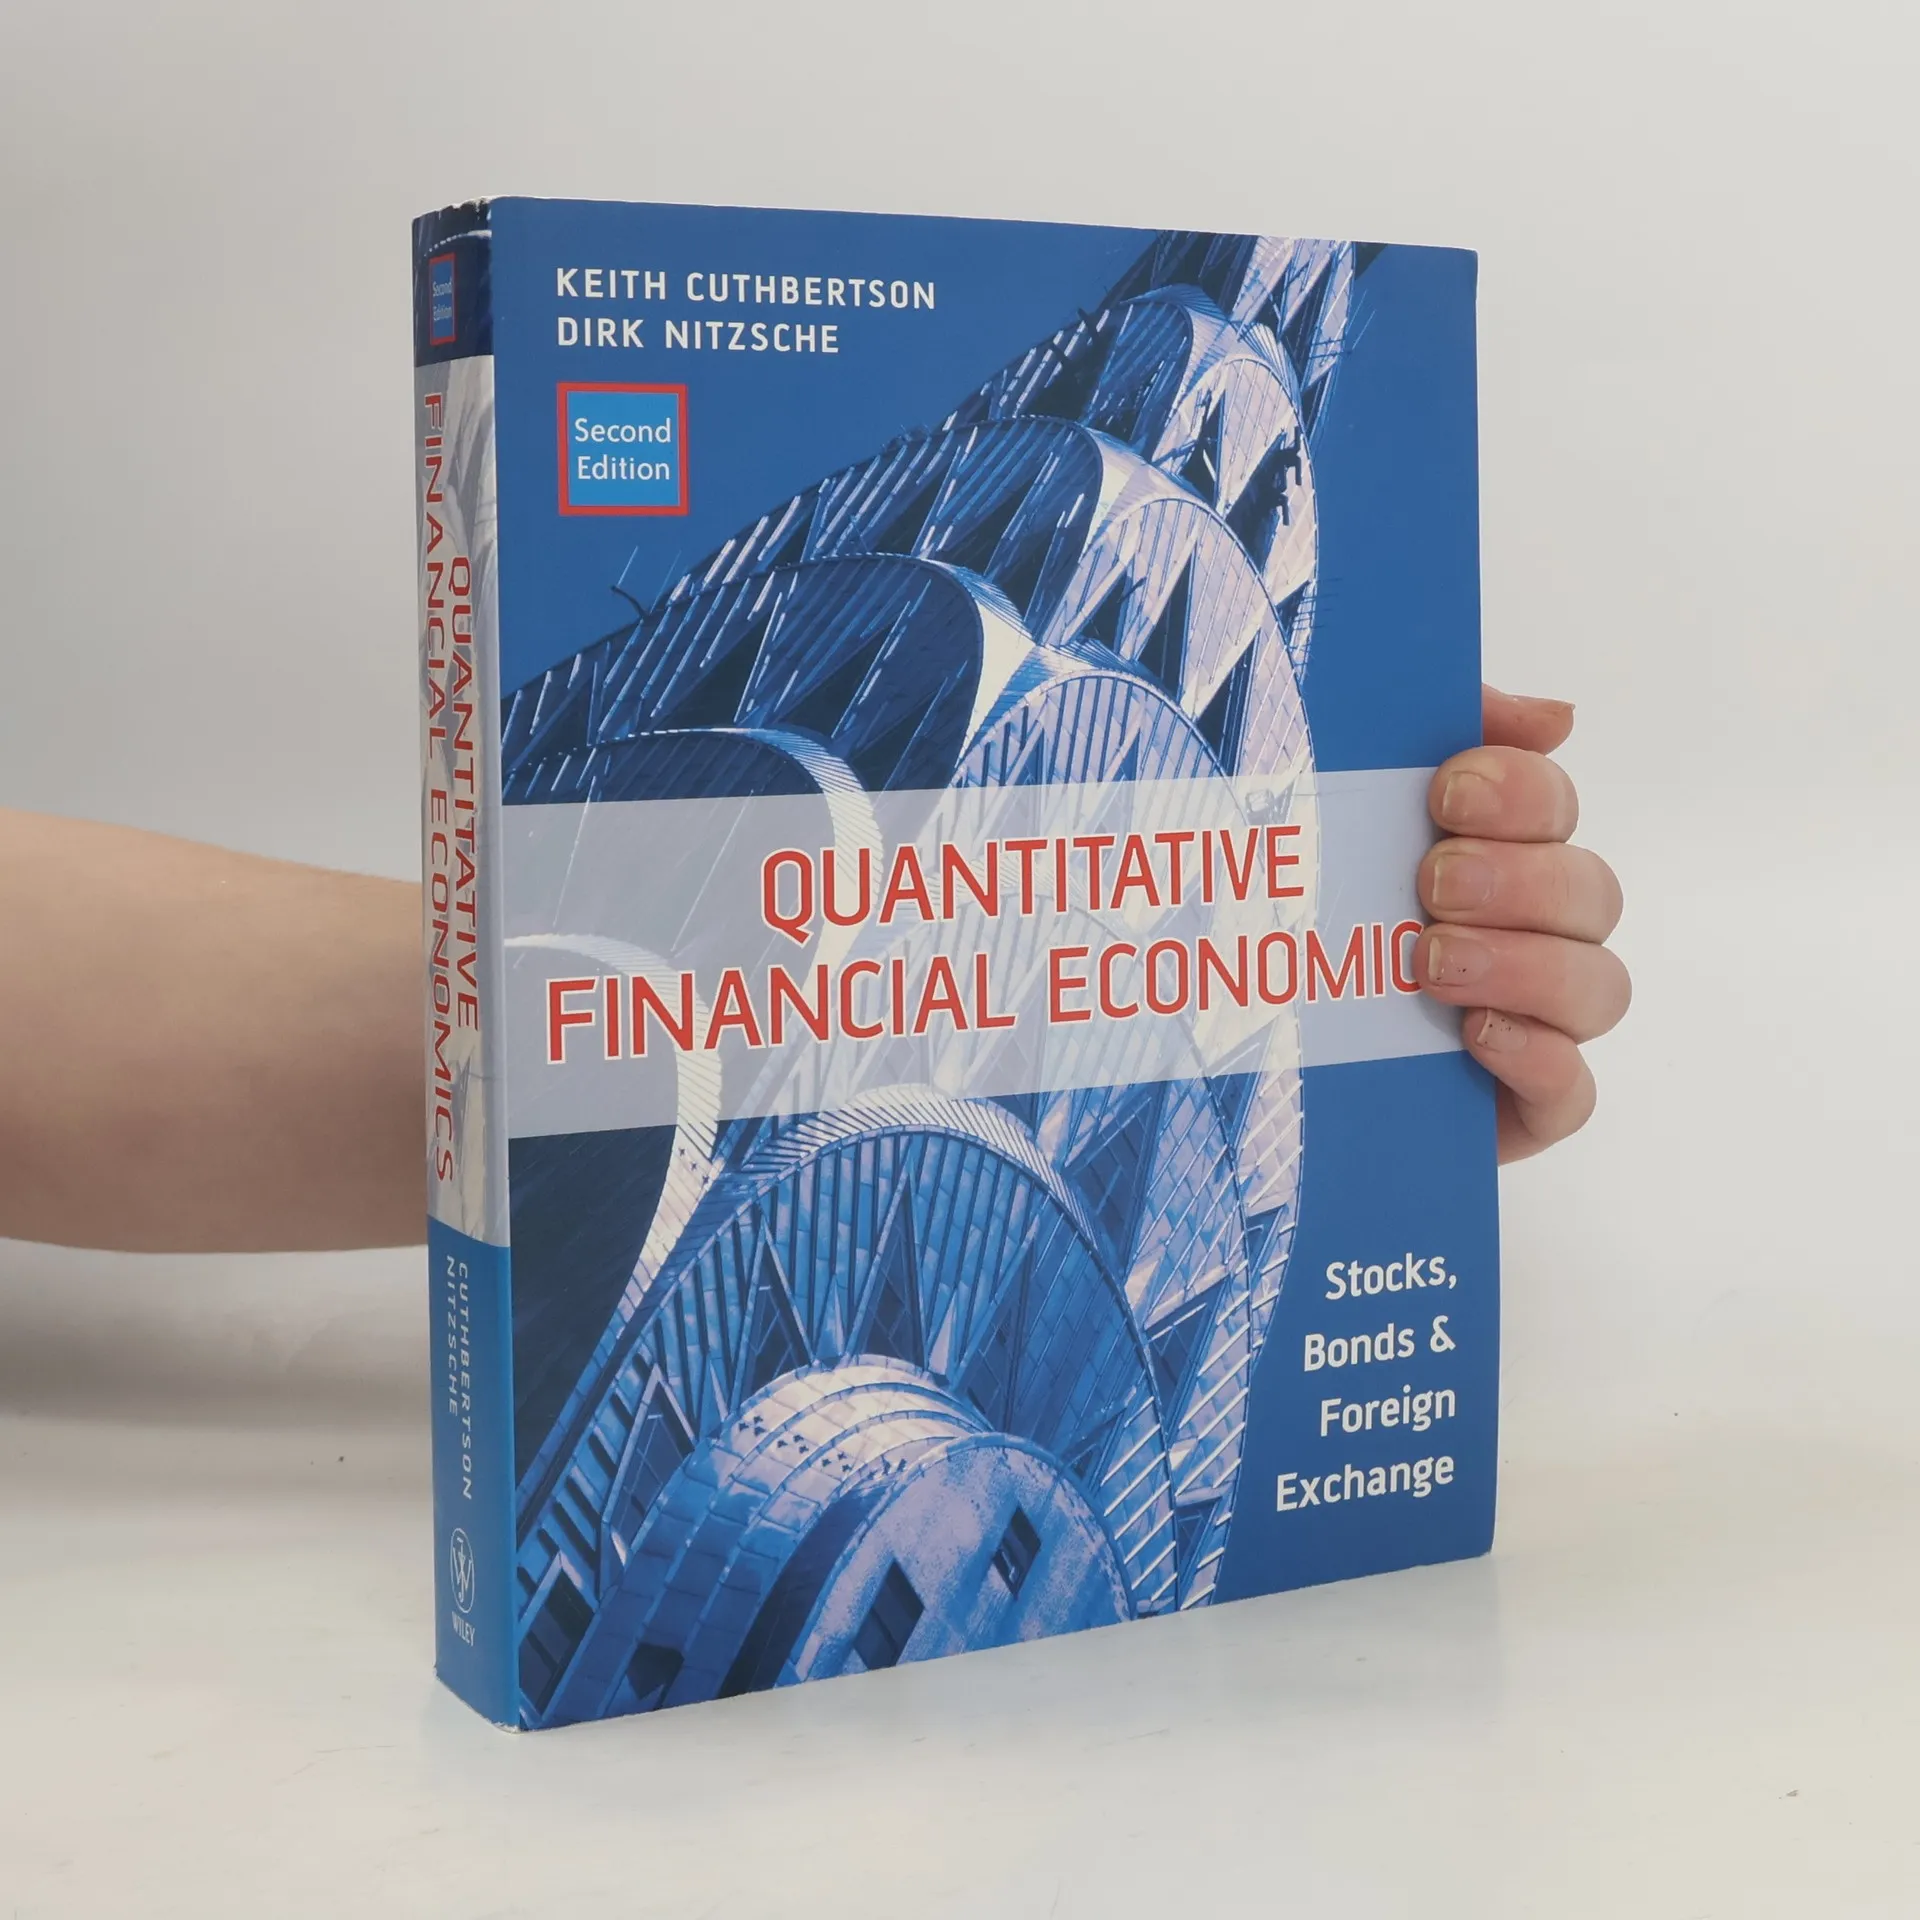
This comprehensive introduction to economic behavior models in financial markets emphasizes analysis in discrete time. The fully revised second edition reflects new developments in theory and practice, building on the success of the first edition. The authors explore theories and tests of competing ideas in financial markets, utilizing examples from stock, bond, and foreign exchange markets. A key focus is on how models inform real-world decisions, making the content accessible for both students and quantitative practitioners studying asset returns and prices. Reviews of the first edition highlight its clarity and intuitive explanations, making it valuable for students and empirical researchers in macroeconomics and finance. Readers found it accessible and informative, offering fresh perspectives on recent empirical literature, and a useful resource for finance doctoral students and academics. Additionally, the book features a supporting website that includes questions and answers, illustrative Excel and GAUSS programs, and econometrics notes, enhancing the learning experience.
Zakup książki
Quantitative Financial Economics, Keith Cuthbertson, Dirk Nitzsche
- Język

- Rok wydania
- 2004
- Oprawa
- (miękka)
Metody płatności
Brakuje nam tutaj Twojej recenzji.
- Tytuł
- Quantitative Financial Economics
- Podtytuł
- Stocks, Bonds and Foreign Exchange - Second Edition
- Język
- angielski
- Autorzy
- Keith Cuthbertson, Dirk Nitzsche
- Wydawca
- WILEY
- Rok wydania
- 2004
- Oprawa
- miękka
- Liczba stron
- 736
- ISBN10
- 0470091711
- ISBN13
- 9780470091715
- Seria
- Kategorie
- Tagi
- Biznes, Tematy prawne, Finanse, Inwestowanie, Akcje, Dobro
- Ocena
- 3 z 5
- Opis
- This comprehensive introduction to economic behavior models in financial markets emphasizes analysis in discrete time. The fully revised second edition reflects new developments in theory and practice, building on the success of the first edition. The authors explore theories and tests of competing ideas in financial markets, utilizing examples from stock, bond, and foreign exchange markets. A key focus is on how models inform real-world decisions, making the content accessible for both students and quantitative practitioners studying asset returns and prices. Reviews of the first edition highlight its clarity and intuitive explanations, making it valuable for students and empirical researchers in macroeconomics and finance. Readers found it accessible and informative, offering fresh perspectives on recent empirical literature, and a useful resource for finance doctoral students and academics. Additionally, the book features a supporting website that includes questions and answers, illustrative Excel and GAUSS programs, and econometrics notes, enhancing the learning experience.