

Więcej o książce
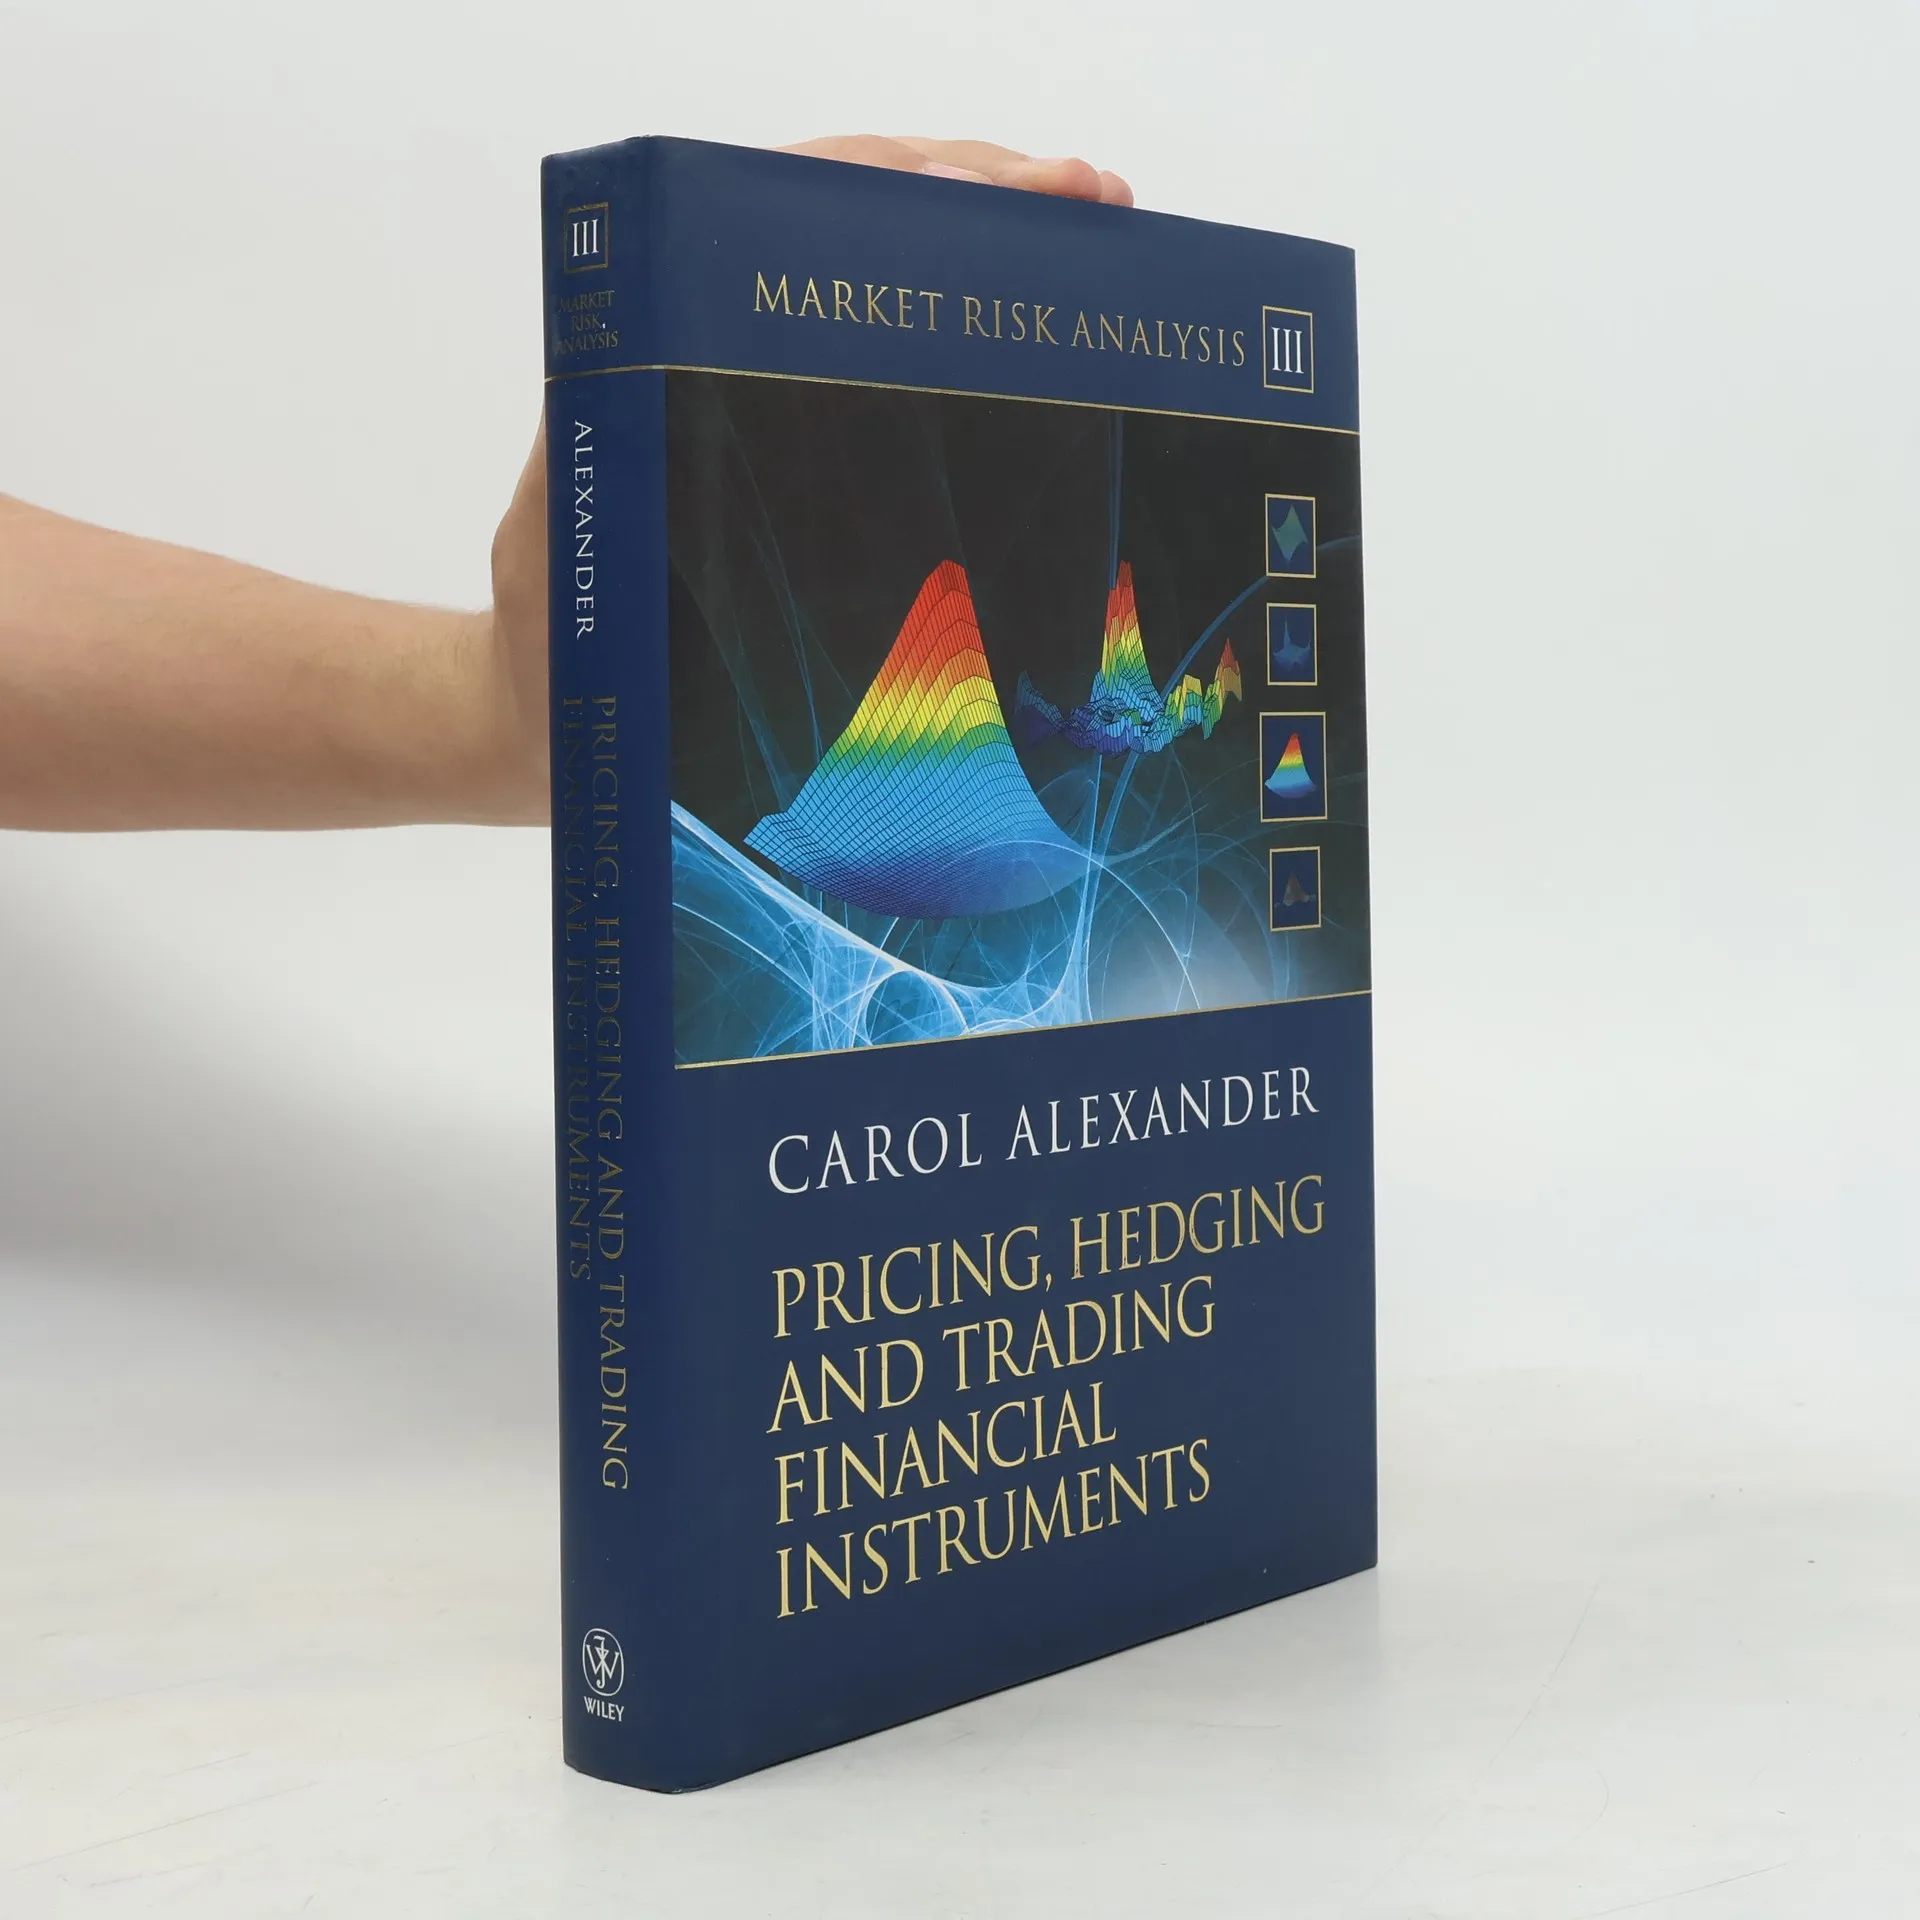
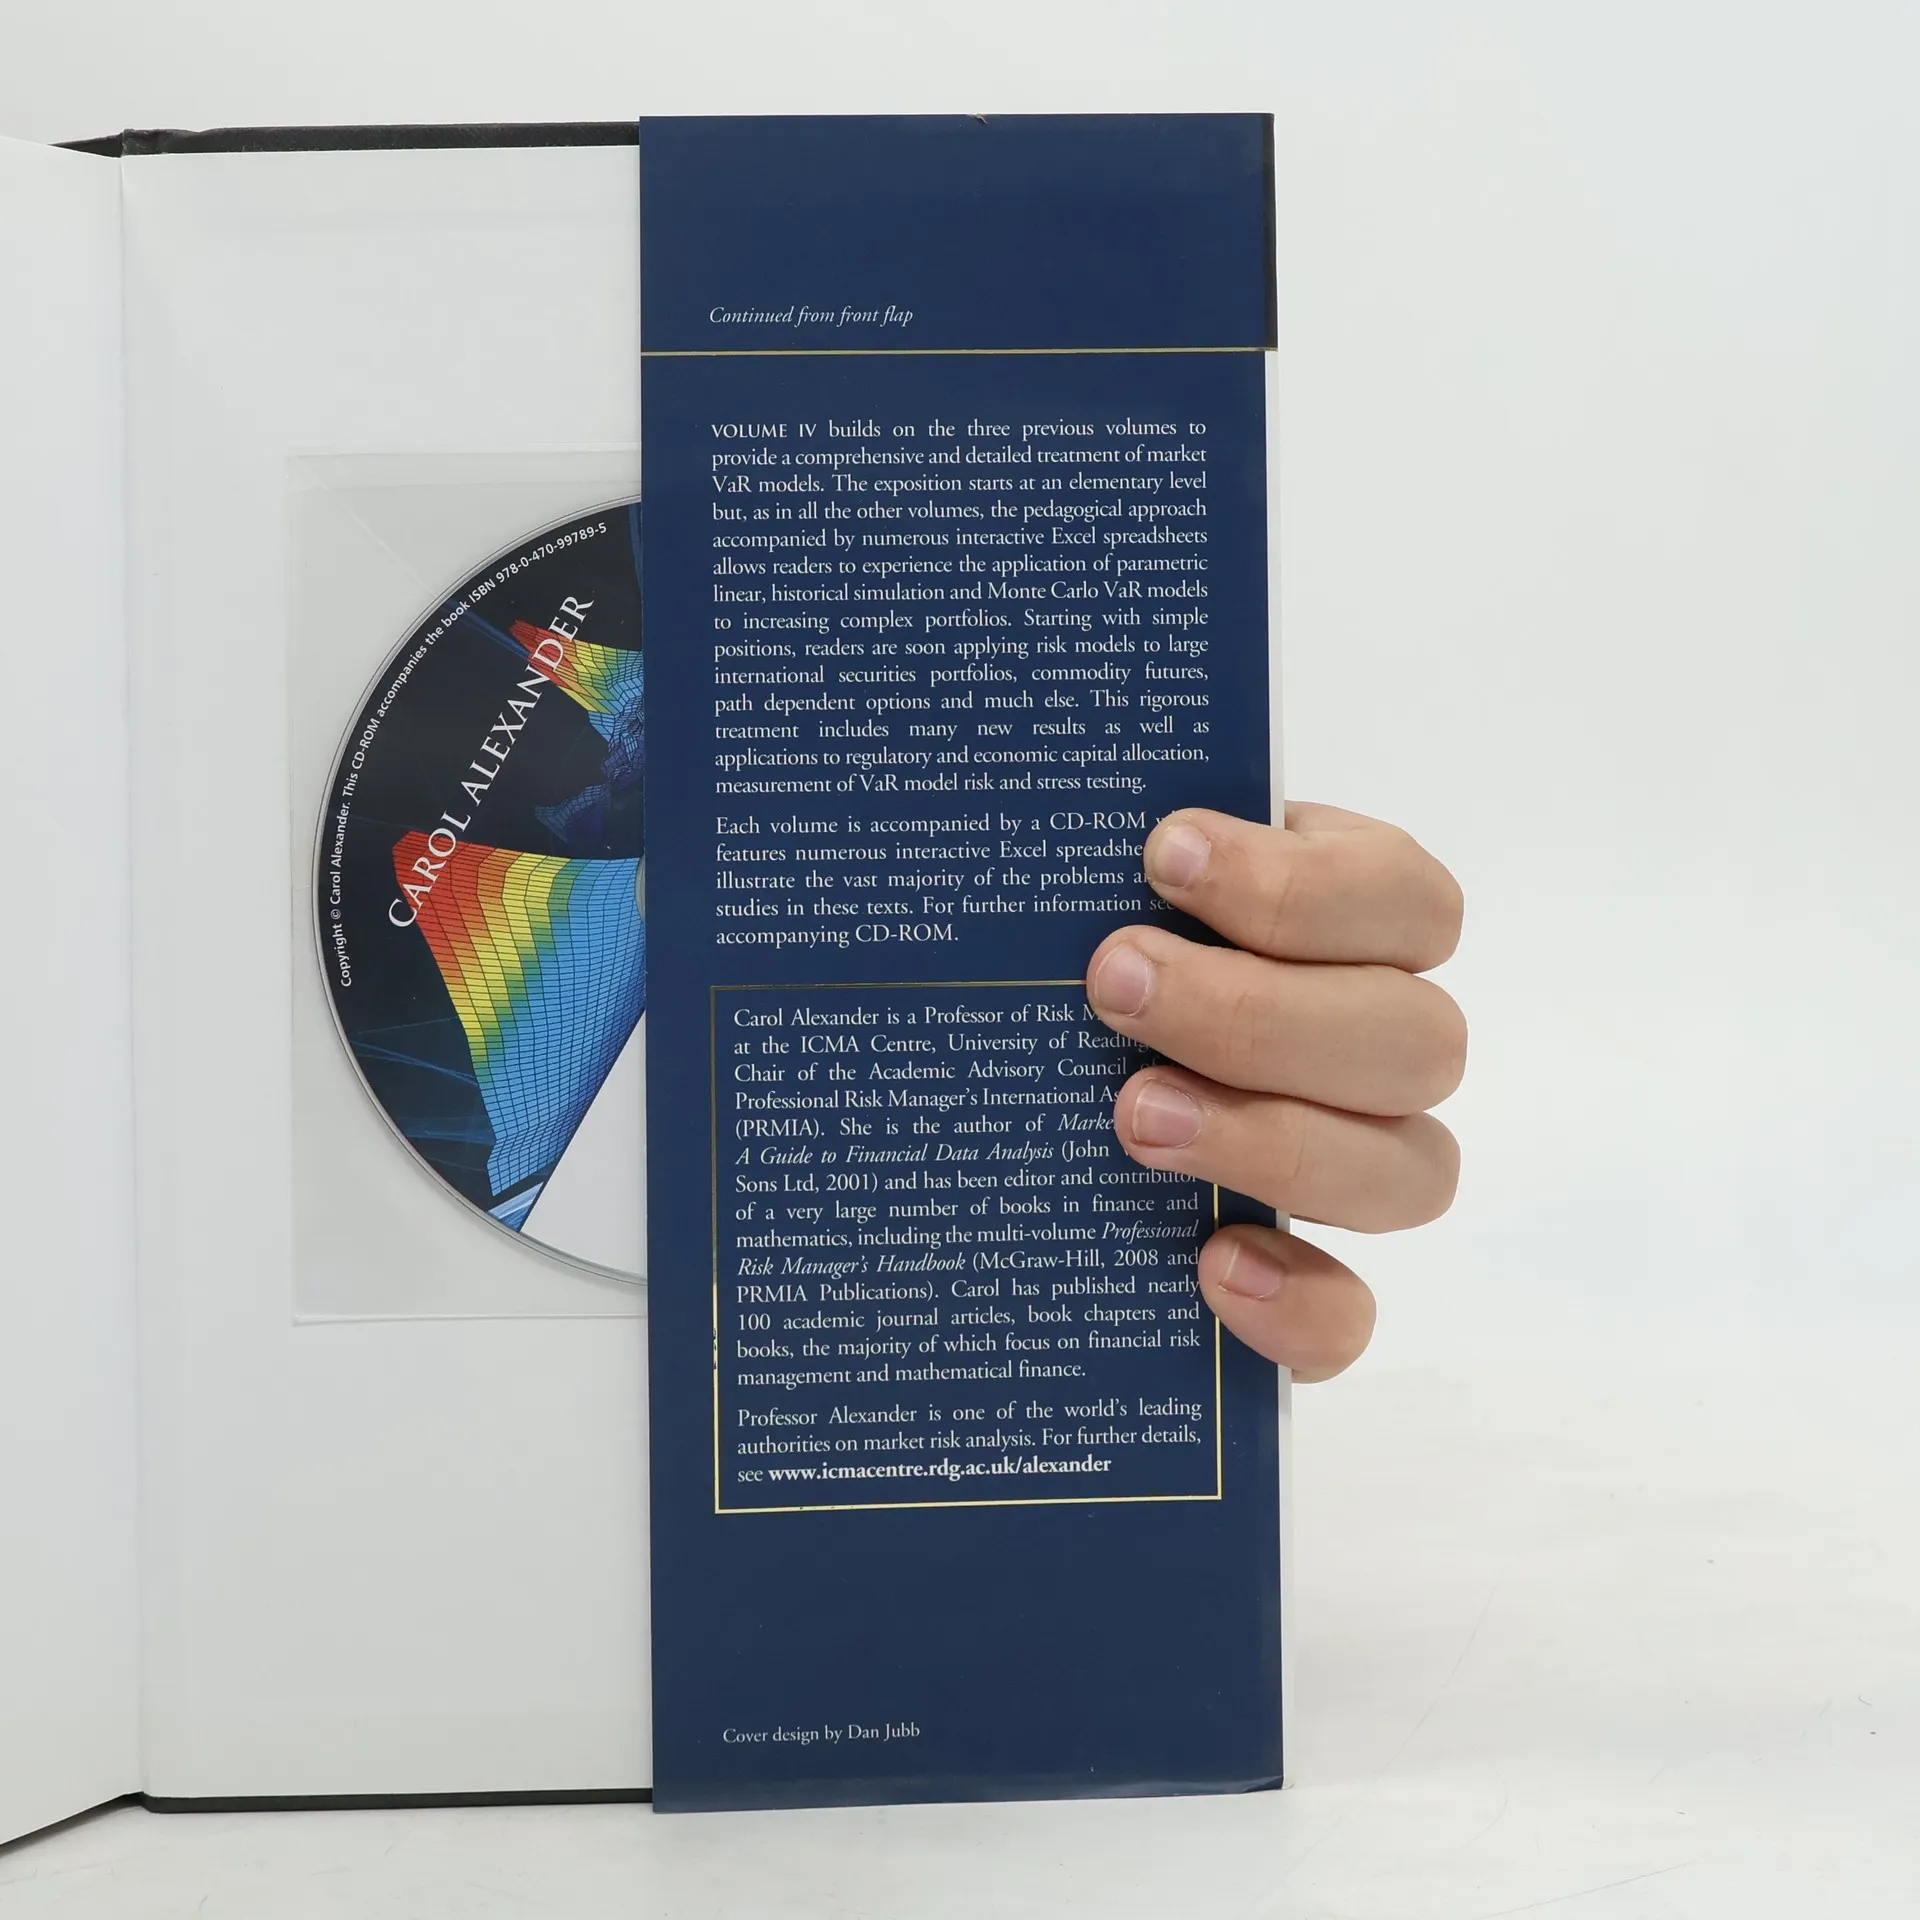
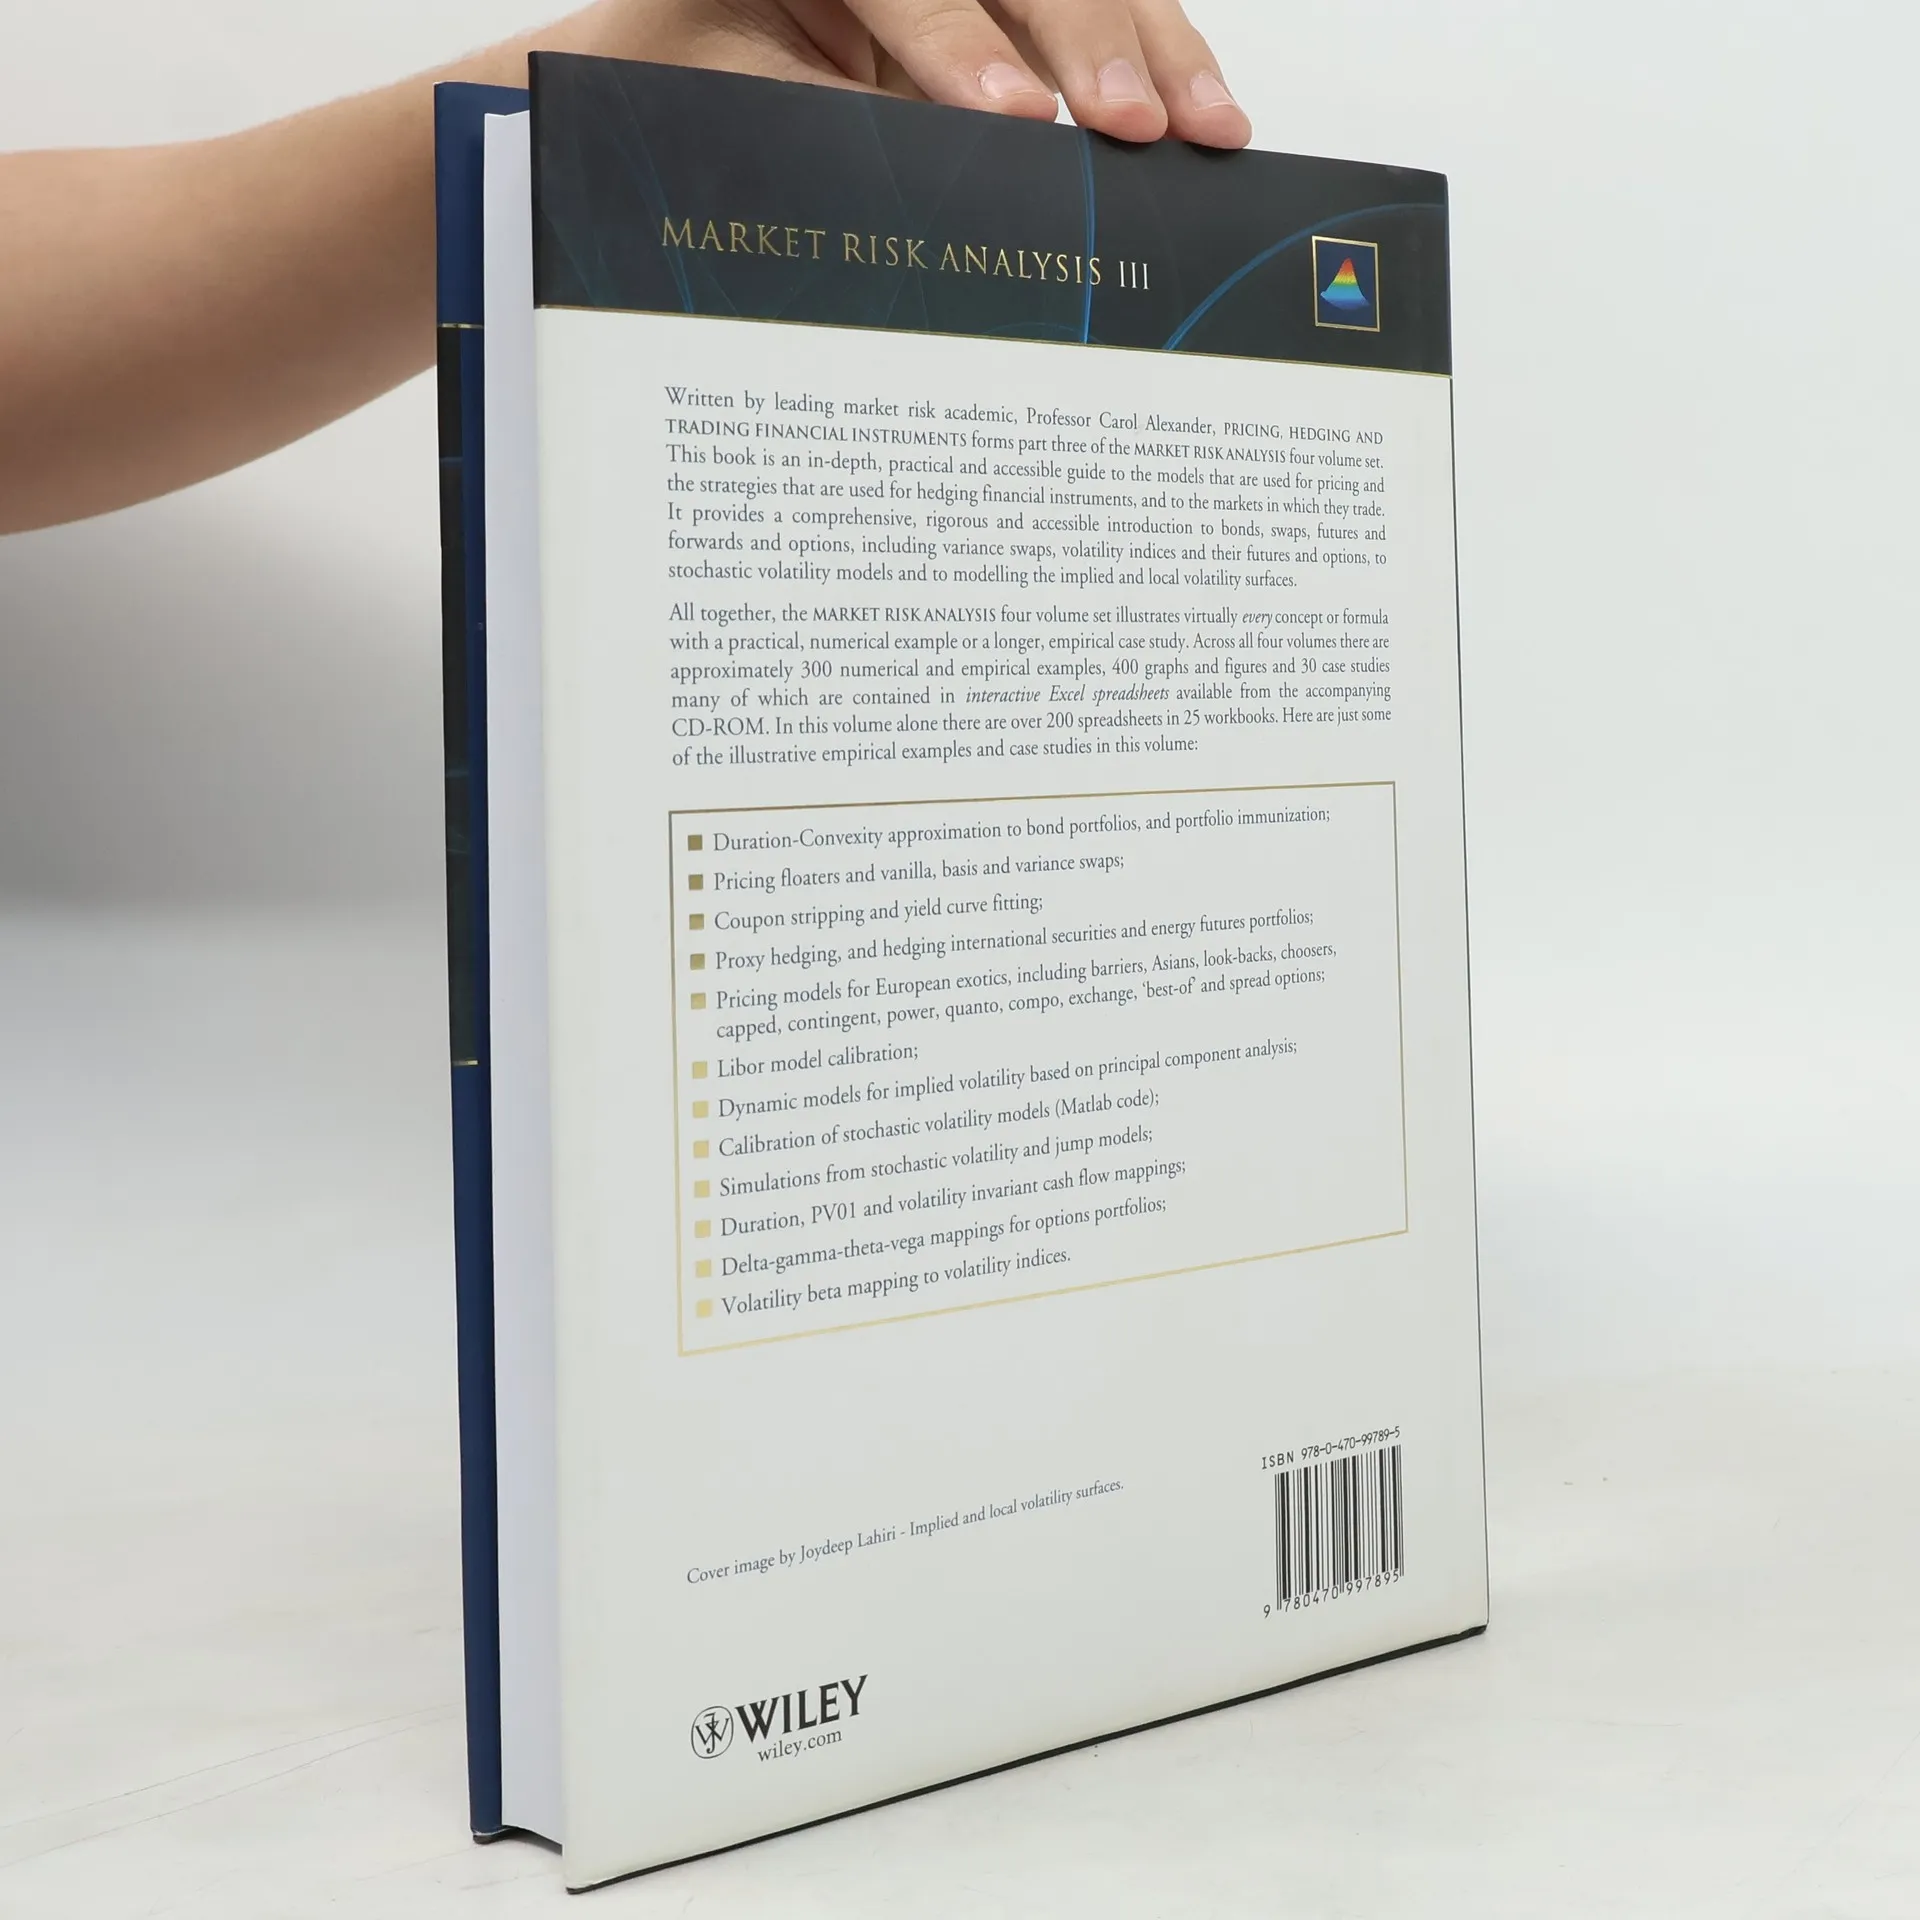
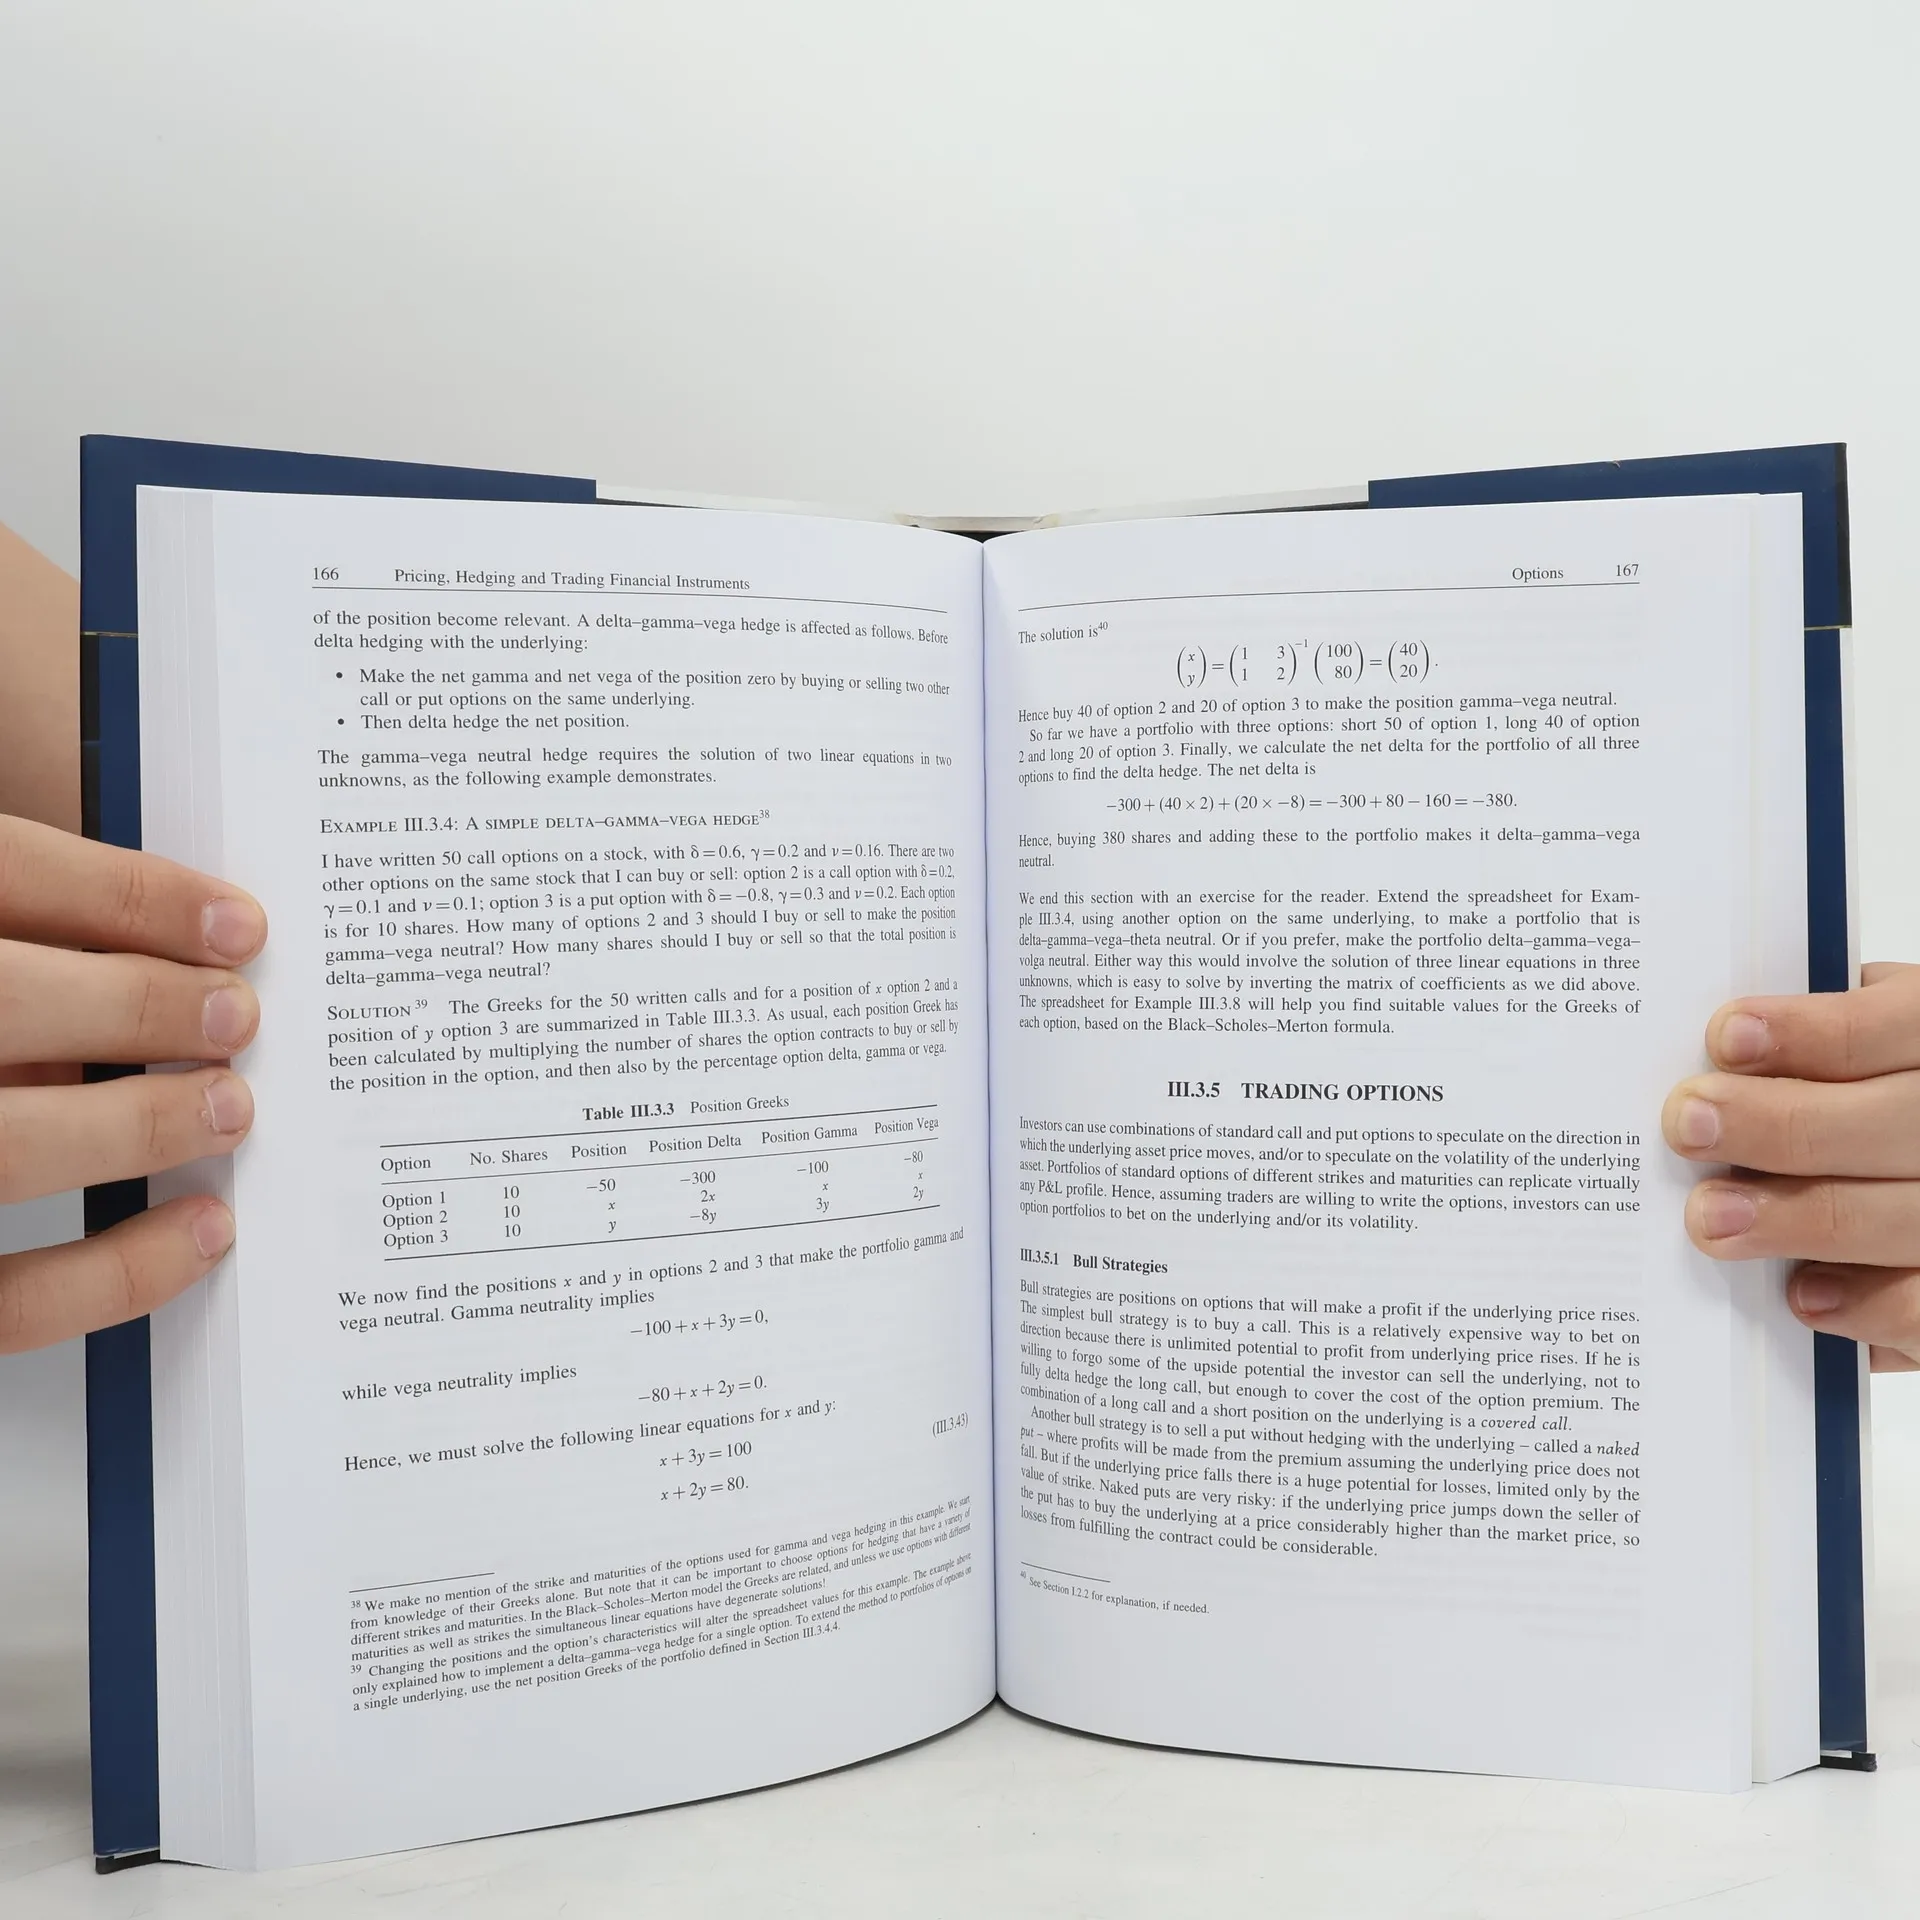
Written by leading market risk academic, Professor Carol Alexander, Pricing, Hedging and Trading Financial Instruments forms part three of the Market Risk Analysis four volume set. This book is an in-depth, practical and accessible guide to the models that are used for pricing and the strategies that are used for hedging financial instruments, and to the markets in which they trade. It provides a comprehensive, rigorous and accessible introduction to bonds, swaps, futures and forwards and options, including variance swaps, volatility indices and their futures and options, to stochastic volatility models and to modelling the implied and local volatility surfaces. All together, the Market Risk Analysis four volume set illustrates virtually every concept or formula with a practical, numerical example or a longer, empirical case study. Across all four volumes there are approximately 300 numerical and empirical examples, 400 graphs and figures and 30 case studies many of which are contained in interactive Excel spreadsheets available from the the accompanying CD-ROM . Empirical examples and case studies specific to this volume
Zakup książki
Market Risk Analysis, Pricing, Hedging and Trading Financial Instruments, Carol Alexander
- Język

- Rok wydania
- 2008
- Oprawa
- (twarda)
Metody płatności
Brakuje nam tutaj Twojej recenzji.
- Tytuł
- Market Risk Analysis, Pricing, Hedging and Trading Financial Instruments
- Język
- angielski
- Autorzy
- Carol Alexander
- Wydawca
- WILEY
- Rok wydania
- 2008
- Oprawa
- twarda
- Liczba stron
- 416
- ISBN10
- 0470997893
- ISBN13
- 9780470997895
- Seria
- Kategorie
- Tagi
- Biznes, Tematy prawne, Finanse, Nauczyciele, Modelka
- Ocena
- 4,15 z 5
- Opis
- Written by leading market risk academic, Professor Carol Alexander, Pricing, Hedging and Trading Financial Instruments forms part three of the Market Risk Analysis four volume set. This book is an in-depth, practical and accessible guide to the models that are used for pricing and the strategies that are used for hedging financial instruments, and to the markets in which they trade. It provides a comprehensive, rigorous and accessible introduction to bonds, swaps, futures and forwards and options, including variance swaps, volatility indices and their futures and options, to stochastic volatility models and to modelling the implied and local volatility surfaces. All together, the Market Risk Analysis four volume set illustrates virtually every concept or formula with a practical, numerical example or a longer, empirical case study. Across all four volumes there are approximately 300 numerical and empirical examples, 400 graphs and figures and 30 case studies many of which are contained in interactive Excel spreadsheets available from the the accompanying CD-ROM . Empirical examples and case studies specific to this volume