

Więcej o książce
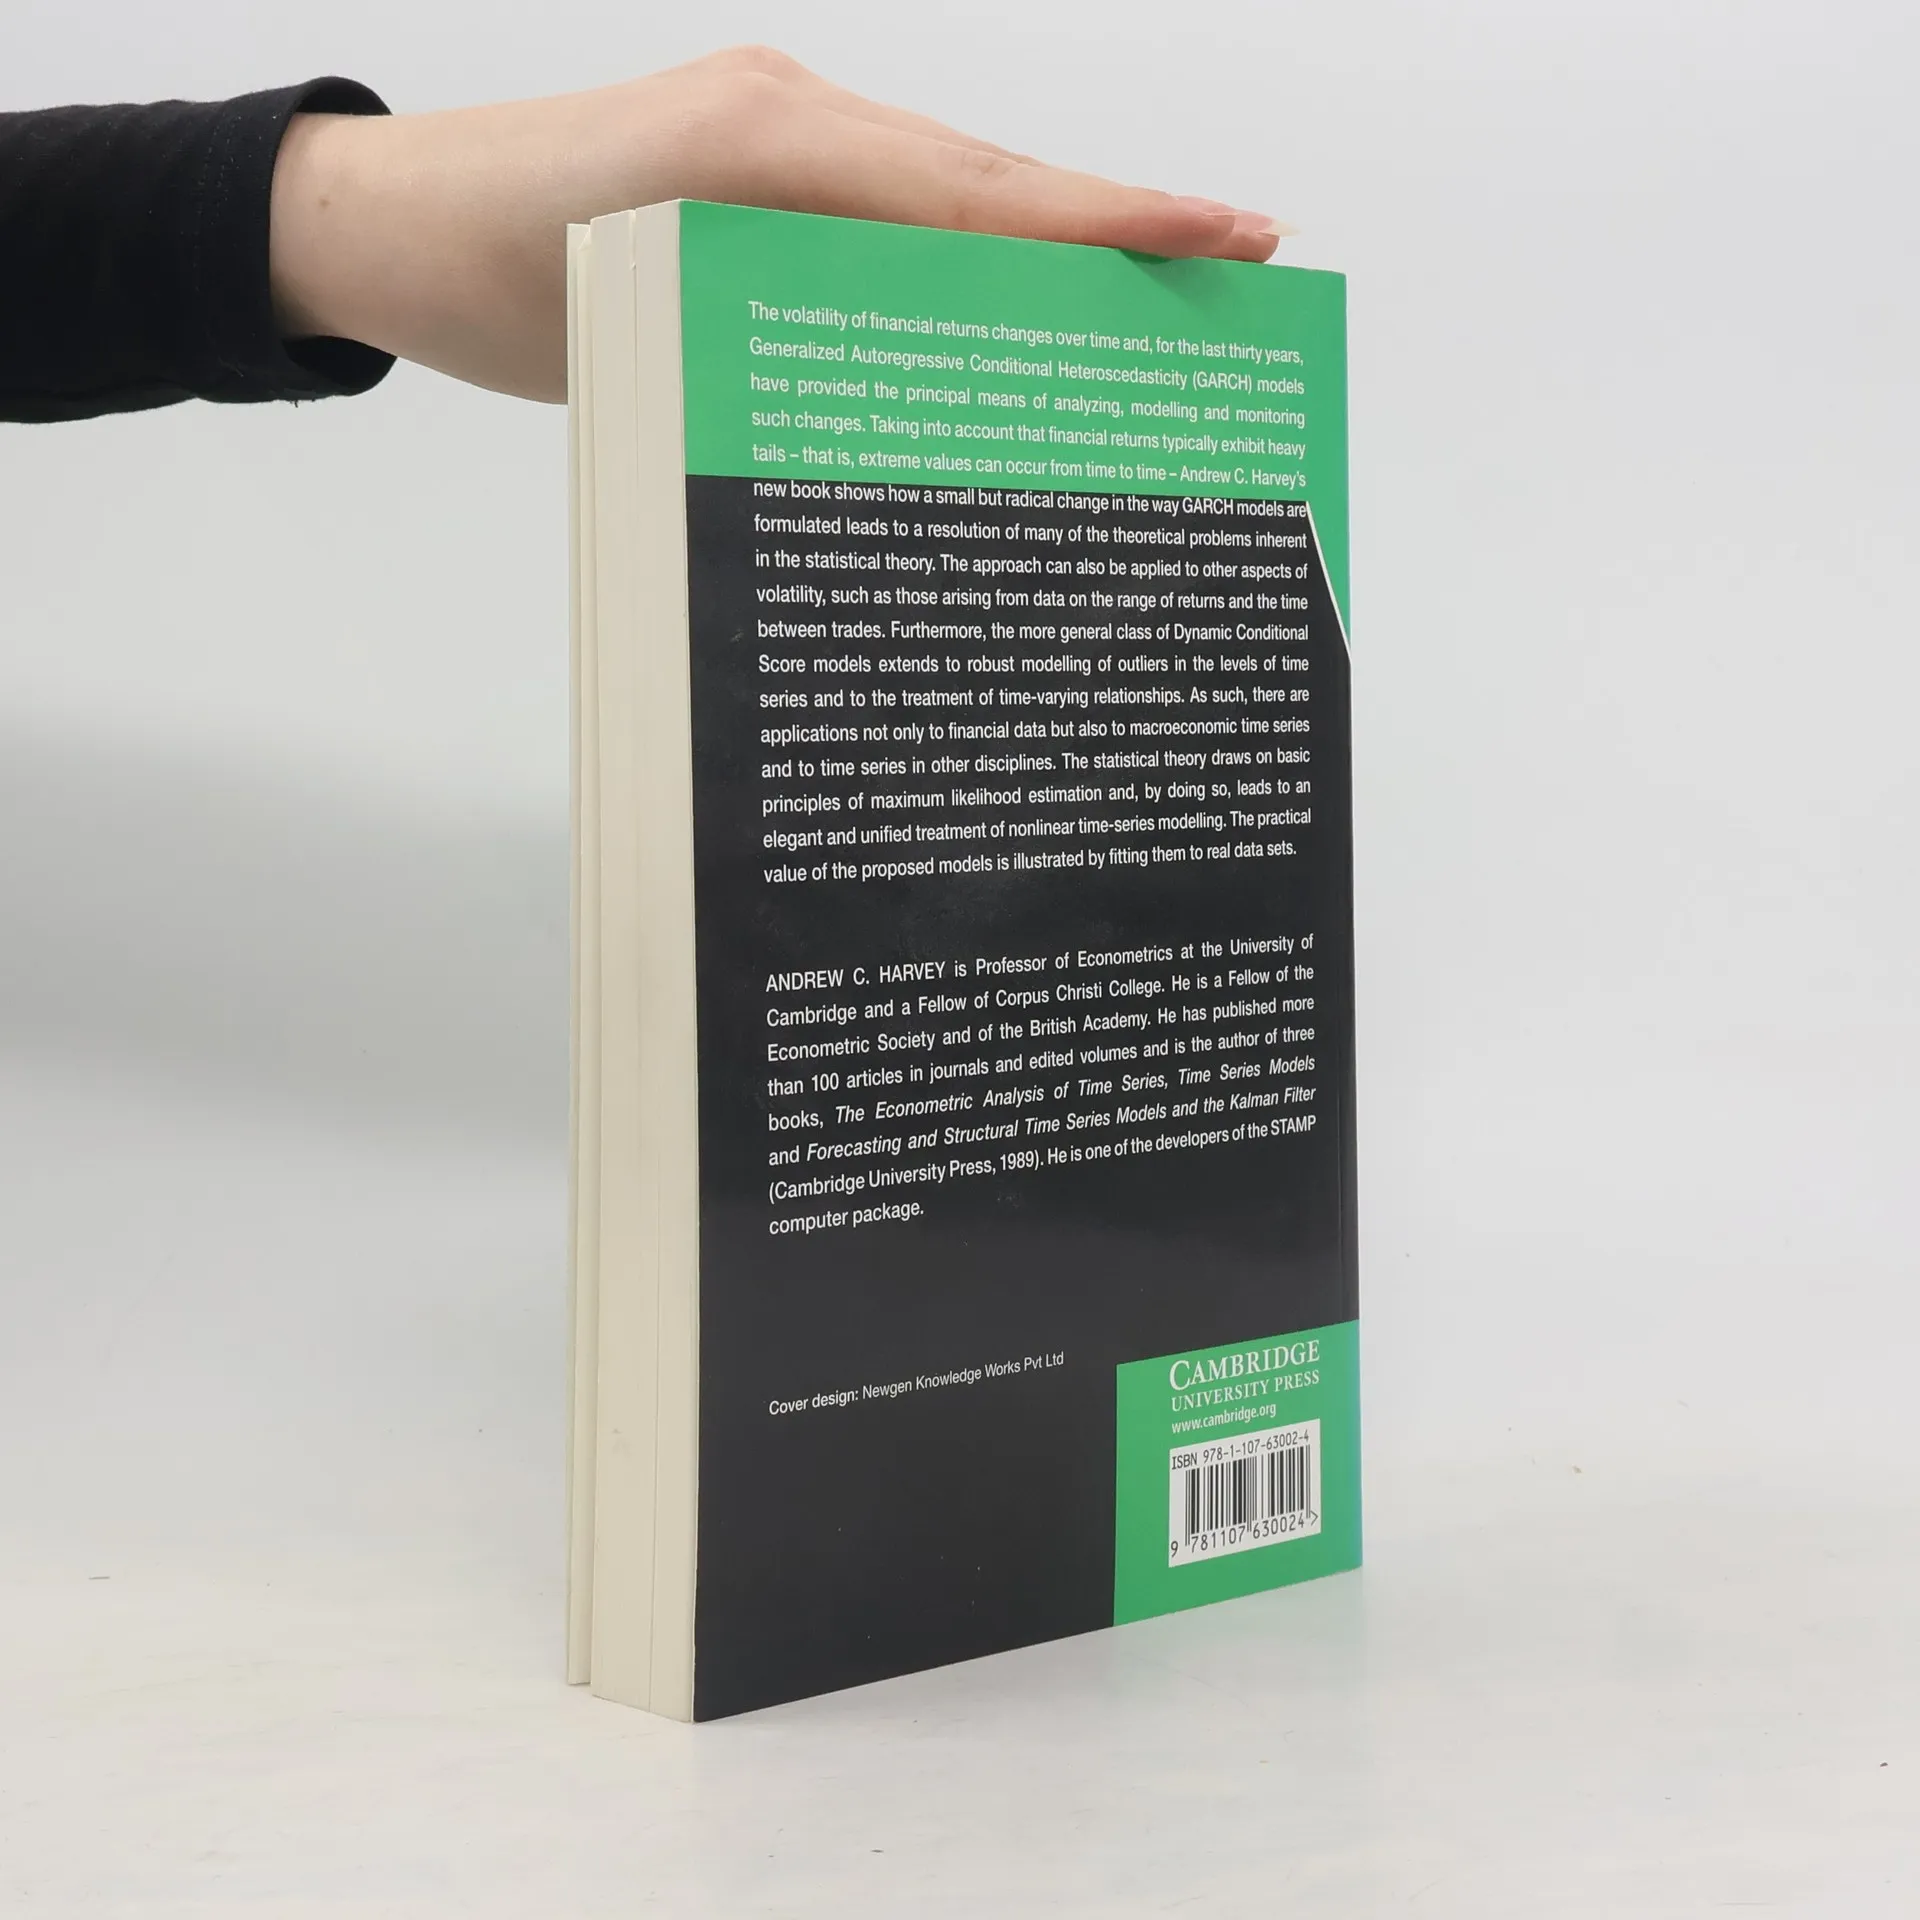
The volatility of financial returns changes over time and, for the last thirty years, Generalized Autoregressive Conditional Heteroscedasticity (GARCH) models have provided the principal means of analyzing, modeling, and monitoring such changes. Taking into account that financial returns typically exhibit heavy tails that is, extreme values can occur from time to time Andrew Harvey's new book shows how a small but radical change in the way GARCH models are formulated leads to a resolution of many of the theoretical problems inherent in the statistical theory. The approach can also be applied to other aspects of volatility, such as those arising from data on the range of returns and the time between trades. Furthermore, the more general class of Dynamic Conditional Score models extends to robust modeling of outliers in the levels of time series and to the treatment of time-varying relationships. As such, there are applications not only to financial data but also to macroeconomic time series and to time series in other disciplines. The statistical theory draws on basic principles of maximum likelihood estimation and, by doing so, leads to an elegant and unified treatment of nonlinear time-series modeling. The practical value of the proposed models is illustrated by fitting them to real data sets.
Zakup książki
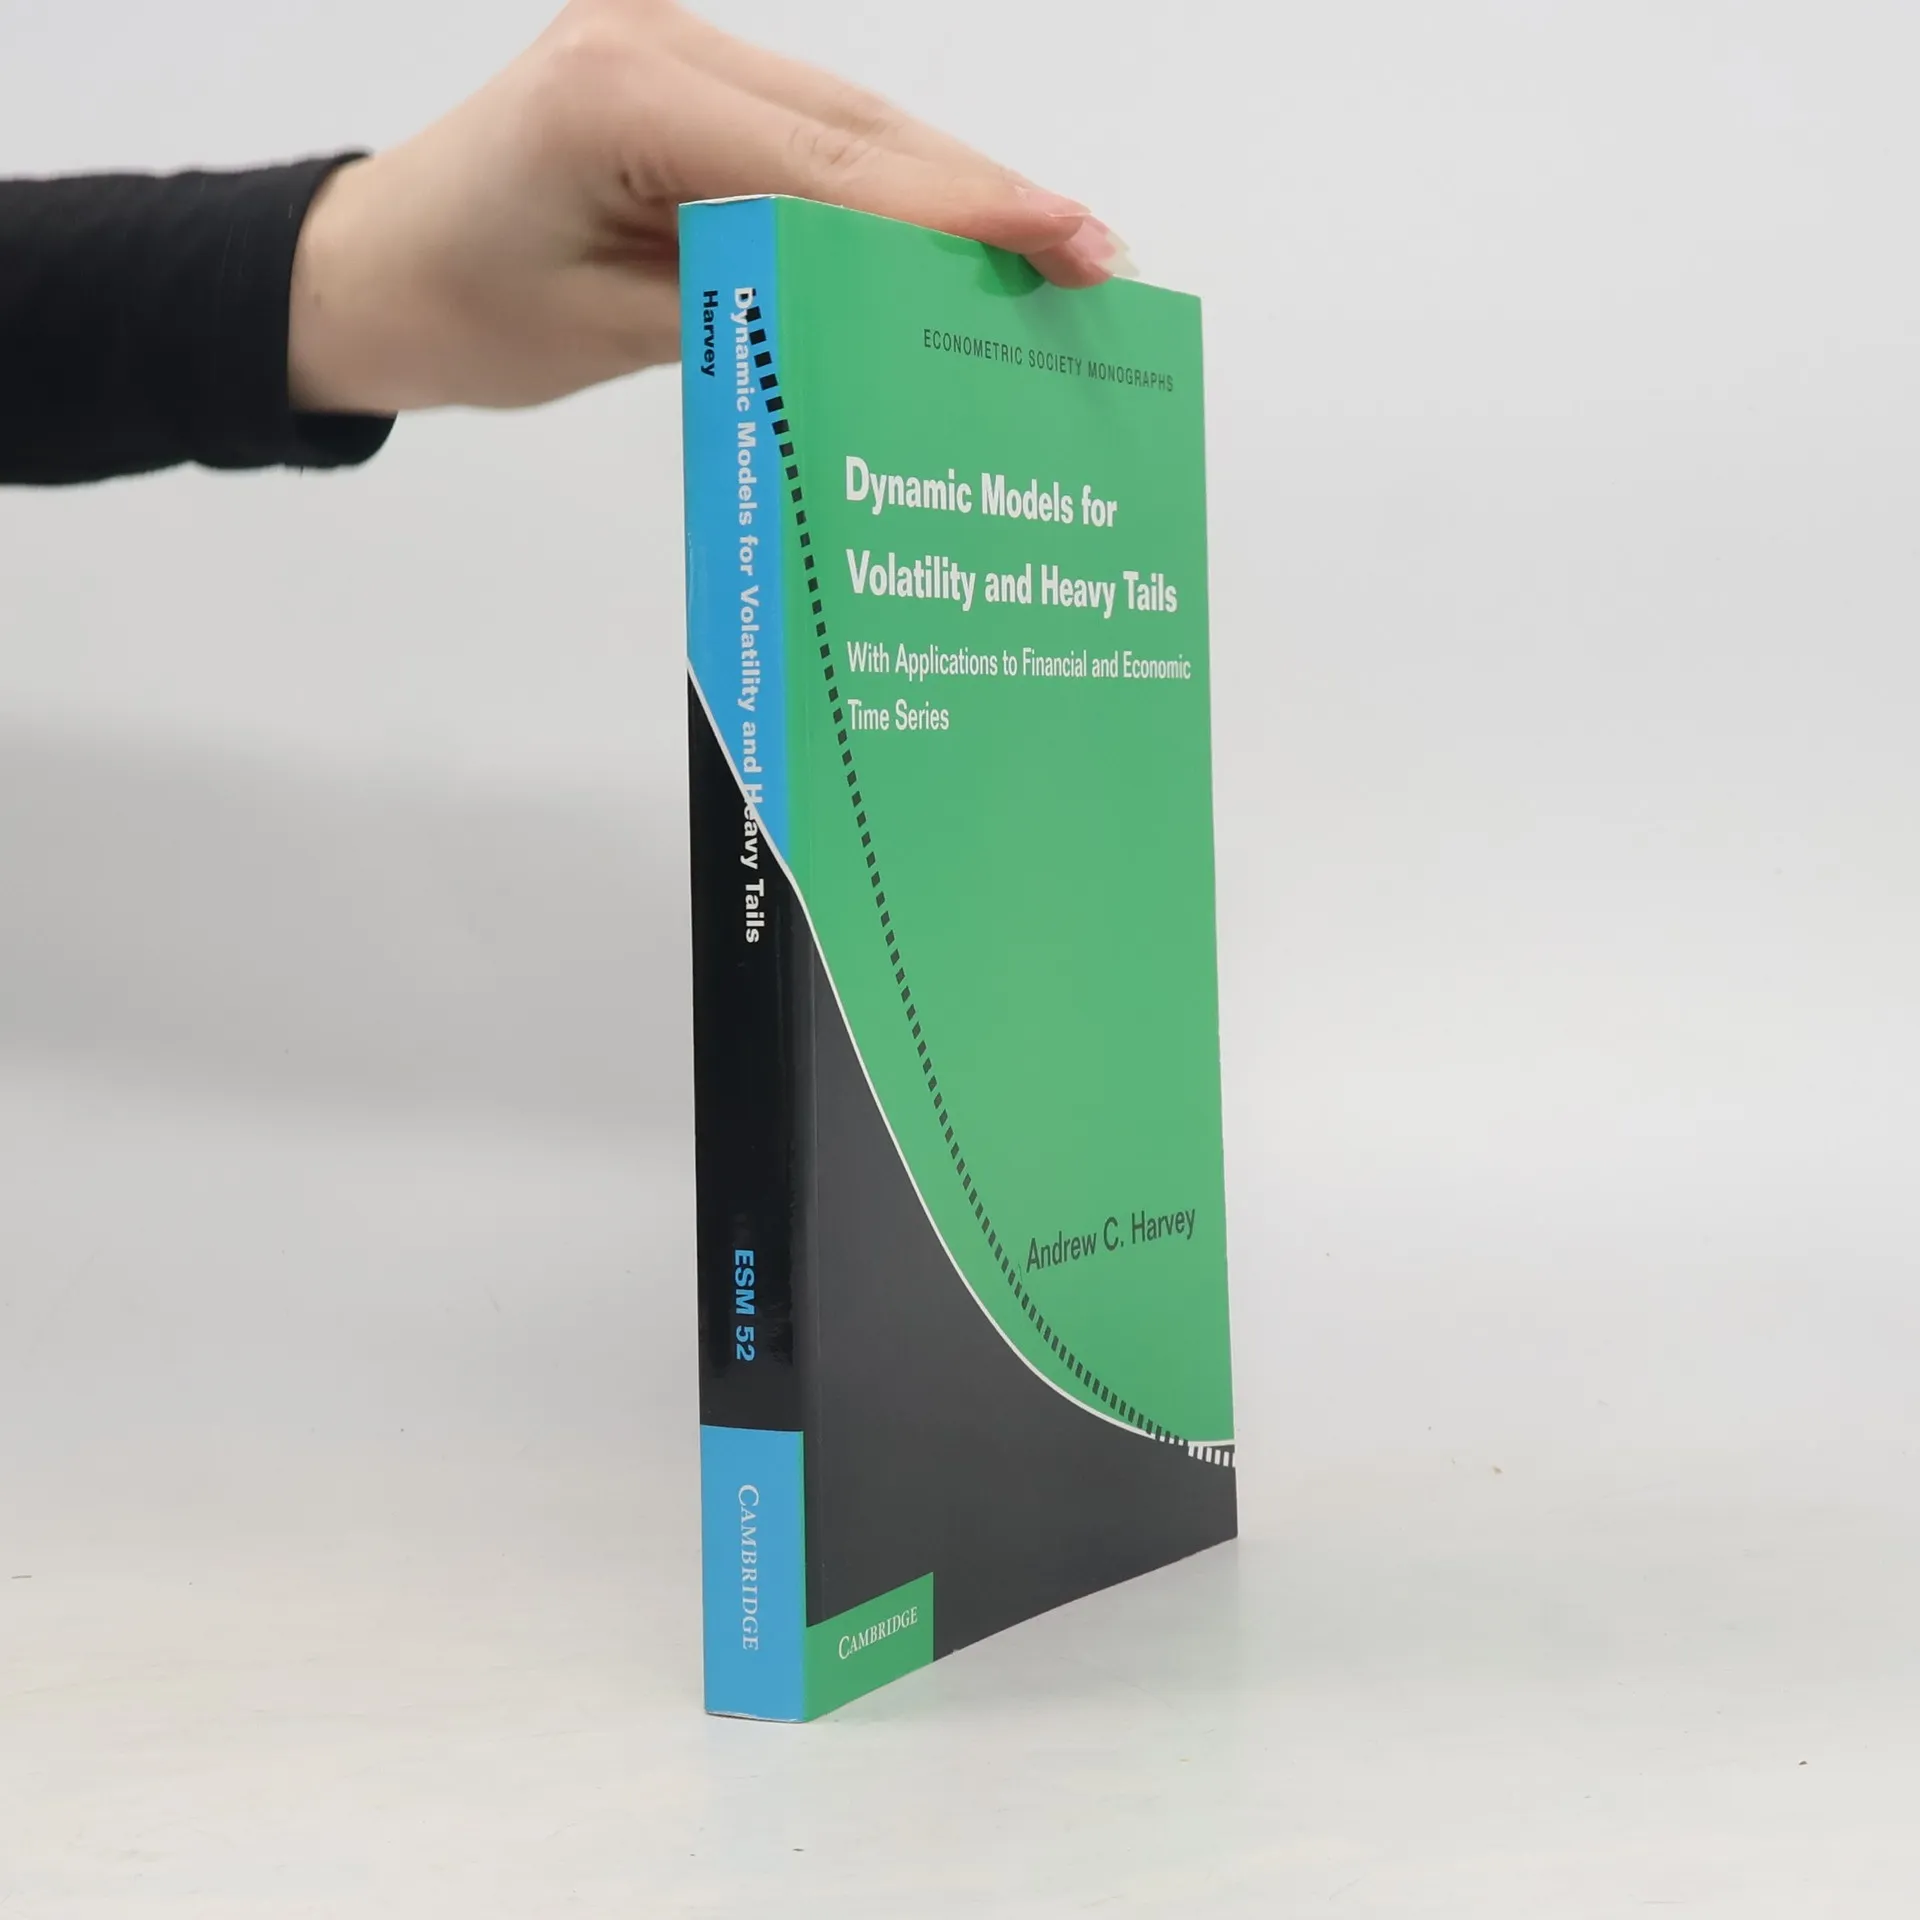
Dynamic Models for Volatility and Heavy Tails, Andrew C. Harvey
- Język

- Rok wydania
- 2013
- Oprawa
- (miękka)
Metody płatności
Nikt jeszcze nie ocenił.
- Tytuł
- Dynamic Models for Volatility and Heavy Tails
- Podtytuł
- With Applications to Financial and Economic Time Series
- Język
- angielski
- Autorzy
- Andrew C. Harvey
- Wydawca
- Cambridge University Press
- Rok wydania
- 2013
- Oprawa
- miękka
- Liczba stron
- 282
- ISBN10
- 1107630029
- ISBN13
- 9781107630024
- Seria
- Kategorie
- Tagi
- Biznes
- Opis
- The volatility of financial returns changes over time and, for the last thirty years, Generalized Autoregressive Conditional Heteroscedasticity (GARCH) models have provided the principal means of analyzing, modeling, and monitoring such changes. Taking into account that financial returns typically exhibit heavy tails that is, extreme values can occur from time to time Andrew Harvey's new book shows how a small but radical change in the way GARCH models are formulated leads to a resolution of many of the theoretical problems inherent in the statistical theory. The approach can also be applied to other aspects of volatility, such as those arising from data on the range of returns and the time between trades. Furthermore, the more general class of Dynamic Conditional Score models extends to robust modeling of outliers in the levels of time series and to the treatment of time-varying relationships. As such, there are applications not only to financial data but also to macroeconomic time series and to time series in other disciplines. The statistical theory draws on basic principles of maximum likelihood estimation and, by doing so, leads to an elegant and unified treatment of nonlinear time-series modeling. The practical value of the proposed models is illustrated by fitting them to real data sets.