

Parametry
Więcej o książce
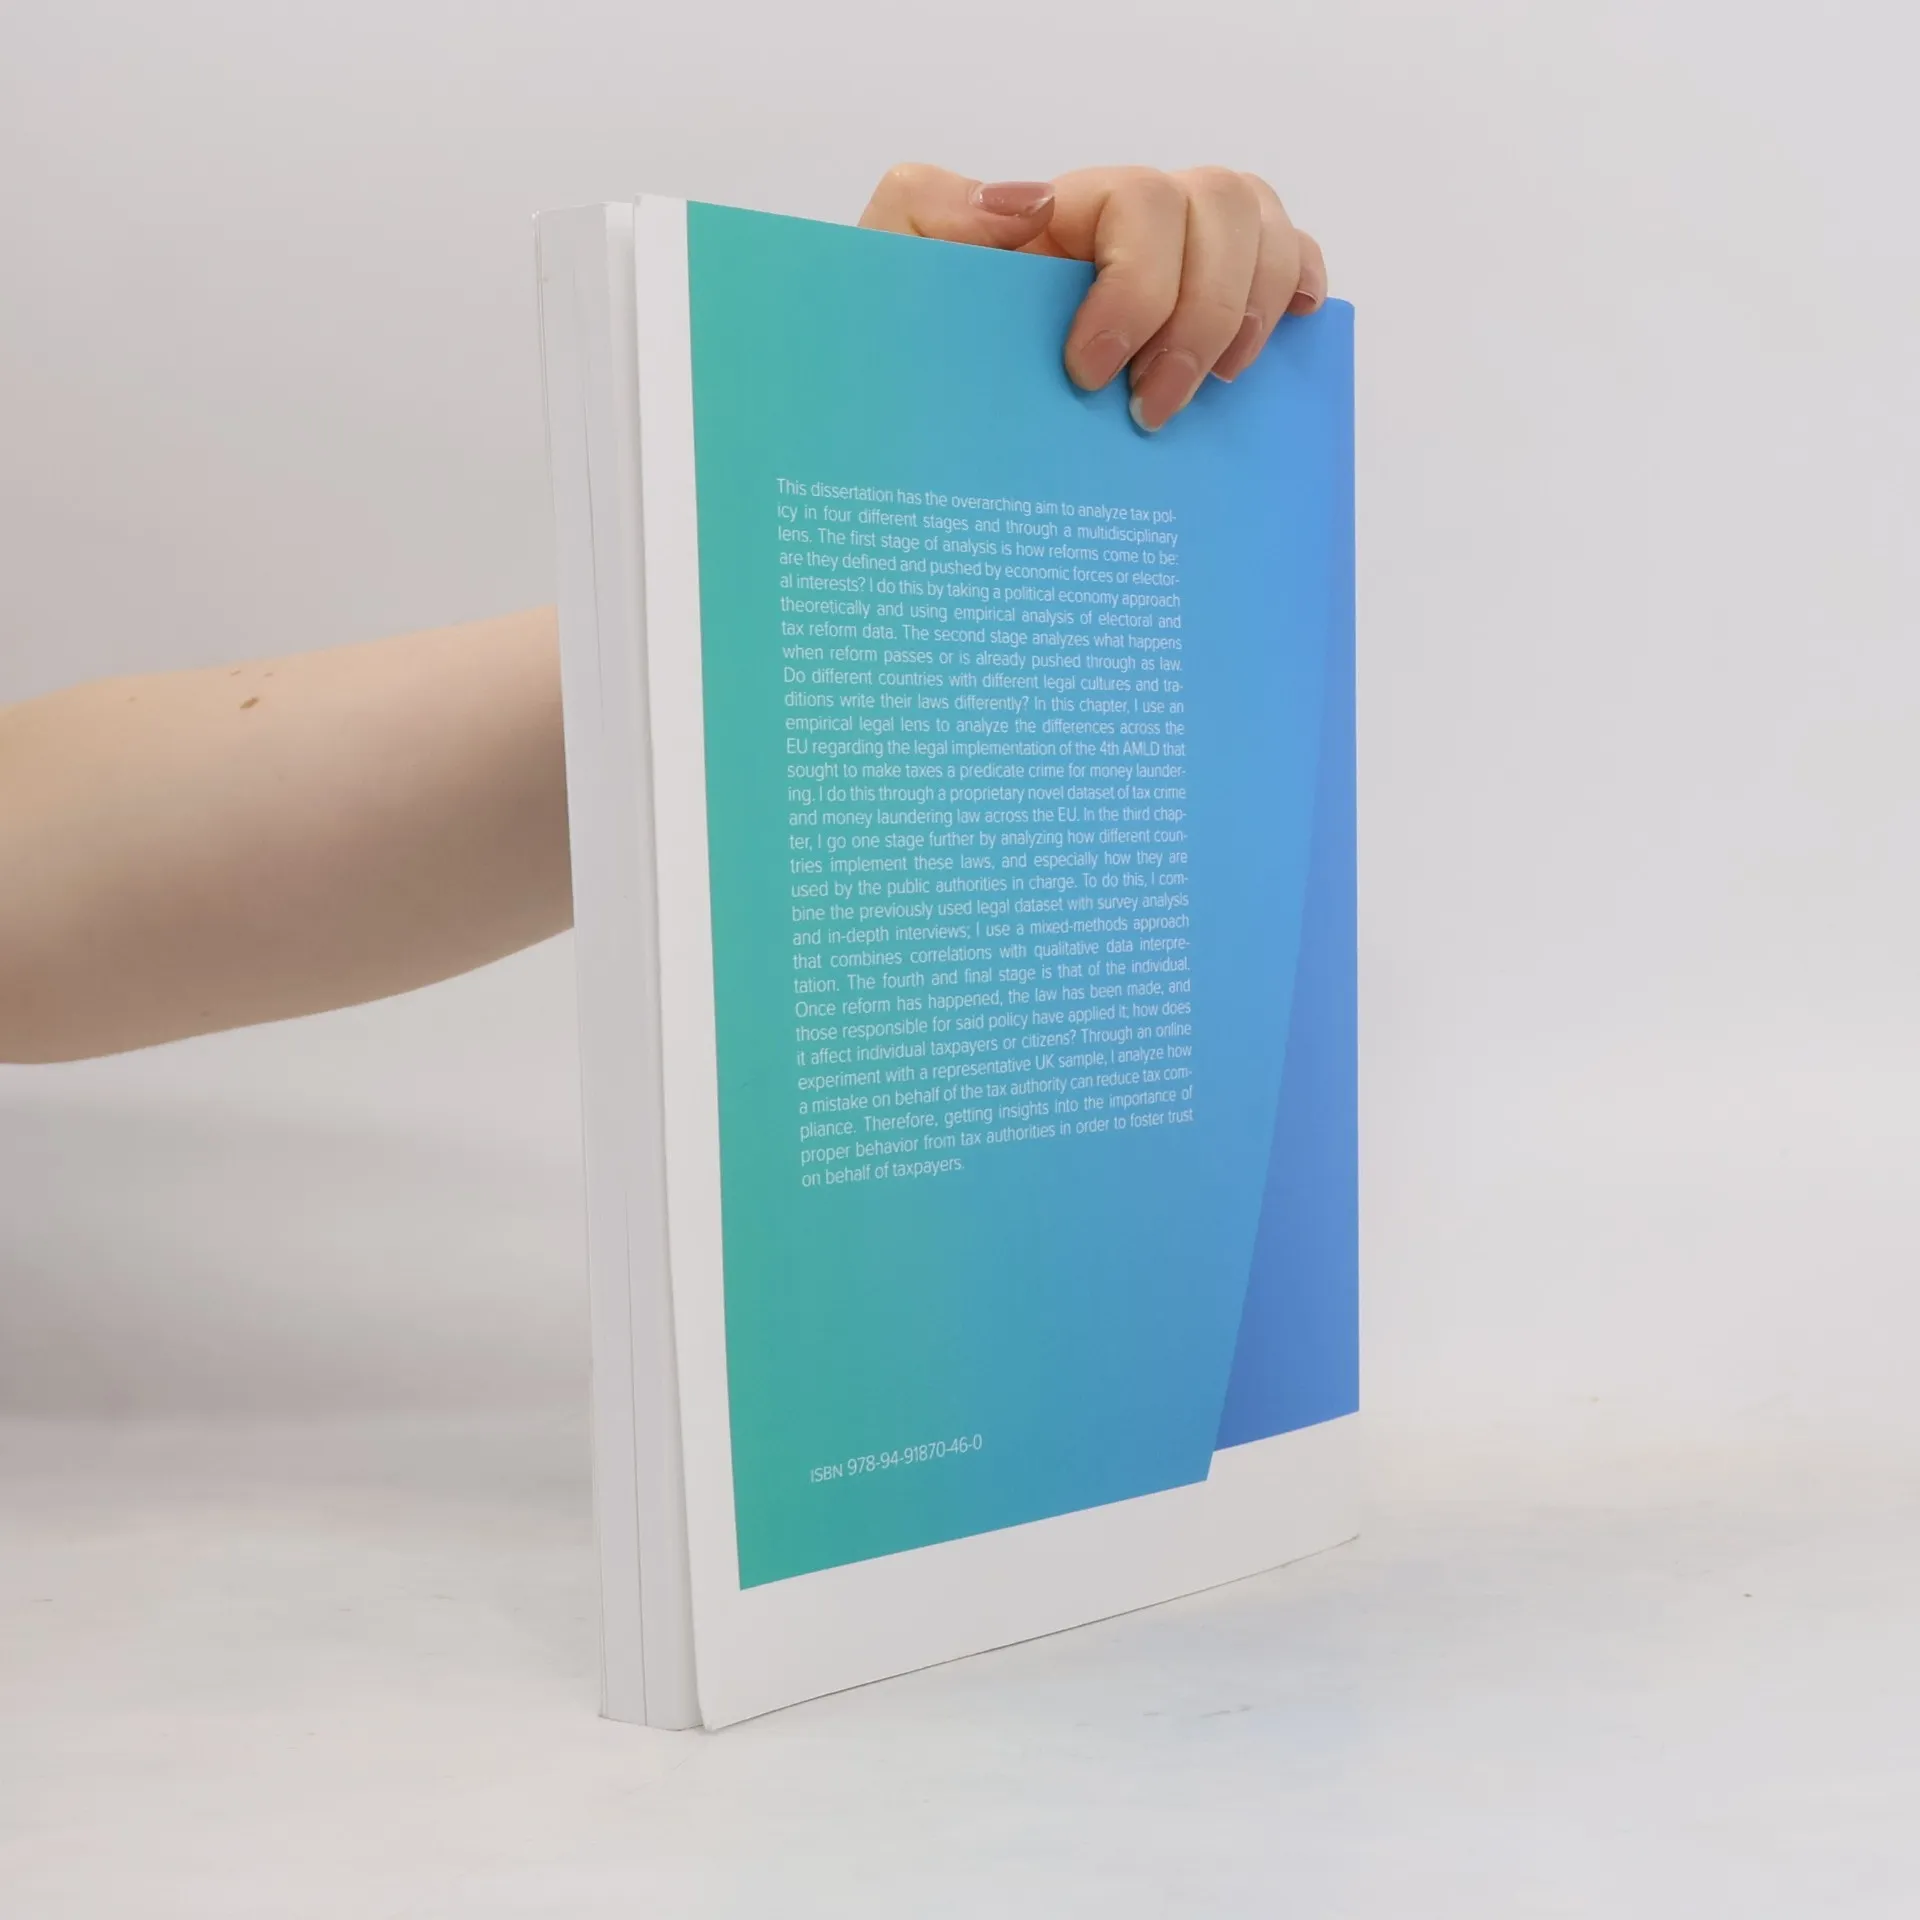
This dissertation aims to analyze tax policy across four stages through a multidisciplinary lens. The first stage examines how reforms emerge, questioning whether they are driven by economic forces or electoral interests. A political economy approach is employed, utilizing empirical analysis of electoral and tax reform data. The second stage investigates the legal drafting of reforms once they are enacted. It explores whether countries with varying legal cultures write their laws differently, specifically analyzing the EU's implementation of the 4th AMLD, which aimed to classify taxes as a predicate crime for money laundering. This analysis is supported by a novel dataset of tax crime and money laundering laws across the EU. The third chapter delves into how these laws are implemented by public authorities, employing a mixed-methods approach that combines legal data with survey analysis and in-depth interviews. The final stage focuses on the individual taxpayer's experience post-reform. An online experiment with a representative UK sample assesses how errors made by tax authorities can impact tax compliance. This highlights the significance of responsible behavior from tax authorities in fostering taxpayer trust.
Zakup książki
A Multidisciplinary Analysis of Tax Reform 062, Lucía Eugenia Rossel Flores
- Język


- Rok wydania
- Oprawa
- (miękka)
Metody płatności
Nikt jeszcze nie ocenił.
- Tytuł
- A Multidisciplinary Analysis of Tax Reform 062
- Podtytuł
- From Politics to Human Behavior
- Język
- angielski, holenderski
- Autorzy
- Lucía Eugenia Rossel Flores
- Oprawa
- miękka
- ISBN10
- 9491870467
- ISBN13
- 9789491870460
- Seria
- Kategorie
- Tagi
- Biznes, Tematy prawne
- Opis
- This dissertation aims to analyze tax policy across four stages through a multidisciplinary lens. The first stage examines how reforms emerge, questioning whether they are driven by economic forces or electoral interests. A political economy approach is employed, utilizing empirical analysis of electoral and tax reform data. The second stage investigates the legal drafting of reforms once they are enacted. It explores whether countries with varying legal cultures write their laws differently, specifically analyzing the EU's implementation of the 4th AMLD, which aimed to classify taxes as a predicate crime for money laundering. This analysis is supported by a novel dataset of tax crime and money laundering laws across the EU. The third chapter delves into how these laws are implemented by public authorities, employing a mixed-methods approach that combines legal data with survey analysis and in-depth interviews. The final stage focuses on the individual taxpayer's experience post-reform. An online experiment with a representative UK sample assesses how errors made by tax authorities can impact tax compliance. This highlights the significance of responsible behavior from tax authorities in fostering taxpayer trust.