



Parametry
- 756 stron
- 27 godzin czytania
Więcej o książce
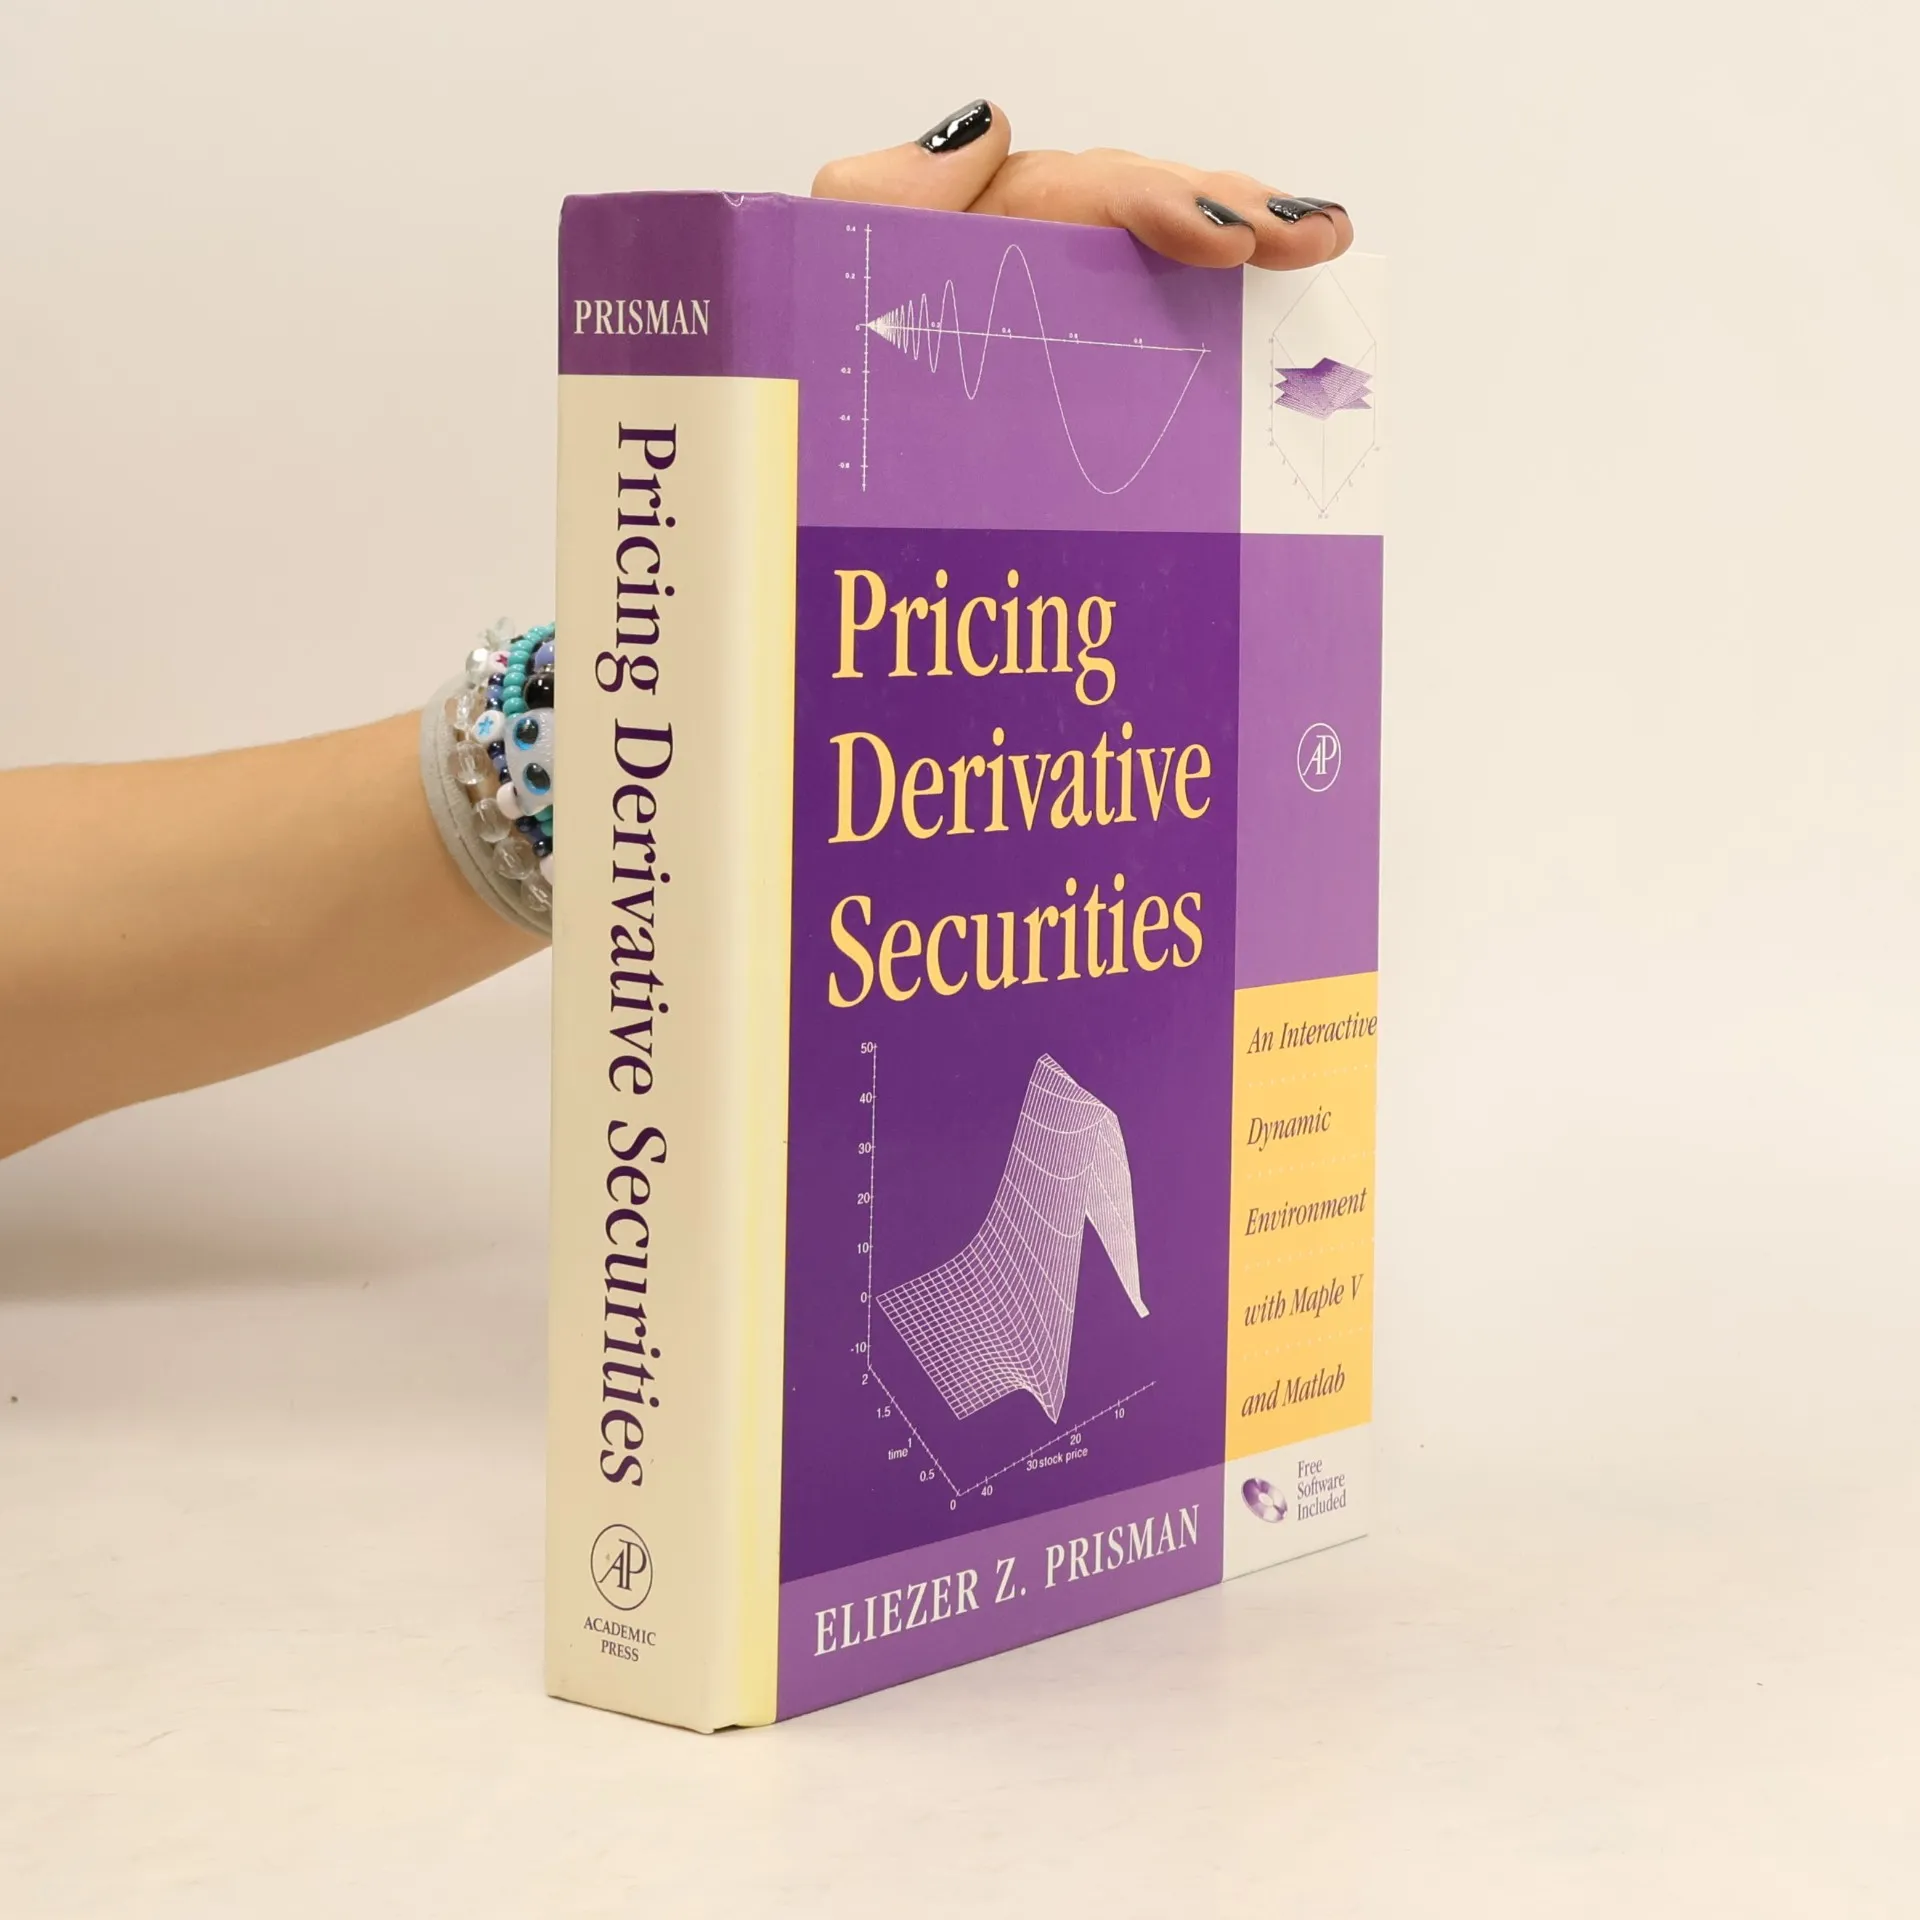
Pricing derivatives theory is brought to life in this interactive financial pricing experience. The book is driven by a no-arbitrage perspective within a one-period state-preference model, utilizing Maple® and Matlab® programs to help readers visualize payoffs and navigate various constraints. With clear explanations and rich illustrations, this resource teaches core theoretical concepts often obscured by complex terminology and institutional details. Readers can engage with the electronic packages indefinitely, using the book and its solutions manual as a tutorial to tackle increasingly complex problems. Key features include an enclosed CD-ROM with the student version of Maple V, offering a dynamic learning environment that encourages hands-on experience. Students can enhance their learning by modifying commands in online files, allowing for experimentation with applications and reader-generated examples alongside those provided. The book equips readers with the framework and tools based on the no free lunch concept to analyze various scenarios related to derivative securities, including those not explicitly covered. Basic concepts of stochastic calculus are illustrated through animations, simulations, and three-dimensional graphs, simplifying mathematical complexities. Additionally, the MATLAB® Graphic User Interface brings theoretical material to life, enhancing the learning experience.
Zakup książki
Pricing Derivative Securities, Eliezer Z. Prisman
- Język

- Rok wydania
- 2000
- Oprawa
- (twarda),
- Stan książki
- Uszkodzony
- Cena
- 69,99 zł
Metody płatności
Nikt jeszcze nie ocenił.
- Tytuł
- Pricing Derivative Securities
- Podtytuł
- An Interactive, Dynamic Environment with Maple V and Matlab - Free Software Included
- Język
- angielski
- Autorzy
- Eliezer Z. Prisman
- Wydawca
- Academic press
- Rok wydania
- 2000
- Oprawa
- twarda
- Liczba stron
- 756
- ISBN10
- 0125649150
- ISBN13
- 9780125649155
- Seria
- Kategorie
- Opis
- Pricing derivatives theory is brought to life in this interactive financial pricing experience. The book is driven by a no-arbitrage perspective within a one-period state-preference model, utilizing Maple® and Matlab® programs to help readers visualize payoffs and navigate various constraints. With clear explanations and rich illustrations, this resource teaches core theoretical concepts often obscured by complex terminology and institutional details. Readers can engage with the electronic packages indefinitely, using the book and its solutions manual as a tutorial to tackle increasingly complex problems. Key features include an enclosed CD-ROM with the student version of Maple V, offering a dynamic learning environment that encourages hands-on experience. Students can enhance their learning by modifying commands in online files, allowing for experimentation with applications and reader-generated examples alongside those provided. The book equips readers with the framework and tools based on the no free lunch concept to analyze various scenarios related to derivative securities, including those not explicitly covered. Basic concepts of stochastic calculus are illustrated through animations, simulations, and three-dimensional graphs, simplifying mathematical complexities. Additionally, the MATLAB® Graphic User Interface brings theoretical material to life, enhancing the learning experience.