Principles of Financial Engineering presents a fresh, original, informative, and up-to-date introduction to financial engineering. Rather than introducing financial instruments, this book describes the methods of synthetically creating assets in static and in dynamic environments, and shows how to use them. It offers clear links between intuition and underlying mathematics and an outstanding mixture of market insights and mathematical materials. It emphasizes developing methods that can be used to solve risk management, taxation, regulation, and above all, pricing problems. It explains issues involved in the day-to-day life of traders, using non-mathematical language. It provides a careful and concise analysis of the LIBOR market model and of volatility engineering problems. Exercises and case studies at end of each chapter as well as on-line Solutions Manual are available. This book will be a useful resource for anyone learning about practical elements of financial engineering. It can also serve as a resource for professionals and academics in all areas of quantitative finance. * Exercises and case studies at end of each chapter and on-line Solutions Manual provided* Explains issues involved in day-to-day life of traders, using language other than mathematics* Careful and concise analysis of the LIBOR market model and of volatility engineering problems
Salih N Neftci Książki


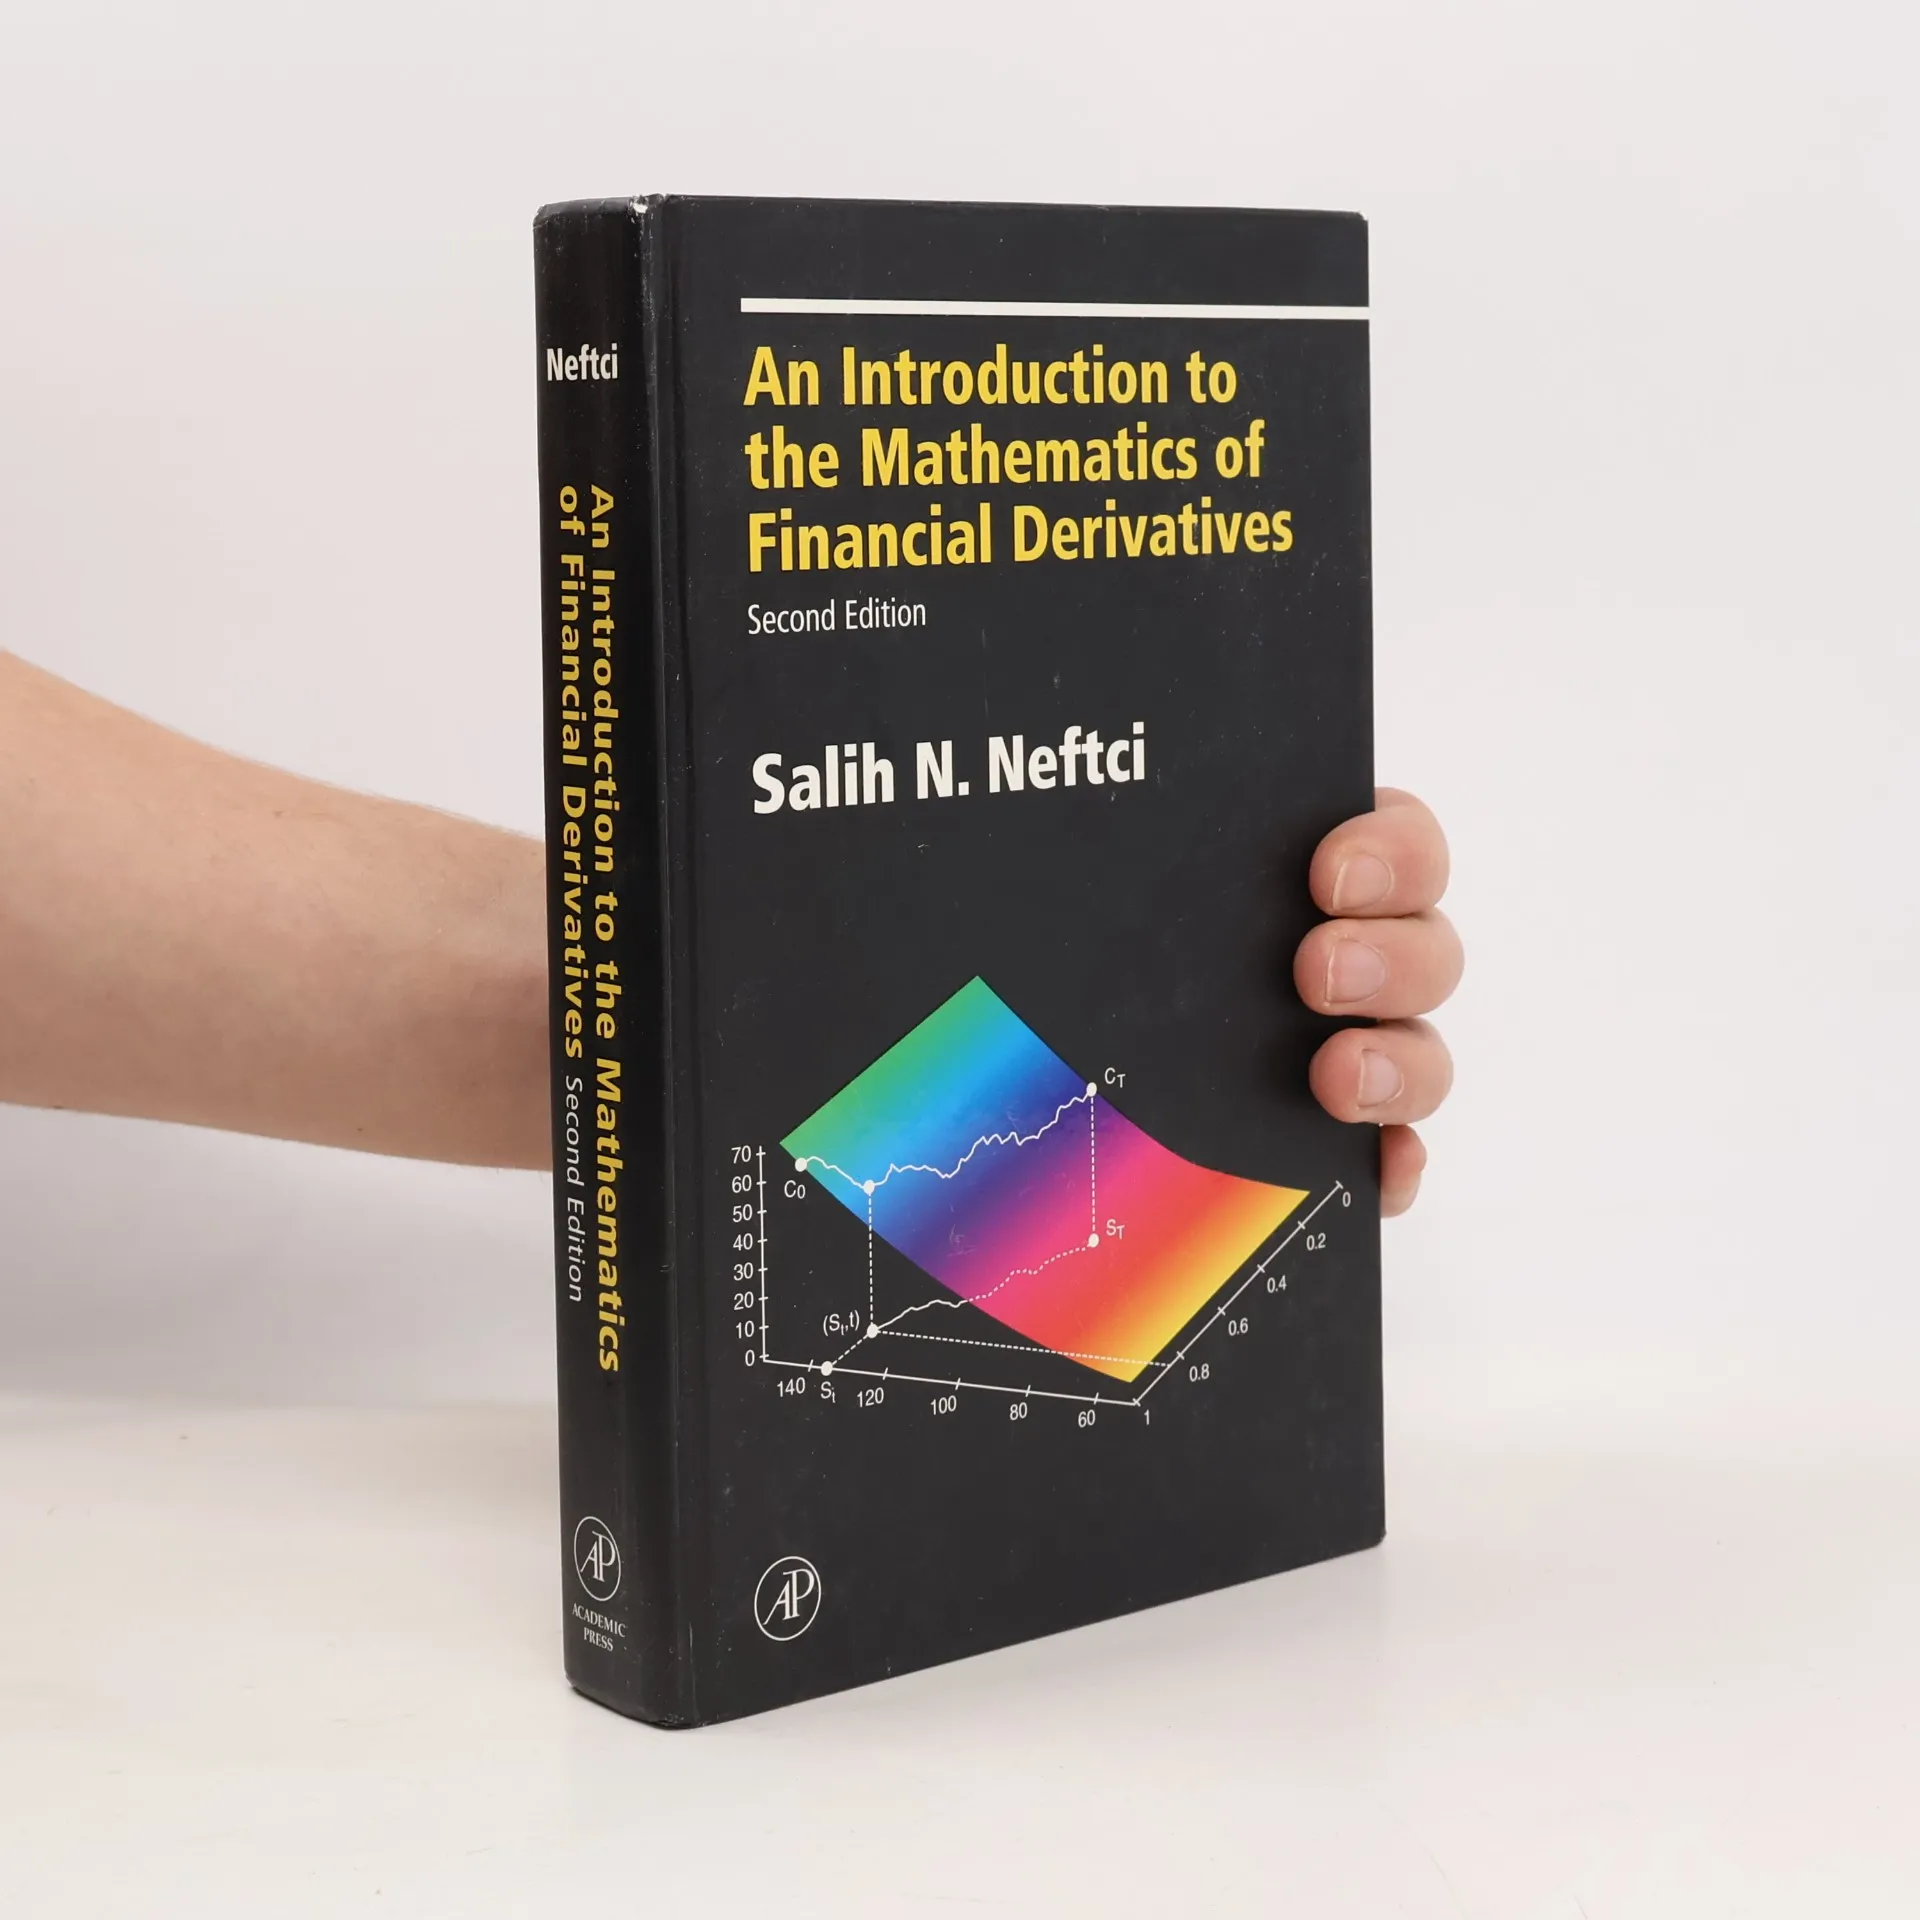
An Introduction to the Mathematics of Financial Derivatives
- 352 strony
- 13 godzin czytania
Using a systematic approach to the material, this text introduces the mathematics underlying the pricing of derivatives. The interest in dynamic pricing models is increasing due to their applicability to practical situations. With the freeing of exchange, interest rates, and capital controls, the markets for derivative products has matured, and pricing models have become more accurate. The resource should be of interest to professionals, Ph.D. students and advanced MBA students who are specifically interested in these financial products.
An Introduction to the Mathematics of Financial Derivatives - Second Edition
- 560 stron
- 20 godzin czytania
An Introduction to the Mathematics of Financial Derivatives, Second Edition, introduces the mathematics underlying the pricing of derivatives. The increased interest in dynamic pricing models stems from their applicability to practical with the freeing of exchange, interest rates, and capital controls, the market for derivative products has matured and pricing models have become more accurate. This updated edition has six new chapters and chapter-concluding exercises, plus one thoroughly expanded chapter. The text answers the need for a resource targeting professionals, Ph.D. students, and advanced MBA students who are specifically interested in financial derivatives. This edition is also designed to become the main text in first year masters and Ph.D. programs for certain courses, and will continue to be an important manual for market professionals and professionals with mathematical, technical, or physics backgrounds.